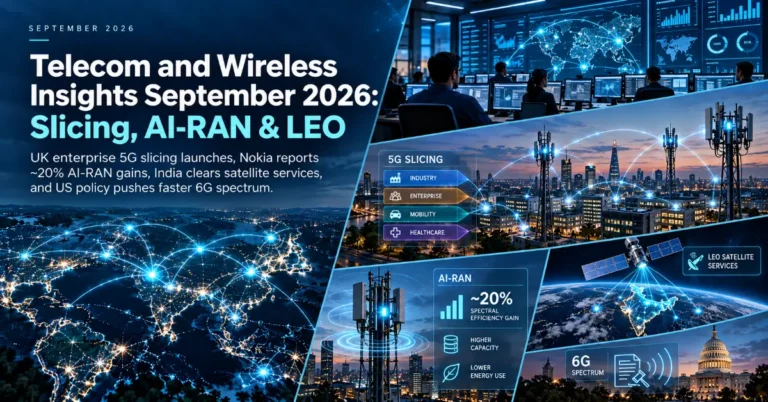
Advanced Connectivity Insights September 2026: 5G slicing and standalone services became products enterprises can buy, AI–RAN gathered multi-operator field results while the 6G path stayed open, satellite and NTN moved from licensing to service, FWA and broadband investment kept flowing into fibre supply, and spectrum policy tilted toward 6G.
At a glance – Advanced Connectivity Insights September 2026
- Slicing and premium connectivity went on sale: Vodafone Business launched the UK’s first national 5G+ slicing service for enterprises with a committed minimum 15 Mbps download rate, KT added app slicing, and AT&T launched Turbo Live paid priority at stadiums.
- AI–RAN gathered field results: Nokia reported about 20% spectral efficiency improvement in live trials with eight operators, while 3GPP deferred its 5G-to-6G migration decision and operators signalled 6G will arrive mostly as software on 5G spectrum and hardware.
- Satellite moved from licence to service: India cleared Starlink, Eutelsat OneWeb and Jio Satellite Communications, AT&T Business will bundle Amazon Project Kuiper with fibre and 5G, and O2 Business launched direct-to-device satellite for UK enterprises.
- Fibre supply locked in: AT&T signed a $3B+ multi-year deal with Corning and Verizon agreed a multi-billion-dollar Corning deal for more than 80 million miles of fibre for 2027–2032, as Cricket Wireless launched 5G FWA at $45 a month.
- Spectrum policy tilted to 6G: the US OMB overhauled federal spectrum repurposing to speed 6G auctions, CTIA called 4 GHz prime 6G spectrum, and the FCC scheduled a vote to open more than 1,000 MHz across 12GHz and 42GHz for satellite.
- Resilience and market structure moved: an external review confirmed a timing-system event caused Telstra’s national outage, and Poste Italiane lifted its Telecom Italia stake to about 86%.
1. Slicing, standalone 5G and premium connectivity become products
Operators turned slicing, standalone 5G and priority access into named products with prices and committed performance this month.
- Vodafone Business (UK): launched SuperMobile for Business, the UK’s first national 5G+ network slicing service for enterprises on the VodafoneThree network, with a dedicated slice isolated from consumer demand, up to 4x faster speeds than standard plans, a committed minimum 15 Mbps download rate, and uplink and downlink allocation for video, field operations and real-time reporting.
- KT (South Korea): added app slicing to separate work and personal traffic on the same device, with smartphone support from Samsung Electronics and Google, extended 5G SA slicing for closed enterprise and public-sector networks, and enabled VPN-less secure access through a portable “Egg” device.
- Verizon: set out its position favouring standardised end-to-end 5G SA slicing on its nationwide cloud-native core over isolated physical cores for public-safety and enterprise use, with application-specific SLAs for latency, bandwidth and reliability.
- India: Jio, Airtel and Vodafone Idea contested TRAI’s proposed quality-of-service benchmarks for 5G slicing on feasibility and measurement grounds, the next step after the per-slice rules covered in August.
- Premium venue connectivity: AT&T launched Turbo Live, paid priority mobile data at congested stadium moments, alongside AI fan features at AT&T Stadium; Movistar deployed high-capacity connectivity for San Diego Comic-Con Málaga; HPE is completing a Wi-Fi 7 and AI networking upgrade at Tottenham Hotspur Stadium; and Xfinity became the Baltimore Ravens’ Wi-Fi partner.
- Standalone and Open RAN build-out: NTT Docomo began commercial deployment of Nokia O-RAN-compliant multivendor base stations, prioritising cities, stadiums and venues; Ericsson will modernise about 85% of Nex-Tech Wireless’s RAN in rural Kansas and expand its cloud-native core for 5G SA over four years; T-Mobile and Reliance Jio completed 5G SA roaming using Syniverse’s platform; and Freshwave installed four 4G/5G small cells for VMO2 in Canterbury.
Why it matters for buyers: Vodafone’s committed 15 Mbps minimum is the kind of contractual number buyers can hold an operator to, and TRAI’s contested benchmarks show how hard measuring slice performance will be. Ask for the committed floor, how it is measured and what happens when it is missed. → Turn slice SLAs into scored vendor criteria with the TeckNexus RFP Scorecard Generator.
2. AI-RAN results arrive while the 6G path stays open
AI-RAN produced multi-operator field results this month, while standards bodies and operators kept their options open on how 6G arrives.
- Nokia: reported about 20% spectral efficiency improvement versus standard radio configurations in live field trials with A1 Group, Chunghwa Telecom, du, e&, Mobily, stc, TPG Telecom and Zain Saudi, with programmes ongoing at NTT Docomo production sites (trial results reported by Nokia).
- Where gains land: a Chetan Sharma Consulting study commissioned by Nokia found the strongest AI-RAN spectral efficiency gains are likely at dense, heavily loaded sites where GPU economics are most favourable, with ASIC-based platforms potentially better suited elsewhere.
- Architecture choices: Nokia is backing the O-RAN E3 interface and dApps for real-time RAN applications in spectrum efficiency, sensing and location, while Ericsson continues to prioritise rApps for network automation; NVIDIA signalled plans for an AI-RAN 6G radio unit chip.
- 6G path: 3GPP deferred its decision on 5G-to-6G migration options at its Madrid plenary after members could not agree which options to support, and industry reporting indicates operators plan to introduce 6G mainly through software upgrades on existing 5G spectrum, RAN and vendors.
- Early 6G work: Verizon applied for an experimental 4 GHz licence to demonstrate 5G sensing with Ericsson and Samsung as groundwork for 6G, and added AWS, Cisco, Intel, Keysight, MediaTek, Nvidia, Palo Alto Networks, Rohde & Schwarz and Viavi to its 6G Innovation Forum; Ericsson’s 2026 Technology and Telecoms Trends report highlighted physical AI, quantum-resilient security, programmable networks and heterogeneous compute.
- Tools and devices: Nokia opened a live testing hub for cloud-native core, automation, network APIs and AI-driven operations; Samsung’s Network in a Server now runs vRAN and 5G SA core on a Supermicro Compact Edge Server; and Quectel unveiled the RG660Qx 5G module on Qualcomm X85/X82 for FRMCS rail, supporting the GSM-R to 5G migration planned by 2030. Operator AI agents and autonomy are covered in the companion AI & Automation Insights.
Why it matters for buyers: about 20% spectral efficiency is now reported across eight operators, but the gains depend on site load, so the business case is site-by-site, not network-wide. With 6G expected largely as software on 5G hardware, today’s RAN choices will carry forward. → Model where AI-RAN gains justify the compute with the TeckNexus Network Planning tools.
3. Satellite and NTN move from licences to services
Satellite connectivity gained licences, bundles and trials this month, with India’s market opening the largest new door.
- India: the government cleared Starlink, Eutelsat OneWeb and Jio Satellite Communications to start satcom services, and plans a 5% spectrum usage charge for satellite operators that could speed LEO and MEO broadband launches; Jio separately plans a 30–32 satellite LEO constellation over India with 100–150 Gbps per satellite for 4–4.8 Tbps in total (plan), compared with Starlink’s approved 600 Gbps and Amazon’s 3 Tbps application.
- AT&T Business & Amazon Project Kuiper: AT&T will integrate Kuiper LEO service with its fibre and 5G networks as a fully managed, single-bill offer for US enterprise and public-sector customers, with AT&T supplying equipment and 24/7 support.
- O2 Business (UK): launched O2 Satellite for Business, a direct-to-device service extending coverage beyond O2’s mobile network, focused on rural locations.
- Trials and plans: Eutelsat trialled OneWeb LEO connectivity on PKP Intercity services in Poland at up to 160 km/h, with ACO Solutions leading deployment and Hispasat as distribution partner; SoftBank and Sceye completed a stratospheric HAPS trial over Japan covering voice, messaging, video, drone links and edge computing, ahead of a commercial launch targeted for 2027; and SpaceX’s CFO said Starlink aims to launch mobile satellite services in the first half of 2028 (plan).
- Ecosystem: Space42 and Viasat committed $1 billion to form the Equatys shared infrastructure venture; Iridium stockholders approved its acquisition by Rocket Lab with 99.6% of votes; Orange International Networks is hosting a new LEO gateway at its Bercenay-en-Othe teleport; SES signed a multi-year deal to distribute JioStar channels on IS-20; and Deutsche Telekom, Orange, Vodafone and Telefónica are exploring a consortium bid for EU satellite spectrum.
- Satellite IoT: Particle by Digi’s M635e gained Skylo certification for NTN alongside LTE-M, Wi-Fi and Bluetooth with automatic satellite fallback; Sateliot stressed standards-based interoperability between terrestrial networks and its LEO constellation; and John Deere is shipping autonomous trucks with factory-fitted satellite connectivity.
Why it matters for buyers: satellite is now sold as part of operator bundles and managed services, not only direct from constellation owners, which changes who buyers contract with and who carries the SLA. India’s approvals make it the market to watch for LEO pricing. → Compare satellite, terrestrial and hybrid coverage options with the TeckNexus Technology Selector.
4. FWA, fibre and broadband lock in supply and pricing
Fibre supply deals, new FWA pricing and cable upgrades shaped broadband investment this month.
- Fibre supply: AT&T signed a multi-year agreement worth more than $3 billion with Corning for optical fibre and cable, and Verizon and Corning agreed a multi-billion-dollar deal for more than 80 million miles of high-density fibre for 2027–2032, alongside Meta and Amazon commitments to expand fibre manufacturing capacity.
- Fibre investment: Rightfiber secured a $1.6 billion credit facility for network expansion and potential M&A, and TDS Telecommunications completed its purchase of Granite State Communications’ fibre and voice operations, adding more than 11,000 New Hampshire service addresses.
- Fixed wireless: Cricket Wireless launched 5G FWA home internet at $45 a month standalone or $75 bundled with mobile; Tarana Wireless is preparing UK FWA capacity trials as Ofcom moves to open upper 6GHz; and GlobalLogic launched an AI-native test automation kit for 5G FWA.
- Cable: CableLabs says DOCSIS 4.0 supplier certification is nearing completion after more than three years of testing, and MaxLinear launched Puma 9 CPE silicon for DOCSIS 3.1, D3.1+ and 4.0, targeting up to 50% lower CPE cost (target).
- Network modernisation: AT&T is automating operations, decommissioning its copper landline network and replacing hardware in thousands of central hubs with DriveNets cloud-native software while focusing investment on fibre and wireless; AT&T also sued Charter over “fiber-powered” claims for HFC broadband.
- Competition and services: Ofcom blocked a discount in Openreach’s wholesale pricing as UK altnets pushed back on its pricing; Onivia signed an MVNO deal with Vodafone Spain to add mobile to its wholesale catalogue; Lumen launched Intelligent Internet with on-demand bandwidth through Lumen Connect or APIs; and Deutsche Telekom launched T-Travel eSIM data for 200+ destinations.
Why it matters for buyers: operators locking in fibre through 2032 signals confidence that fibre stays the long-term access and backhaul choice, while $45 FWA keeps price pressure on where fibre isn’t built. Buyers should weigh both on a market-by-market basis. → Compare fibre, FWA and cable economics with the TeckNexus ROI/TCO tools.
5. Spectrum and policy tilt toward 6G
US spectrum policy moved to speed 6G, while regulators elsewhere set rules for satellite, unlicensed and consumer services.
- US 6G spectrum: the Office of Management and Budget issued a memorandum reforming interagency procedures to speed federal spectrum repurposing for 6G auctions; CTIA called the 4 GHz band prime 6G mid-band spectrum and urged swift repurposing; ATIS published a Next G Alliance whitepaper on spectrum needed for commercial 6G by 2030; and the FCC’s Brendan Carr said upcoming auctions are intended to enable competition beyond the three largest carriers.
- Mid-band capacity: AT&T leased 55 3.45GHz licences across about 25 markets from N Squared II, to be activated on radios already at existing sites, and petitioned the FCC to allow 2W EIRP operation for 3.45 GHz devices.
- Satellite and unlicensed: the FCC scheduled a vote on a Satellite Spectrum Abundance Order to unlock more than 1,000 MHz across 12GHz and 42GHz; ITU WRC-27 will consider spectrum approaches for NTN and direct-to-device; the UAE is moving upper 6 GHz from trials to commercial deployment by the second half of 2026; analyst Dean Bubley warned that changing the US 6GHz status would strand equipment; and WCRN petitioned the FCC to allow voluntary 5G Broadcast by low-power TV stations.
- US broadband programmes: NTIA directed leftover BEAD funds to further BEAD bidding; GAO urged the FCC and NTIA to improve broadband map accuracy and BEAD sustainability; SpaceX asked the FCC to retire USF High-Cost support; industry groups urged lower permit fees and shorter shot clocks while municipalities opposed; and CTIA, USTelecom and NCTA sought FCC waivers for minor hardware changes to approved routers.
- Elsewhere: Ofcom is reviewing the UK mobile market framework as operators call for easier planning and net neutrality changes; TRAI directed operators to offer lower-cost voice-and-SMS-only plans; and India’s Department of Telecommunications is assessing the cost of replacing legacy Huawei and ZTE equipment deployed before trusted-source rules.
Why it matters for buyers: the US is moving fastest to prepare 6G spectrum, with 4 GHz and federal bands in focus, while upper 6 GHz policy is splitting between licensed and unlicensed use across markets. Spectrum timing will shape when 6G investment makes sense. → Build spectrum and policy risk into vendor and market evaluations with the TeckNexus RFP Scorecard Generator.
6. Resilience, security and market structure
Outage reviews, security research and a run of deals and leadership changes reshaped the operator landscape this month.
- Resilience: an external review by Technology Audit Partners confirmed a technical event in Telstra’s network timing system caused its Australia-wide mobile outage, and the Australian Government signalled plans to strengthen network resilience after an Optus outage; research from Economist Enterprise supported by AT&T Business found nine in ten mid-sized and large US enterprises miss third-party disruptions until operations are affected (survey of 1,020 executives), and Arelion research found 58% of enterprise leaders slowed or safeguarded initiatives over network provider concerns (survey).
- Security: researchers unveiled 5G-Shark, a technique that lures phones onto rogue 5G cells without jamming to expose identifiers and force downgrades; Bharti Airtel’s Safe Network blocked more than 1.62 million malicious links; and BT Business is supporting British Transport Police drone operations with EE connectivity across the UK rail network, scaling over two years.
- M&A: Poste Italiane lifted its Telecom Italia stake to just under 86% through its tender offer, advancing a take-private plan; Keppel is in talks with StarHub on a potential sale of M1, which would be Singapore’s first telecom consolidation; Airspan is acquiring the bulk of Cambium Networks’ product lines and hiring more than 135 Cambium staff; and Elliott Management is pressing Deutsche Telekom to drop its plan for full control of T-Mobile US.
- Sharing and platforms: Vodafone and Digicel agreed tower site access for co-location; Síminn and Comarch extended their agreement to modernise digital service launches in Iceland; Komatsu expanded Komtrax telematics in Saudi Arabia with NTT Docomo Business and STC Group; and Cosmote Telekom is rebranding to Telekom in Greece.
- Leadership: Deutsche Telekom appointed former AWS executive Jan Hofmeyr as CTO as CFO Christian Illek prepares to retire; T-Mobile US named Jessica Uhl CFO Designate; Charter CFO Jessica Fischer leaves on 15 October to join a Google–Blackstone AI data centre venture; Crown Castle announced CFO and COO changes; Mediacom appointed Gavin Throckmorton to lead mobile strategy; and Calix named Juergen Lindner CMO.
Why it matters for buyers: a single timing-system event took down a national network, and surveys show most enterprises don’t see third-party failures coming. Resilience evidence, not just coverage and speed, belongs in every connectivity evaluation. → Compare resilient architecture and provider options with the TeckNexus Technology Selector.
What Advanced Connectivity Insights for September 2026 means if you’re planning network investment
September’s throughline is connectivity being sold on commitments: committed slice speeds, managed satellite bundles, fibre secured through 2032 and spectrum lined up for 6G. Six moves follow directly from the month:
- Buy slices on committed numbers — Vodafone Business’s 15 Mbps floor sets a benchmark; ask how it is measured and enforced.
- Treat AI-RAN as a site-by-site business case — Nokia’s about 20% gains across eight operators are strongest at dense, loaded sites.
- Plan 6G as an evolution of today’s RAN — 3GPP’s deferred migration decision and software-led 6G plans mean current choices carry forward.
- Add satellite through the operators you already use — AT&T with Kuiper and O2’s direct-to-device offer bring LEO into managed bundles.
- Weigh FWA and fibre per market — $45 FWA and fibre supply deals through 2032 both shape where each wins.
- Make resilience an explicit evaluation criterion — Telstra’s timing-system outage and enterprise surveys show the cost of single points of failure.
For AI agents and autonomous operations, see the companion AI & Automation Insights, September 2026; for enterprise deployments, see Private Network Insights, September 2026.
Catching up? Last month’s signal is here: Slicing Goes Regulatory, Satellites Multiply: Advanced Connectivity Insights, August 2026 →
This analysis is drawn from TeckNexus’s full curated Advanced Connectivity Monthly Insights for September 2026. See every deployment, product, and partnership update →