Private Network
Intelligence
Intelligence Journeys
Utilities Private Broadband Planning
AI Use Case Planning for Utilities

Digital Infrastructure

Intelligence Tools

Use TeckNexus intelligence tools to assess readiness, compare deployment models, prioritize use cases, evaluate risk, and build stronger business cases for AI use cases, private 5G, LTE, edge, and secure industrial connectivity.

AIDigital Infrastructure

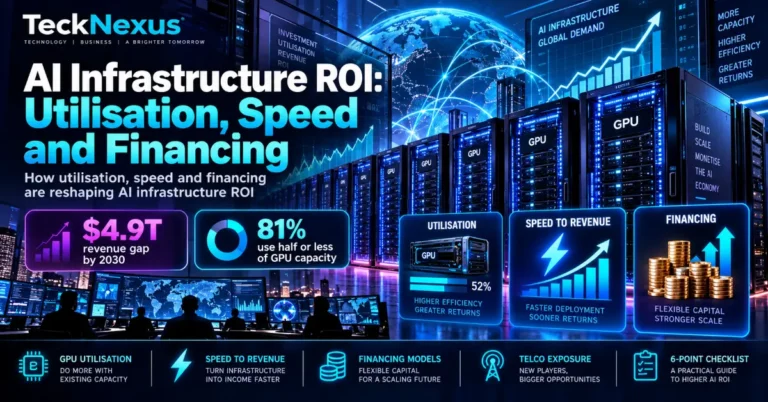
The AI Infrastructure ROI Reckoning: Utilisation, Speed and Smarter Financing

Gartner estimates a $4.9 trillion gap between AI data centre capex and attributable revenue by 2030, while 81% of companies with AI in production use half or less of their GPU capacity. TeckNexus examines the three levers reshaping AI infrastructure ROI, utilisation, speed to revenue and financing, how telcos are ...

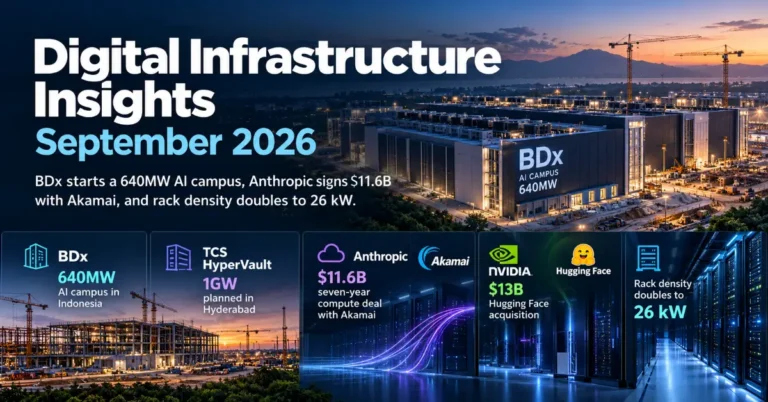
September 2026's roundup: BDx breaks ground on a 640MW AI campus in Indonesia and TCS's HyperVault plans 1GW in Hyderabad, Anthropic signs an $11.6B seven-year compute deal with Akamai, Nvidia confirms its $13B Hugging Face acquisition, and rack densities double as power and cooling set the pace....
AI clusters require dramatically more optical interconnect per unit of compute than previous data center generations, pulling transceiver speeds from 800G toward 1.6T and driving early adoption of co-packaged optics. TeckNexus examines the technology shift, why AI workloads consume so many more optical ports, and the electro-absorption laser supply constraint...
SK Hyper: Seeks to attract global technology companies to South Korea for AI training
Bloomberg | Oct 23 | Funding

SK Hyper: Seeks to attract global technology companies to South Korea for AI training

SK Hyper, a unit launched in July by SK Telecom, is promoting South Korea as a location for AI model training to draw international technology firms.
Carrier Invests $600 Million in Texas AI Data Center Cooling Plant
Wsj | Oct 23 | Industry Analysis

Carrier Invests $600 Million in Texas AI Data Center Cooling Plant

Carrier Global is investing more than $600 million in a new advanced manufacturing and engineering facility in Fort Worth, Texas, to meet surging demand for cooling infrastructure from AI data centers. The more than 1-million-square-foot plant will manufacture energy-efficient commercial chillers, with production expected to begin in 2027. The investment will more than triple Carrier's existing commercial chiller production capacity, targeting approximately 3,000 units annually and creating 1,500 jobs. With data center equipment sales projected to reach $2 billion in 2026, Carrier is strengthening its position in AI infrastructure cooling, advanced thermal management and sustainable data center operations as high-density computing workloads drive increasing cooling requirements.

Nscale: Faces data center delays, equipment failures, and power constraints
Bloomberg | Oct 23 | Industry Analysis

Nscale: Faces data center delays, equipment failures, and power constraints

Nscale is experiencing operational issues at certain data center sites, including project delays, equipment failures, and limited power availability, alongside investor-related pressures.
AI spending lifts Q1 2026 business fixed investment; data center construction accelerates
Policyarena | Oct 23 | Industry Analysis

AI spending lifts Q1 2026 business fixed investment; data center construction accelerates

Business fixed investment rose at an 11% annualized rate in Q1 2026, largely attributed to AI-related spending, with a notable uptick in data center construction.
HPE and Nvidia Expand Private Cloud AI with Vera CPU Rack for Agentic AI
Datacenterdynamics | Oct 23 | Feature Update

HPE and Nvidia Expand Private Cloud AI with Vera CPU Rack for Agentic AI

Hewlett Packard Enterprise (HPE) is expanding its Private Cloud AI platform in collaboration with Nvidia to accelerate enterprise agentic AI adoption and high-performance computing. The enhanced solution supports mixed Nvidia H200 and RTX PRO 6000 Blackwell GPU clusters, with KAI Scheduler optimizing resource allocation and workload placement. HPE also introduced a liquid-cooled Nvidia Vera CPU rack featuring 256 Vera processors, BlueField-4 DPUs and support for 22,500 AI agent sandboxes. According to HPE, the architecture delivers up to 80% faster agentic CPU performance, while Nvidia OpenShell and Sentry technologies strengthen security, governance and workload isolation. These innovations enable enterprises to scale AI inference, autonomous agents and hybrid AI infrastructure while maintaining control over sensitive data and operations.
Nutanix: Partners with NVIDIA, Supermicro, and Netris on AI infrastructure leveraging NVIDIA Spectrum-X Ethernet
Analyticsindiamag | Oct 23 | Partnership

Nutanix: Partners with NVIDIA, Supermicro, and Netris on AI infrastructure leveraging NVIDIA Spectrum-X Ethernet

Nutanix announced partnerships with NVIDIA, Supermicro, and Netris to offer AI infrastructure that integrates NVIDIA Spectrum-X Ethernet networking, aligning compute, networking, and software for enterprise AI deployments.
Crusoe: Secures $700M facility with Neuberger Specialty Finance to fund behind-the-meter power for AI factories
Crusoe | Oct 23 | Partnership

Crusoe: Secures $700M facility with Neuberger Specialty Finance to fund behind-the-meter power for AI factories

Crusoe obtained a $700M asset-backed financing facility from Neuberger Specialty Finance to purchase power generation equipment (behind-the-meter gas generators) for Crusoe-built and owned AI data centers. The facility is secured by recently ordered equipment and supports scaling of Crusoe’s AI factory platform, following a $3.9B Series F in Sep 2026 and over 6 GW of gross AI infrastructure capacity under contract. Customers cited include Microsoft, Google, Oracle, and OpenAI’s Stargate initiative.
WWT and Polarise Partner to Build 5MW Sovereign AI Data Center in Oslo
Datacentre | Oct 23 | Partnership

WWT and Polarise Partner to Build 5MW Sovereign AI Data Center in Oslo

World Wide Technology (WWT) and German AI infrastructure provider Polarise have announced a strategic partnership to accelerate sovereign AI data center development across Europe, beginning with a 5MW facility in Oslo, Norway. The new AI Factory will integrate Nvidia accelerated computing, liquid cooling and Polarise's full-stack AI cloud platform, with WWT serving as systems integrator. Building on Polarise's earlier AI cluster deployment in Munich, the collaboration aims to expand European-controlled AI computing capacity while supporting data sovereignty, enterprise AI inference and large-scale AI workloads. The partnership establishes a foundation for additional sovereign AI Factory deployments across Europe, strengthening regional AI infrastructure and digital independence.
TIM: Partners with NVIDIA to expand sovereign AI cloud and edge infrastructure in Italy
Decode39 | Oct 23 | Partnership

TIM: Partners with NVIDIA to expand sovereign AI cloud and edge infrastructure in Italy

TIM Enterprise will host a sovereign AI platform in Italy that integrates TIM’s centralized cloud and distributed edge network with NVIDIA’s full-stack AI, including GPUs, Nemotron models, and NeMo Guardrails. The platform provides managed services, data localization, access governance, security, and regulatory controls, and is supported by IPCEI CIS deployments of Edge Cloud nodes equipped with NVIDIA GPUs across Italy.

Frequently Asked Questions

What does "digital infrastructure" actually cover?

Digital infrastructure is the physical and logical foundation that computing, connectivity, and AI run on: data centers and the power and cooling that feed them, interconnection and colocation, subsea cables and fiber backbones, the semiconductors and memory inside the equipment, and the specialized facilities built for AI compute. The category has expanded well beyond traditional data centers and networks to include large GPU clusters, AI accelerators, sovereign cloud, and emerging concepts at the edges of the field. The common thread is that much of it is now being reshaped by demand for AI compute, which influences where capacity gets built, how it's powered, and who supplies the chips.

How is AI changing what gets built, and at what scale?

AI has shifted digital infrastructure from incremental growth toward very large, capital-intensive buildouts. Where capacity was once planned rack by rack, major AI projects are now scoped in hundreds of megawatts to multiple gigawatts of power, tied to access to large numbers of GPUs, and committed years in advance through long-term colocation and compute agreements. This scale pulls land, electricity, and chip supply into the center of infrastructure planning, and concentrates investment around sites that can support dense, power-hungry compute. For operators and enterprises, the practical implication is that AI capacity decisions increasingly resemble heavy-infrastructure projects rather than IT procurement.

Why is power becoming the main constraint on data center growth?

AI workloads are far more power-dense than traditional computing, so electricity supply, grid interconnection, and cooling now gate how fast capacity can come online. Increasingly, the binding question for a new build isn't whether chips are available but whether enough reliable, affordable power can be secured and the heat managed. Power and cooling design have become central evaluation criteria for large projects, and milestones like grid interconnection and on-site substations are now treated as critical path items. This also pushes sustainability and energy efficiency from a reporting exercise into a core siting and design decision, since power is both the main constraint and a major operating cost.

What's happening with the AI chip and memory supply chain?

The supply chain is both expanding and diversifying. Memory is advancing toward higher-bandwidth, more efficient high-bandwidth memory (HBM) generations to feed large AI systems. On accelerators, the market is gradually fragmenting beyond a single dominant supplier as hyperscalers invest in custom in-house silicon, even as leading GPUs still anchor most large clusters. Chip manufacturing is diversifying geographically and across foundries, driven by efforts to reduce reliance on a small number of suppliers and locations. The throughline is that AI compute demand is reshaping who makes the chips, what kind, and where they're made — a shift with direct consequences for cost, availability, and infrastructure planning.

Why are governments getting directly involved in chip and data center infrastructure?

Semiconductors and AI compute are increasingly treated as strategic national assets, so governments are intervening with funding, incentives, and sometimes direct equity stakes. The motivations are supply-chain security, reducing dependence on concentrated manufacturing, and capturing the economic value of building domestic capacity. National programs are funding new fabrication and packaging facilities, and policy is actively shaping where capacity gets built. The effect is that government strategy now influences the digital infrastructure map as much as commercial demand does, and infrastructure decisions increasingly carry geopolitical as well as economic weight.

What is sovereign cloud, and why does it keep coming up?

Sovereign cloud means cloud infrastructure operated so that data, control, and operations stay within a country's borders and under its legal jurisdiction, rather than depending entirely on foreign providers. It's gaining momentum as governments and regulated industries demand that sensitive workloads — increasingly including AI workloads — meet national data-residency and security requirements. Common models involve a global cloud provider partnering with a locally operated, legally independent entity staffed by local personnel to satisfy sovereignty rules. For operators and enterprises, sovereign cloud is becoming a distinct infrastructure category and a competitive opportunity, especially as AI raises the stakes around where data and models physically reside.

Where is digital infrastructure investment growing fastest geographically?

Capacity is expanding well beyond the established hubs. Asia-Pacific is especially active, with significant hyperscale and national AI infrastructure projects, and markets like India building both chip fabs and data center capacity. Other emerging regions are growing too, driven by demand for capacity closer to users, national strategies to build domestic infrastructure, and the search for sites with available power and favorable economics. The broad pattern is decentralization: rather than concentrating in a few traditional centers, investment is spreading toward locations that can offer power, land, connectivity, and supportive policy — reshaping the global map of where digital infrastructure lives.

What are the newest frontiers in digital infrastructure to watch?

Beyond conventional buildouts, several directions signal where the field is heading. Custom in-house AI silicon is gradually fragmenting the accelerator market away from a single dominant supplier. AI-optimized networking — low-latency, high-throughput links purpose-built to connect GPU clusters and data centers — is becoming its own category. General-purpose CPUs are expected to see renewed demand as agentic AI workloads grow alongside accelerators. And more speculative concepts continue to appear, including ideas like running AI workloads in orbit. For decision-makers, the practical signal is that digital infrastructure is broadening quickly, and the assumptions behind a build — power, chips, location, and networking — are shifting fast enough to warrant active tracking.

Partner Hubs

Telco AI Agent Leadership

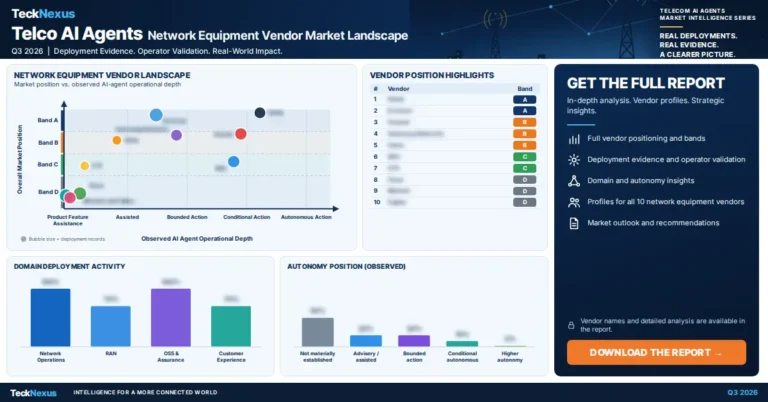
Telco AI Agent Leadership Landscape - Network Equipment Vendors
Network Equipment Vendor Report
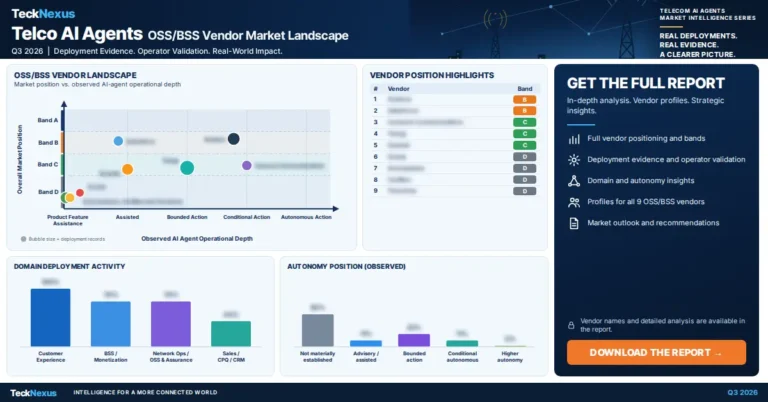
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
OSS/BSS Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
System Integrator Report
Scroll to Top