
AI Agent Competitive
Intelligence
Intelligence
Private Network
Intelligence
Intelligence
Intelligence Journeys
Utilities Private Broadband Planning
AI Use Case Planning for Utilities
Intelligence Tools
By Tool Type
▼
By Industry
▼
Access Type
▼
Resources
▼
Technology Hubs
▼
Partner Hubs
▼
Monthly Trackers
▼


Home » Digital Infrastructure
Digital Infrastructure
Semiconductors are the chips that make networks and devices work — from radio and baseband processors to the AI accelerators increasingly central to both network equipment and connected devices. Chip capability sets the ceiling on what networks and devices can do, determining which frequencies, features, and AI workloads are possible. The sector sits at the intersection of telecom, AI, and geopolitics, with supply chains, manufacturing capacity, and export controls shaping the broader technology landscape. For operators, enterprises, and vendors, semiconductor trends influence device capability, equipment cost, and the pace of AI adoption across networks. This channel covers semiconductors as they relate to connectivity and AI — chipsets for networks and devices, AI accelerators, and the supply-chain and geopolitical dynamics around them — with analysis of how chip developments enable or constrain the technologies built on top of them.
- Tech News & Insight
- October 15, 2026
- Canio Campaniello

Attackers rarely break 5G itself. They compromise corporate IT and pivot into private networks through weak boundaries. Here is how it works and how operators can close the path.
- Tech News & Insight
- October 5, 2026
- Hema Kadia
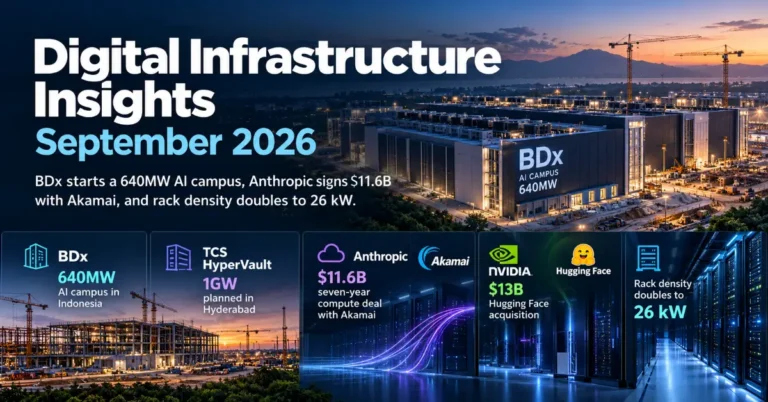
September 2026's roundup: BDx breaks ground on a 640MW AI campus in Indonesia and TCS's HyperVault plans 1GW in Hyderabad, Anthropic signs an $11.6B seven-year compute deal with Akamai, Nvidia confirms its $13B Hugging Face acquisition, and rack densities double as power and cooling set the pace.
- Tech News & Insight
- September 19, 2026
- Hema Kadia
AI clusters require dramatically more optical interconnect per unit of compute than previous data center generations, pulling transceiver speeds from 800G toward 1.6T and driving early adoption of co-packaged optics. TeckNexus examines the technology shift, why AI workloads consume so many more optical ports, and the electro-absorption laser supply constraint that has become a genuine lead-time risk for AI infrastructure buildouts.
- Tech News & Insight
- September 3, 2026
- Hema Kadia
August 2026's roundup: Nvidia forms $500B+ AI compute financing platforms with the world's largest asset managers, SK Telecom's SK Hyper data centre unit and Microsoft's new Hyderabad hyperscale region both go live, the custom silicon race widens to include OpenAI's own inference chip and a reported $12.9B Nvidia bid for Hugging Face, and SpaceX's infrastructure ambitions extend from a $16.8B Texas fab to orbital data centers.
- Tech News & Insight
- August 25, 2026
- Hema Kadia
Telecom operators cutting headcount while pouring capital into AI infrastructure, and chipmakers financing fabs at infrastructure scale, are two sides of the same reallocation. TeckNexus traces the connections across SK Telecom, KT, LG Uplus, T-Mobile, AT&T, Verizon, Nvidia, SK hynix, and SpaceX to show how the AI buildout has become the organising logic the telecom and semiconductor industries are restructuring around.
- Tech News & Insight
- August 21, 2026
- Hema Kadia
Ooredoo Group and Indosat Ooredoo Hutchison have each launched a branded Zankore GPU-as-a-Service platform in Southeast Asia, targeting 1 gigawatt of AI capacity with Nvidia and Nokia as technical partners. TeckNexus examines the capital structure behind the build, why telecom operators are a plausible GPU-as-a-Service provider in under-served regional markets, and the network-compute bundling trade-off buyers should think through before this kind of vendor relationship reaches their own procurement conversations.
- Tech News & Insight
- August 16, 2026
- Hema Kadia
A $5 billion investment tied to 2GW of compute deployment beginning H1 2027 isn't just financial news. It's a forward-looking signal about which AI capacity will actually be available to buyers, and when.
- Tech News & Insight
- August 10, 2026
- Hema Kadia
Ericsson is raising prices on new tenders and renegotiating existing contracts as AI-driven demand lifts component costs. Most supply agreements aren't built to absorb it automatically — which makes this a TCO modelling problem, not just a vendor's problem.
- Tech News & Insight
- August 2, 2026
- Hema Kadia
July 2026's roundup: TSMC raises its Arizona commitment to $265 billion, Micron commits more than $250 billion to US DRAM manufacturing through 2035, SK hynix's $26.5 billion Nasdaq listing prices and begins trading, and hyperscaler data center and interconnect infrastructure keeps expanding from Alberta to Google's dark fiber network.
- Tech News & Insight
- July 9, 2026
- Hema Kadia
Apple's $30 billion Broadcom chip deal is the largest single commitment under its American Manufacturing Program to date - 15 billion+ US-made chips, a $1.5 billion Fort Collins expansion, and a supply agreement running through 2031. Here's what's actually in the deal and what it signals for wireless and telecom supply chains.
- Tech News & Insight
- July 2, 2026
- Hema Kadia
June 2026's roundup: SK Group, GS Group, and Naver unveil a $650 billion, 10-year AI infrastructure megaproject, Google shifts part of its TPU manufacturing from TSMC to Intel, Nvidia diversifies its HBM4 supply chain, and AI data center capacity keeps expanding into new global markets from Indonesia to Paraguay.
Frequently Asked Questions
Why do telecom networks and devices depend so heavily on semiconductor advances?
Every part of the network, from smartphone modems to base station radios to data center servers running virtualized network functions, runs on chips, meaning advances or limitations in semiconductor technology directly determine what’s actually possible for network and device performance, energy efficiency, and cost. Faster, more efficient, and more specialized semiconductors translate directly into faster networks, longer device battery life, and lower operating costs for network infrastructure, while semiconductor limitations or supply constraints can directly slow down how quickly new network capabilities can actually reach commercial deployment. This deep dependency means semiconductor industry trends, often discussed as a somewhat separate topic, actually have direct, practical consequences for telecom network and device roadmaps.
What’s a 5G modem, and why does it matter which one a device uses?
A 5G modem is the specific chip responsible for handling a device’s cellular connection, managing tasks like connecting to available cell towers, processing the radio signal, and supporting whatever specific 5G features and frequency bands that particular chip was designed to handle. Different modems support different frequency bands, speeds, and power efficiency levels, which is why two phones with similar overall specifications can have meaningfully different real-world 5G performance, since the underlying modem chip’s capabilities determine what network features a device can actually access. Major modem chip manufacturers, including Qualcomm and MediaTek, compete heavily on these technical capabilities, releasing new modem generations somewhat ahead of when those features become broadly necessary.
How is AI demand affecting the semiconductor supply chain telecom relies on?
Surging demand for AI-capable chips, especially GPUs used for AI training and inference, is competing for the same manufacturing capacity and supply chains that produce networking and telecom semiconductors, creating pricing and availability pressure across the broader chip industry that indirectly affects telecom equipment and device costs. Semiconductor manufacturing capacity, particularly for the most advanced fabrication processes, is concentrated among a relatively small number of manufacturers globally, meaning a surge in demand from one major sector, like AI data center buildouts, can create ripple effects on availability and pricing for other sectors, including telecom, that rely on similar manufacturing capacity. This dynamic has become a meaningful factor in telecom equipment cost planning as AI infrastructure investment has accelerated.
Why are governments increasingly involved in semiconductor policy related to telecom?
Chips are considered critical infrastructure given their role in both networks and devices, leading governments to fund domestic semiconductor manufacturing and restrict certain chip exports, partly to reduce reliance on a small number of overseas suppliers and partly over genuine national security concerns about dependence on potentially adversarial countries for critical technology components. This has direct telecom relevance, since policies aimed at semiconductor supply chain security can affect the cost, availability, and sourcing options for the chips telecom equipment and device manufacturers rely on. Government semiconductor policy and telecom policy, like Open RAN supply chain diversification efforts, increasingly overlap, both driven by similar concerns about reducing dependence on a small number of geopolitically sensitive suppliers.
What’s the difference between a general-purpose chip and a specialized telecom chip?
A general-purpose chip, like a standard computer processor, is designed to handle a wide range of different computing tasks reasonably well, without being specifically optimized for any single function. A specialized telecom chip, by contrast, is purpose-built for a specific function within the network, like processing radio signals for a particular frequency band, or handling the specific calculations needed for massive MIMO antenna systems, and is typically far more efficient at that specific task than a general-purpose chip would be, though less flexible for other purposes. Telecom equipment generally uses a combination of both: specialized chips for performance-critical functions, and increasingly, general-purpose server processors for flexible, software-defined network functions running in virtualized infrastructure.
How do chip shortages or supply chain disruptions actually affect telecom companies?
Chip shortages or supply chain disruptions can directly delay telecom equipment manufacturing and device production, since both network infrastructure equipment and consumer devices depend on a steady, reliable supply of specific semiconductor components. During the broader global chip shortage of the early 2020s, several telecom equipment vendors and device manufacturers publicly reported delays in fulfilling orders, directly tracing back to semiconductor component availability issues. These disruptions also tend to affect smaller, newer market entrants disproportionately compared to large, established vendors with stronger existing relationships and contractual priority with chip manufacturers, since manufacturers facing constrained capacity often prioritize fulfilling orders for their largest, longest-standing customers first.
What role do GPUs specifically play in telecom infrastructure, beyond just AI?
Beyond their well-known role in AI training and inference, GPUs, or graphics processing units, are increasingly used in telecom infrastructure for tasks that benefit from their ability to perform many calculations simultaneously, known as parallel processing, including certain signal processing tasks within virtualized radio access network functions and accelerating specific network functions that would otherwise run more slowly on general-purpose server processors alone. As telecom infrastructure shifts toward AI-native telco cloud platforms specifically designed to run both traditional network functions and AI workloads on shared infrastructure, GPUs have become an increasingly central, rather than purely AI-specific, component of how that infrastructure is actually built.
How does semiconductor miniaturization relate to 5G and future 6G performance?
Semiconductor miniaturization, the ongoing process of fitting more transistors into a smaller physical chip area, has historically been a major driver of improved chip performance and energy efficiency over time, and this trend directly enables more advanced network capabilities. Smaller, more efficient chips allow network equipment to handle more sophisticated signal processing, like the complex calculations required for massive MIMO antenna systems, within the same power and physical size constraints as earlier, less capable chips. As the industry looks toward 6G, which is expected to require even more sophisticated AI-native processing directly within network equipment, continued semiconductor miniaturization is widely viewed as a practical prerequisite for making those future capabilities economically and physically feasible to deploy at scale.




Telco AI Agent Leadership

