For years, enterprise access to dedicated spectrum was concentrated in a handful of countries. Germany, the United Kingdom, Japan and the United States, through CBRS, became reference markets largely because their regulators made it straightforward for factories, ports and campuses to secure their own frequencies. Elsewhere, enterprises depended on mobile operators or unlicensed technologies.
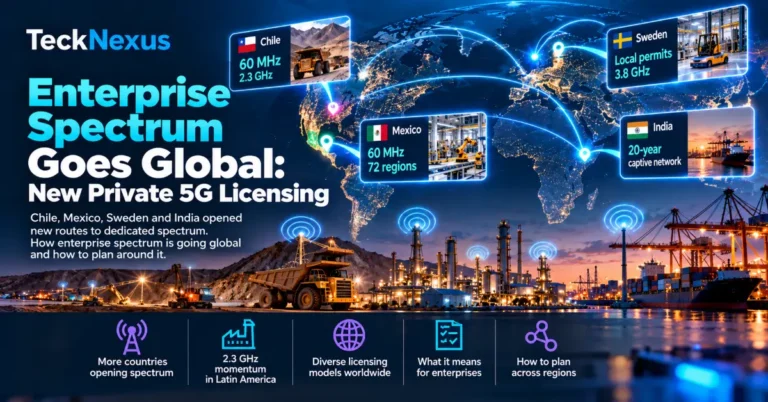
October 2026 showed how quickly that picture is changing. Chile’s regulator allocated 60 MHz in the 2.3 GHz band for private and industrial networks. Mexico increased its planned industrial spectrum auction from 40 MHz to 60 MHz in the upper 2.3 GHz band, with regional licences across 72 areas. Sweden began granting local 5G permits in the 3.8 GHz range. India granted the Mormugao Port Authority a 20-year authorisation for a captive non-public network, and Penang Port went live with Malaysia’s first port private 5G network on dedicated spectrum. Enterprise spectrum is becoming a global feature of the private network market.
Why Enterprise Spectrum Matters for Private Networks
Spectrum determines who controls a private network and how predictably it performs. With dedicated frequencies, an enterprise or its chosen partner can design coverage and capacity around its own operations, configure uplink-heavy frame structures for video and sensors, and avoid contention with public traffic. Without it, enterprises rely on operator spectrum through leasing, slicing or managed services, or on unlicensed options with less predictable performance.
Each route has its place, as our comparison of CBRS, licensed, shared and leased spectrum models sets out. What is changing is that more enterprises, in more countries, now have the option of dedicated spectrum, which strengthens their position whichever route they choose.
Enterprise Spectrum Around the World
Approaches differ by band, licence area and who can hold a licence, but the direction of travel is consistent.
| Market | Band | Model | Status |
| Chile | 2300 to 2360 MHz (60 MHz) | Dedicated allocation for private and industrial networks | Technical rules updated, October 2026 |
| Mexico | Upper 2.3 GHz (60 MHz) | Regional licences across 72 areas by auction | Auction planned; second phase under consideration |
| Sweden | 3800 to 3920 MHz and 3990 to 4130 MHz | Local permits | Applications open, October 2026 |
| India | Captive non-public network authorisation | Direct authorisation or spectrum leasing | Mormugao 20-year authorisation; JNPA leasing procurement |
| Germany | 3.7 to 3.8 GHz | Local campus licences | Established |
| United Kingdom | 3.8 to 4.2 GHz | Shared access licences | Established |
| United States | 3.55 to 3.7 GHz (CBRS); 900 MHz | Shared access; licensed broadband for utilities | Established |
| Brazil | National 5G auction obligation | Private mobile network for government | Navy pilot under way |
Latin America Converges on 2.3 GHz for Enterprise Spectrum
The most striking development in October was the alignment of Chile and Mexico on the 2.3 GHz band. Chile’s Subtel updated its technical rules to set aside 2300 to 2360 MHz for private and industrial networks, supporting private 5G and 5.5G and a path to future 6G in confined industrial settings. Mexico’s Telecommunications Regulatory Commission enlarged its planned industrial auction to 60 MHz in the upper part of the same band, offering regional licences across 72 areas for manufacturing, mining, ports, logistics, energy and agribusiness, and is considering a second phase with broader geographic coverage.
Brazil adds a different model to the region. Its Band Administrator Entity, EAF, is implementing a private mobile network obligation from the national 5G spectrum auction, as covered in our August Private Network Insights, and in October demonstrated a secure national private network for the Brazilian Navy with a one-year pilot.
Convergence on 2.3 GHz matters because the band, known as n40 in 3GPP terms, already has a broad ecosystem of radios and devices. A common enterprise band across major Latin American markets makes it easier for multinational mining, manufacturing and logistics companies to standardise equipment and designs across countries, and gives vendors a larger addressable market for industrial devices. Europe offers a precedent: Valenciaport’s production-scale port network in Spain also targets n40.
Local Licensing Models for Enterprise Spectrum in Europe and Asia
In Europe, the mid-band around 3.8 GHz remains the anchor for local licensing. Sweden’s PTS has begun granting local permits in the 3800 to 3920 MHz and 3990 to 4130 MHz ranges for industrial sites, ports, mines, energy facilities, healthcare, research facilities and campuses. That places Sweden alongside Germany’s 3.7 to 3.8 GHz campus licences and the UK’s shared access licences in the 3.8 to 4.2 GHz range as markets where enterprises can apply directly for site-specific spectrum.
Asia is developing several models side by side. India’s captive non-public network authorisations under the Telecommunications Act, 2023, allow enterprises such as Mormugao Port Authority to plan networks with long-term certainty; the port has engaged a consultant for a detailed project report and is running proof-of-concept trials for cargo tracking, automation and drone surveillance. Other Indian ports are using leasing instead, with Jawaharlal Nehru Port Authority advancing procurement to lease spectrum, a route explored in our analysis of how spectrum leasing is becoming a real procurement path. Malaysia’s Penang Port deployment on dedicated spectrum and China’s national pilot for standalone private 5G across priority industries show further momentum in the region.
Shared and Leased Enterprise Spectrum in the United States
The United States continues to rely mainly on shared and leased models. CBRS remains the foundation for most US private networks, and regulatory certainty around the band is closely watched by manufacturers planning long-term investments. Utilities have a dedicated option in Anterix‘s 900 MHz spectrum, and device support is broadening, with new iPhone models reported to work on private LTE networks using that band, as noted in our September Private Network Insights.
Research is also pointing to more efficient sharing. Idaho National Laboratory has patented an autonomous beam scheduling approach, developed with the University of Utah, that lets multiple private 5G networks coordinate spectrum access without a central controller, aiming to reduce interference and improve capacity where networks sit close together.
Planning Around Regional Enterprise Spectrum Licensing
For organisations operating across several countries, the spread of enterprise spectrum creates opportunity but also complexity. A practical planning approach includes six steps:
- Map every site to its licensing regime: direct local licence, regional auction, captive authorisation, shared access or operator leasing.
- Check band support across devices: confirm that sensors, handhelds, vehicles and modules support each band needed, such as n40, n77, n78 or n48.
- Align licence terms with asset life: long authorisations, such as Mormugao’s 20-year term, suit infrastructure planned to run for decades.
- Plan for timelines: auctions, applications and authorisations take time, so build them into project schedules from the start.
- Standardise designs where bands align: regional convergence, such as 2.3 GHz in Latin America, allows common equipment and templates.
- Keep a fallback route: where dedicated spectrum is unavailable or slow, operator leasing or managed services can bridge the gap.
What Dedicated Enterprise Spectrum Changes for Buyers
Access to dedicated spectrum widens the choice of ownership and operating models. An enterprise holding its own licence can run the network itself, hand it to a systems integrator or engage an operator as a managed service provider without giving up control of the frequencies. That flexibility shapes long-term costs and vendor relationships, as discussed in our analysis of who should own a private 5G network. It also strengthens the business case in sectors where predictable performance and security are non-negotiable, such as ports, mines, utilities and defence.
What to Watch in Enterprise Spectrum
October’s regulatory decisions set out new routes to dedicated spectrum, but their real impact will depend on how quickly enterprises take them up. These developments will show how fast enterprise spectrum turns into working private networks:
- Timing and results of Mexico’s industrial 2.3 GHz auction, and whether a second phase follows.
- Early licensees and deployments under Chile’s new 2.3 GHz allocation.
- Uptake of Sweden’s local 3.8 GHz permits across industry and healthcare.
- Further captive network authorisations at Indian ports and industrial sites.
- Spectrum arrangements under China’s standalone private 5G pilot.
The spread of enterprise spectrum is one of the most important structural shifts in the private network market. As more regulators make dedicated frequencies available, private 5G becomes a realistic option for industries and regions that previously had to rely on operators alone.
For more private network analysis, tools and assessments, explore TeckNexus Intelligence.