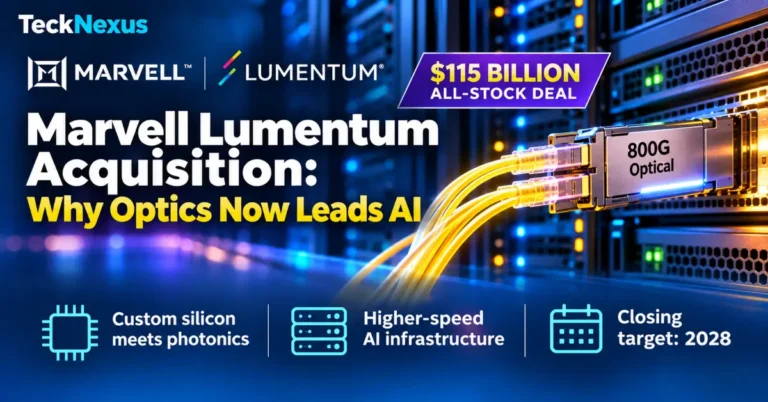
Marvell Technology has agreed to acquire Lumentum Holdings in an all-stock transaction that gives Lumentum an implied enterprise value of $115 billion. Lumentum stockholders will receive 4.5 Marvell shares for each Lumentum share, equivalent to about $1,132 per share and a premium of roughly 23.9% to the unaffected closing price on 28 October 2026. Both boards approved the agreement unanimously, and the companies expect to close in the first half of 2028, subject to stockholder and regulatory approvals.
Read quickly, the announcement looks like one more large deal riding the AI infrastructure boom. Read in context, it says something more specific about where that boom is heading. A custom silicon and networking chip company is paying one of the largest sums in technology history not for more compute, but for lasers, optical transceivers and the specialised fabs that make them. That is a clear statement that moving data, rather than processing it, is becoming the defining engineering challenge of large-scale AI.
The Marvell Lumentum Acquisition at a Glance
| Item | Detail |
| Buyer | Marvell Technology |
| Target | Lumentum Holdings: lasers, optical transceivers, optical circuit switches and compound semiconductor manufacturing |
| Structure | All-stock; fixed exchange ratio of 4.5 Marvell shares per Lumentum share |
| Implied value | About $115 billion enterprise value (roughly $102.5 billion equity value); about $1,132 per Lumentum share |
| Premium | About 23.9% to the unaffected 28 October 2026 close |
| Ownership after closing | About 67% Marvell stockholders, about 33% Lumentum stockholders |
| Leadership | Matt Murphy remains chairman and CEO; three Lumentum directors, including CEO Michael Hurlston, join Marvell’s board |
| Combined scale | About $17.7 billion in annualised pro forma revenue at a 39% non-GAAP operating margin, before synergies |
| Stated targets | $550 billion addressable market; more than $1 billion in annual run-rate cost synergies; accretive to non-GAAP EPS in year one |
| Expected closing | First half of 2028 |
On the same day, Lumentum reported that it had secured a second major near-packaged or co-packaged optics design win, backed by customer purchase commitments of more than $5 billion. The timing gives the deal’s central thesis an immediate commercial anchor: optics is already moving inside the server rack, and customers are committing serious money to get there.
Why the Marvell Lumentum Acquisition Is About Optics Moving Closer to Compute
The strategic case rests on a simple physical constraint. As AI clusters grow from thousands to hundreds of thousands of accelerators, the bandwidth needed between them rises faster than copper can deliver it. Electrical links lose signal quickly at today’s lane speeds, and the circuitry required to recover that signal consumes power that would be better spent on computation. Optical links carry far more data over the same distance with much lower loss.
Optics has already won the long-distance links in AI infrastructure. The question now is how close to the processor it travels. Both companies describe the market in four connectivity domains, each one closer to the chip than the last:
| Connectivity domain | What it connects | Where optics stands |
| Scale-across | Data centres and campuses over kilometres | Optical for years; high-capacity interconnect between distributed AI sites |
| Scale-out | Servers and racks across a cluster | Transition well under way, with 800G and 1.6T pluggable transceivers |
| Scale-up | Accelerators within a rack or pod | Beginning to move to optics through near-packaged and co-packaged designs |
| Scale-in | Dies and chiplets within a single package | The next frontier, where optics sits alongside the silicon itself |
Each step inward raises the bandwidth requirement and tightens the engineering tolerances. That is the heart of the rationale. In the scale-up and scale-in domains, the laser, the modulator, the signal processor and the switch can no longer be designed in isolation by separate suppliers and assembled later. They have to be designed together.
What Each Side Brings to the Marvell Lumentum Combination
The two companies were already closely linked before the announcement, as suppliers to one another across the optical signal chain. Combined, they cover almost every layer of an AI optical link:
| Layer | Marvell | Lumentum |
| Signal processing | Optical and electrical DSPs, SerDes, drivers and amplifiers | Complementary analogue and photodetector components |
| Light source | Relies on external laser supply today | Indium phosphide lasers, including ultra-high-power lasers for co-packaged optics |
| Modules | Silicon photonics and optical engine technology | 800G and 1.6T optical transceivers for cloud and AI data centres |
| Switching | Electrical Ethernet switching | MEMS-based optical circuit switches |
| Compute | Custom XPUs and XPU attach for hyperscalers | Not applicable |
| Manufacturing | Fabless CMOS design and advanced packaging | Compound semiconductor fabs, including what Marvell describes as the world’s largest InP wafer capacity |
The manufacturing column matters most. Lumentum’s indium phosphide fabs are a capability that a fabless design company cannot replicate quickly, and laser supply has been one of the tightest constraints in AI optics over the past year. Owning that capacity gives Marvell a strategic supply position as well as a technology one.
Why Vertical Integration Makes Sense for the Marvell Lumentum Deal
For most of the history of optical networking, the industry has worked through a layered supply chain: component makers sold to module makers, who sold to system builders, who sold to network operators. That model works well when interfaces between layers are stable and standardised. It works less well when every generation demands tighter coupling between electrical and optical design.
The combined company is positioning itself around what both chief executives call extreme co-design. Three benefits stand out:
- Performance and power. Designing the DSP, driver and laser together allows each to be tuned to the real behaviour of the others, improving bandwidth per watt across the link.
- Time to market. Pre-validated optical engines can shorten the qualification cycles that hyperscalers run when they assemble links from several independent suppliers.
- Supply assurance. Combined scale supports the multi-billion-dollar capacity investments needed to meet AI demand, with Lumentum’s fabs and Marvell’s high-volume semiconductor supply chain under one roof.
The deal also gives the combined company a portfolio that spans both electrical and optical switching. As AI data centre architectures evolve, both approaches are expected to coexist, and a supplier able to offer either can follow customer architectures rather than steer them.
The structure of the transaction reflects the same long-term view. Paying entirely in stock means Lumentum’s holders keep a third of the combined business and share in its future growth, rather than taking a cash exit at a single point in the cycle.
What the Marvell Lumentum Acquisition Means for Telecom and Data Centre Interconnect
Most coverage has focused on the inside of the AI data centre, but the deal also matters for the networks between data centres. Scale-across connectivity is the domain closest to traditional telecom, and it is growing quickly as AI training and inference are spread across multiple sites to manage power, land and latency constraints.
Lumentum’s roots lie in optical telecom, and its portfolio still serves carrier networks with components such as optical amplifiers for long-haul links. Marvell supplies DSPs and silicon used in data centre interconnect and carrier optical equipment. A combined company with a stronger position in both the light source and the signal processing could accelerate the performance and efficiency of the high-capacity links that tie AI campuses together, and that operators and neutral-host providers increasingly sell as a service.
For operators building AI-ready transport networks, the broader signal is that optical interconnect is no longer a commodity layer sitting beneath the interesting part of the network. It is becoming a strategic technology in its own right, with investment and innovation flowing towards it from the very top of the semiconductor industry.
The Road to Closing the Marvell Lumentum Acquisition
The companies have set out a long path to completion, and both will continue to operate independently until then:
- Signing, 2 November 2026. The definitive agreement is in place, unanimously approved by both boards.
- Stockholder approvals. Holders of both Marvell and Lumentum will vote on the transaction.
- Regulatory review. Clearances are required in the United States and other jurisdictions, including China, where both companies serve cloud and data centre customers.
- Closing, expected first half of 2028. Lumentum becomes part of Marvell, with Matt Murphy leading the combined company and three Lumentum directors joining the board.
- Integration. The combined company works towards its target of more than $1 billion in annual run-rate cost synergies, primarily in cost of goods sold.
The initial share price reaction for both companies was negative, as investors weighed the all-stock structure and the length of the path to closing against wider questions about the duration of AI infrastructure spending. Over an 18-month approval period, the commercial momentum both businesses report each quarter, including Lumentum’s new design wins, will shape how that view develops.
The Bigger Picture for AI Connectivity After the Marvell Lumentum Deal
The Marvell Lumentum acquisition is the clearest sign yet that the AI infrastructure race has widened from processors to the connections between them. Marvell gains the light source and manufacturing base that its optical ambitions depend on. Lumentum gains the scale, custom silicon relationships and capital to keep pace with demand it has struggled to meet on its own. And the wider industry receives an unmistakable signal that optical interconnect has moved from the edge of the data centre towards its centre.
The details to watch over the coming months are the first jointly designed products, the pace of co-packaged optics adoption in scale-up networks, and how the regulatory review progresses across jurisdictions. Each will indicate how quickly a combined electrical and optical connectivity company can turn its thesis into shipping systems.
For more analysis of AI infrastructure, connectivity and the networks behind them, read TeckNexus Monthly Insights. Have a perspective on optical connectivity or AI infrastructure to share? Partner with TeckNexus to put your insight in front of decision-makers and generate leads.