Private Network
Intelligence
Intelligence Journeys
Utilities Private Broadband Planning
AI Use Case Planning for Utilities

Spectrum

KDDI and Nokia validated quantum-safe optical transport at KDDI’s new Sakai Data Center, a facility built to support real-time AI training, inference, and analytics. The demonstration used Nokia’s 1830 Photonic Service Switch with C+L band capabilities for capacity scaling and the 1830 Security Management Server for centralized key and policy control. The goal is clear: deliver high-throughput, low-latency, and line-rate encrypted data center interconnect (DCI) that is resilient against both today’s threats and tomorrow’s quantum-era risks. Encrypting at the optical layer removes the performance penalties of application or IP-layer encryption and avoids fragmenting security by workload.
India’s AI agenda increasingly spans silicon, data platforms, models, and applications, with an intent to catalyze domestic innovation and contribute to global ecosystems. For telecom leaders, the message is clear: AI is not a bolt-on capability but a system-level transformation that touches RAN, core, transport, cloud, and the enterprise edge. The AI economy runs on connectivity—low-latency access to data, assured bandwidth, location-aware processing, and programmable control. The operators that can fuse connectivity, compute, and data into a cohesive platform will set the pace for India’s next wave of digital growth.
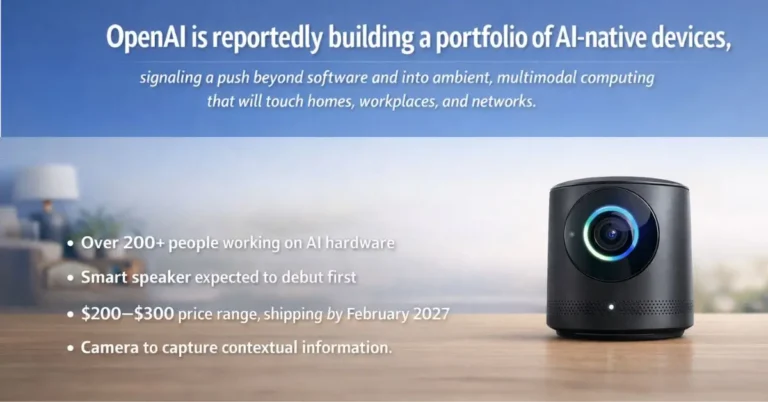
OpenAI is reportedly building a portfolio of AI-native devices, signaling a push beyond software and into ambient, multimodal computing that will touch homes, workplaces, and networks. Multiple reports indicate OpenAI has over 200 people developing a family of AI-enabled hardware, with a smart speaker expected to debut first. Early guidance points to a price in the $200–$300 range and a ship window no earlier than February 2027. The device is said to include a camera to capture contextual information about users and surroundings—an explicit bet on multimodal AI that fuses voice, vision, and environment for richer interactions.
Ericsson and Mistral AI are aligning telecom-grade engineering with customizable foundation models to push AI deeper into network operations and RAN automation. The pairing marries Mistral AI’s fast-evolving model stack with Ericsson’s domain expertise across radio, cloud-native networking, and service management. For European operators, it signals a path to AI capabilities that respect data residency, security, and compliance expectations under the EU AI Act without ceding control to generic, hyperscaler-led platforms. The outcome operators want is simple: measurable gains in performance, efficiency, and resiliency with governance baked in.
Boldyn Networks is rolling out a neutral host 5G upgrade at Silverstone that shifts the circuit from seasonal stopgaps to a year-round, high-capacity mobile platform for fans, teams, and broadcasters. The architecture spans 25 locations, with 57 sectors engineered across 87 DAS zones to handle concentrated traffic and maintain performance under crowd pressure. The design anticipates surges in uplink and signaling, supports concurrent sessions at scale, and smooths throughput across hotspots. A permanent, multi-operator 5G foundation unlocks new revenue, better service metrics, and more efficient event delivery. When connectivity works, dwell time, spend, and satisfaction rise.
Ericsson has introduced an agentic rApp delivered as a cloud service on Amazon Web Services (AWS), aiming to speed operators’ shift from manual automation toward truly autonomous networks. By offering an “Agentic rApp as a Service” on AWS, Ericsson is packaging policy-driven and AI-assisted RAN optimization as a managed, cloud-delivered capability. Agentic capabilities bring reasoning, planning, and action-taking to operations. Running rApps on AWS offers elasticity, global reach, and faster release cadence. The goal: faster onboarding, lower integration friction, and a more repeatable path to closed-loop assurance across multi-vendor 4G/5G networks.
SpaceX’s anticipated 2026 IPO is not just a space-launch story; it is a capital and scale inflection that could reorder parts of the mobile and broadband value chain. Market chatter pegs SpaceX’s IPO valuation around the trillion-plus mark with a potential multibillion-dollar primary raise, a war chest that would dwarf most rivals’ balance sheets. For telecom, the same cash advantage accelerates Starlink’s network deployment, ground infrastructure, and device partnerships—compressing the window for incumbents to respond. Starlink reports more than 9,000 satellites in orbit, 9.2 million paying customers, and over $10 billion in annual revenue.
The plan centers on Visakhapatnam, a port city on India’s east coast, as a tightly coupled zone for data centers, subsea cable landings, power, water, and the digital supply chain. State leadership wants the cluster to be more than rack space. It aims to bring in server assemblers, power and cooling vendors, and specialized logistics to create end-to-end capability. The city is also being pitched as a landing point for new subsea systems toward Singapore, which would diversify India’s international connectivity beyond Chennai and Mumbai and lower latency into Southeast Asia.
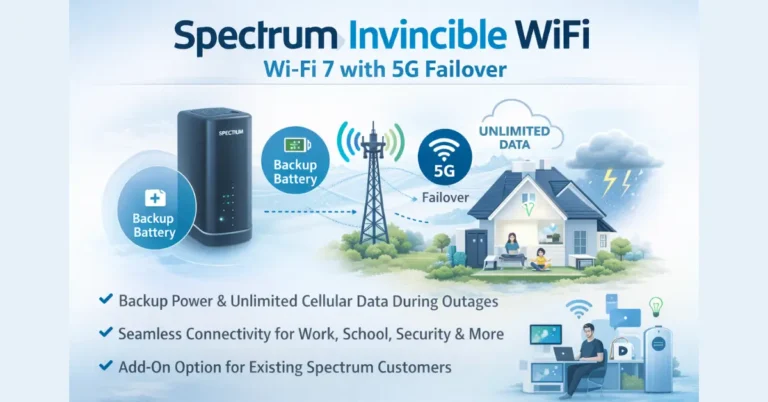
Charter introduced Spectrum Invincible WiFi, a package built around its Advanced Wi‑Fi 7 router paired with an integrated backup battery and an embedded 5G cellular pathway. The system automatically rides through local power interruptions for up to eight hours and, if the wired broadband link drops, switches to cellular with unlimited data until the primary connection returns. The offer targets households running multigig internet and dozens of smart devices, and is positioned as a simple add-on for existing Spectrum customers. Home connectivity has become mission‑critical for work, school, security and telehealth while weather-related disruptions and grid instability are rising.
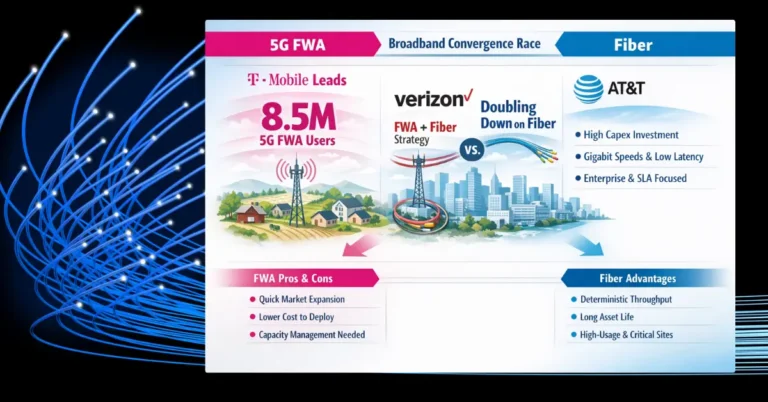
FWA is capex-light and fast to deploy, especially in mid-band-rich markets, which makes it ideal for quick share gains, addressable market expansion, and rural or underserved pockets. Its constraint is shared capacity: as mobile traffic grows, operators must manage prioritization, peak congestion, and plan mix to preserve experience. Fiber demands higher upfront capital but delivers deterministic throughput, low latency, and long asset life that underpins premium ARPU, enterprise SLAs, and wholesale opportunities. Expect operators to steer FWA toward segments with favorable traffic profiles and use fiber for high-usage clusters and enterprise-critical sites.
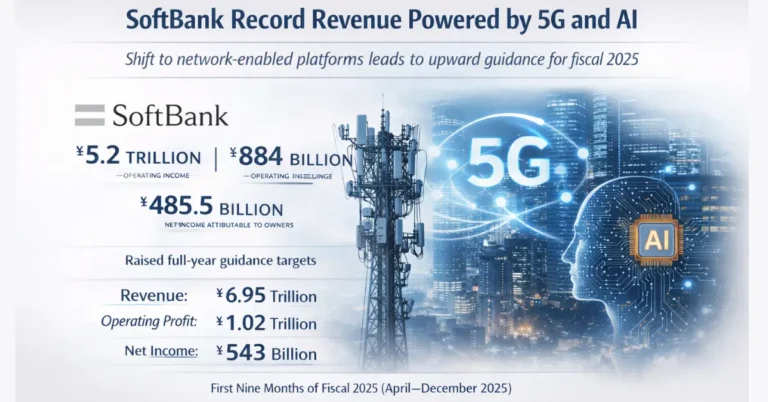
SoftBank Corp. delivered its strongest nine-month performance on record and lifted full-year guidance, underscoring a strategic shift from connectivity-only services to network-enabled platforms in AI, cloud, and edge. Through the first nine months of fiscal 2025 (April–December 2025), SoftBank reported revenue of ¥5.2 trillion, up 8% year over year, and operating income of ¥884 billion, also up 8%, with net income attributable to owners rising 11% to ¥485.5 billion. Management raised full-year targets to ¥6.95 trillion in revenue, ¥1.02 trillion in operating profit, and ¥543 billion in net income, signaling confidence heading into the March 31, 2026 year end.
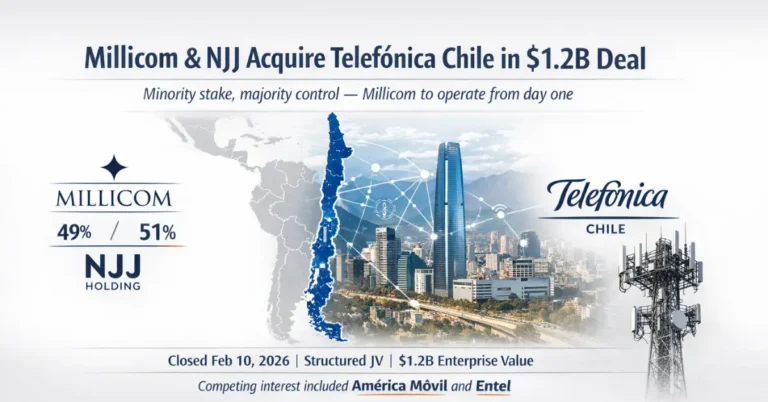
Millicom and NJJ have jointly acquired Telefónica’s Chilean operations in a structure designed to capture upside while insulating Millicom’s balance sheet. Through a jointly controlled vehicle, NJJ holds 51% and Millicom 49% of nearly all of Telefónica’s interest in Chile, with Millicom operating the asset from day one despite its minority stake. The headline value is about $1.2 billion, reflecting a challenged but strategically important footprint in one of Latin America’s most advanced telecom markets. The transaction closed on February 10, 2026, and follows months of speculation that drew interest from other regional heavyweights, including América Móvil and Entel.

Partner Hubs

Telco AI Agent Leadership

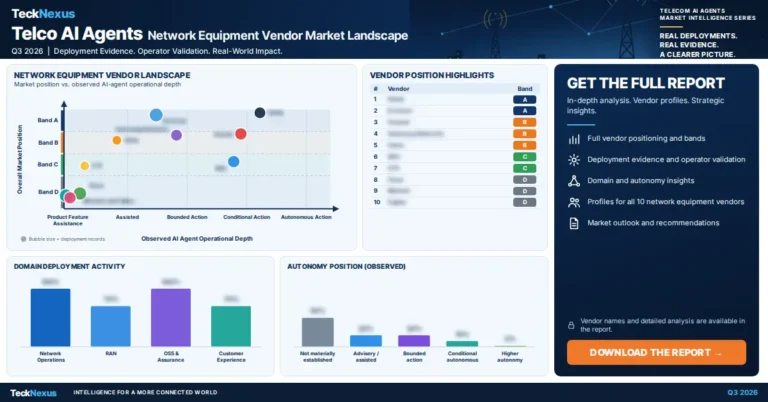
Telco AI Agent Leadership Landscape - Network Equipment Vendors
Network Equipment Vendor Report
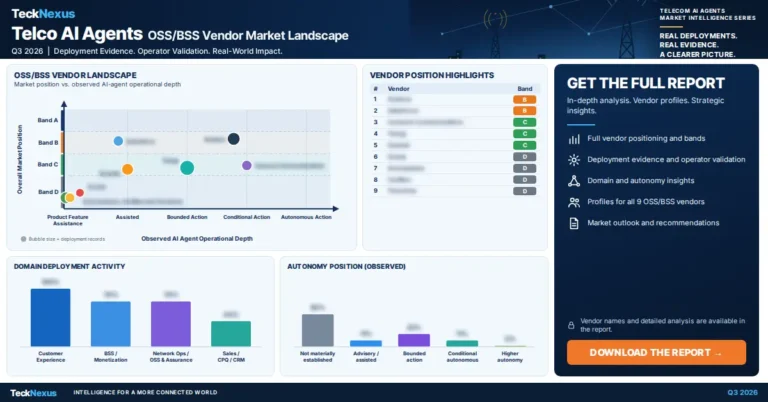
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
OSS/BSS Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
System Integrator Report
Scroll to Top