Private Network
Intelligence
Intelligence Journeys
Utilities Private Broadband Planning
AI Use Case Planning for Utilities

Spectrum

A surprise endorsement from President Trump has thrust Nexstar’s proposed takeover of Tegna back into the spotlight, with implications that cut across broadcast consolidation, streaming competition, and FCC ownership policy. After criticizing large media combinations late last year, the President is now urging regulators to approve Nexstar’s bid for Tegna, framing it as a way to bolster competition against national TV networks and Big Tech platforms. Regulatory outcomes hinge on how the FCC treats national reach limits, market overlaps, and public‑interest conditions. The combined footprint would touch a supermajority of U.S. TV households—well beyond today’s national audience reach cap absent discounts or divestitures.
New guidance from the NTIA signals that BEAD-funded satellite providers, including SpaceX’s Starlink, must abide by standard program terms rather than negotiate bespoke carve-outs. An updated NTIA FAQ on subgranting makes clear that states cannot waive or dilute the statutory and programmatic requirements set out in the BEAD NOFO and subsequent guidance. Payments should be tied to objective milestones and verifiable outcomes, not front-loaded without proportional performance. Performance testing, reporting, and documentation must meet program and FCC-aligned standards; subgrantees cannot unilaterally narrow test samples or exclude locations to their advantage. The FAQ effectively answers whether BEAD can be implemented on a “vendor’s terms”: it cannot.
Colombia has cleared a milestone consolidation: Tigo has taken operational control of Movistar, creating a second national-scale incumbent to challenge Claro. The Superintendence of Industry and Commerce (SIC) approved the integration through Resolution 94169 of 2025, capping months of scrutiny and pushback from rivals and ISPs. The merger compresses Colombia’s competitive field at a time when 5G rollouts, fiber densification, and cloud-native cores demand scale. It creates a stronger counterweight to Claro, but also raises real concerns about a two-horse race and the downstream effects on MVNOs, ISPs, and enterprise buyers.
AT&T is deepening ties with Amazon by pairing its national fiber assets with AWS cloud and AI tooling while adding low Earth orbit connectivity from Amazon’s satellite network to fill coverage gaps for business customers. The collaboration has two pillars: cloud modernization on AWS and satellite-enabled reach via Amazon’s LEO network, with AT&T also supplying fiber capacity into AWS data centers to bolster high-performance infrastructure. Amazon’s LEO constellation will deliver fixed broadband connectivity for AT&T Business customers in areas where terrestrial options are limited, enabling primary service in hard-to-reach sites and resilient backup for SD‑WAN architectures.
Boingo Wireless is integrating Globalstar’s XCOM RAN to accelerate private 5G across airports, stadiums, hospitals, convention centers, transit hubs, and military bases. Globalstar said Boingo will add XCOM RAN, a software-defined private 5G platform built around the Supercell architecture, to its private network portfolio. A highlighted approach is overlaying XCOM RAN on existing distributed antenna system (DAS) infrastructure to preserve DAS coverage advantages while boosting capacity and performance. Enterprises are moving beyond pilot projects to operational private 5G in high-traffic, RF-challenged environments. This aligns with rising demand for low-latency, secure connectivity for IoT, video, automation, and mission-critical operations.
The merger creates a $1.25 trillion private giant that fuses launch, satellites, and AI, but the strategic logic goes beyond orbiting data centers. SpaceX brings rockets, Starship scale, and the world’s largest NGSO broadband network via Starlink. xAI brings models, AI R&D, and a brand in the hottest capital market category. Together, they present a single story to investors: own the stack from compute to constellation to connectivity, on and off Earth. Consolidation gives Musk freedom to reallocate cash flows and simplifies the roadshow pitch.
Digipower X positions itself as a vertically integrated AI infrastructure operator combining Tier III-certified modular data centers with owned and controlled energy assets to compress deployment cycles. The company cites more than 200 MW currently online across a combined-cycle plant and three additional operational sites, development pathways for up to 1.5 GW over the next three years, and a letter of intent tied to a 1.3 GW power plant in West Virginia that is being evaluated as a long-term AI campus anchor, with additional scale targeted in North Carolina. Its AI-Ready Modular Solution (ARMS) aims to deliver Tier III modular capacity in roughly 180 days, emphasizing redundancy, energy optimization, and liquid-cooling readiness for high-density AI clusters.
Airspan plans to supply a 5G Air-to-Ground (ATG) system for Space Compass’s High-Altitude Platform Station (HAPS) program, using an aircraft operating around 16–18 km to act as a stratospheric node for maritime monitoring. The end-to-end solution—airborne radios and antennas, onboard 5G processing, and a complete ground-based 5G RAN, core, and management stack—targets secure command-and-control plus real-time sensor data exchange between the HAPS and ground stations up to roughly 300 km away. After lab and pre-flight work, the team intends to validate the system on a light aircraft in 2026, followed by stratospheric trials in 2027.
The operators that control both dense fiber and performant 5G, and that package them coherently, will set the pace for the next telecom cycle. AT&T’s targets—more fiber passings, higher bundle attach, and measured wireless growth—put it squarely in the camp that sees integrated networks as the winning model. If the company executes on build cadence and cross-sell while keeping experience clean, expect continued share gains in fiber markets and a tougher environment for single-asset competitors. For buyers, the practical takeaway is to lean into converged sourcing now to lock in economics and resiliency as these footprints expand.
With the Union Budget around the corner, the Cellular Operators Association of India (COAI) is asking for a structural fix to spectrum pricing, statutory levies, and GST that is designed to restore sector health and accelerate digital infrastructure build-out. COAI’s agenda centers on spectrum affordability, regulatory levy rationalization, and GST reform to unlock liquidity frozen as input tax credit. COAI argues for spending the sizable unused corpus first, holding the DBN levy in abeyance, and trimming license fees to roughly 0.5–1% to cover administrative costs. Cutting GST on regulatory payments from 18% to 5% would reduce the pace of new ITC build-up and meaningfully ease liquidity pressure.
The next wave of digital transformation will be defined by AI workloads riding on cloud and edge infrastructure over 5G networks, and that shift will change how networks are built, monetized, and secured. Generative and agentic AI move more compute into the network, creating persistent, uplink-heavy, low-latency flows rather than the mostly downlink, best-effort traffic of the smartphone era. Video from cameras, glasses, and sensors feeds models at the edge and in the cloud; results return in milliseconds to people and machines. That means tighter latency budgets, deterministic jitter control, and stronger guarantees for both throughput and reliability.
Verizon exits 2025 with standout subscriber growth and a leaner 2026 investment plan that shifts dollars from network build to integration, efficiency and customer retention. Verizon posted more than 1 million net additions in the fourth quarter, including 616,000 postpaid phone net adds—the best showing since 2019—and 372,000 broadband net adds driven by 319,000 fixed wireless access (FWA) additions and the strongest Fios Internet quarter since 2020. After years of 5G coverage build, Verizon is pivoting to densification, fiber integration and operating efficiency, allowing capex to step down without undermining network competitiveness. Capital will concentrate on fiber-led convergence, FWA capacity, and experience-centric technologies that reduce churn and support revenue quality.

Partner Hubs

Telco AI Agent Leadership

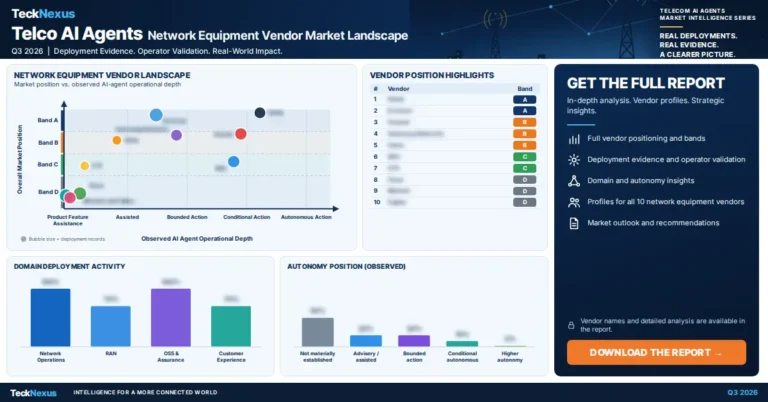
Telco AI Agent Leadership Landscape - Network Equipment Vendors
Network Equipment Vendor Report
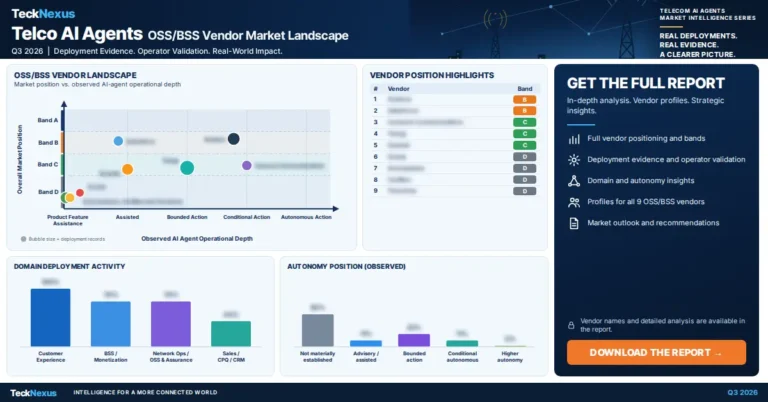
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
OSS/BSS Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
System Integrator Report
Scroll to Top