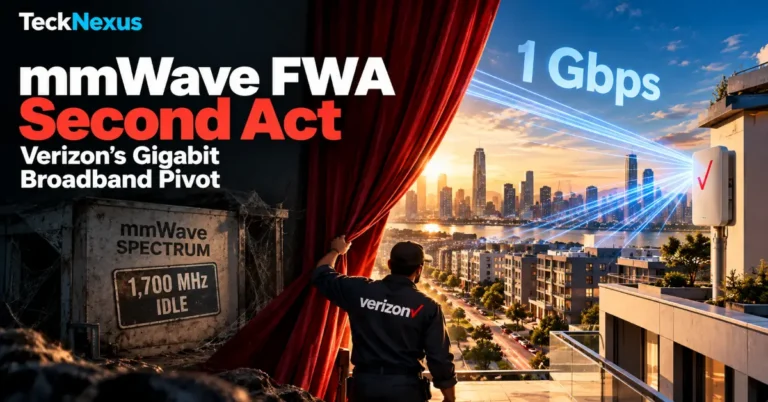
For much of the past five years, millimetre wave has been the part of the US 5G story the industry has preferred not to dwell on. High-band licences were acquired at scale, deployed in stadiums and dense downtown blocks, and then left largely underused while mid-band C-band spectrum carried the weight of both mobile growth and fixed wireless access. Verizon’s third quarter results have changed that narrative. The operator now plans to use roughly 1,700 MHz of mmWave holdings to deliver a 1 Gbps fixed wireless service across metro areas, with a medium-term goal of adding 10 to 15 million gigabit-capable premises on top of its existing target of 40 to 50 million fibre passings.
On the surface, this reads as a comeback. Look more closely and it is something more interesting: a move away from treating FWA as a single product sold wherever spare capacity exists, towards treating broadband as a portfolio of access layers, each matched to a customer segment and a clear performance promise. That shift matters well beyond one operator’s subscriber line.
Why mmWave FWA is a different proposition from mobile mmWave
The difficulties mobile mmWave ran into were never a mystery. Signals at these frequencies travel short distances and are easily blocked by walls, glass, foliage and even the user’s own hand. A smartphone is constantly moving, frequently indoors and rarely pointed anywhere useful. Coverage became a patchwork of hotspots, and the user experience was hard to make consistent.
Fixed access removes most of those variables. The customer premises equipment stays in one place, can be positioned at a window or mounted outdoors, and only needs to be aligned once. Beam management becomes predictable rather than reactive, and higher-gain antennas at both ends of the link improve the link budget considerably. The physics are unchanged, but the engineering problem is a different one: it moves from managing mobility to planning sites, installations and line of sight.
Radio hardware has also moved on substantially since the first wave of high-band deployments. Phased-array integration, beamforming silicon and CPE design have all matured, which changes the cost and performance envelope of a fixed mmWave link. Verizon has not yet published the technical specifics of its new solution, so the detail of the architecture will become clearer as deployments scale, but the direction of travel is well grounded.
Segmentation is the real story behind mmWave FWA
The subscriber numbers explain the timing. Verizon added 314,000 broadband customers in the third quarter, split between 155,000 fibre connections and 159,000 FWA connections, with FWA net additions around 40% lower than a year earlier. That decline was deliberate. The operator has stopped selling fixed wireless into locations where it cannot deliver the speed a given customer segment expects, rather than filling whatever capacity happens to be available.
Demand data shows why that discipline points directly at mmWave. More than 55% of new Verizon fibre customers are choosing plans of 1 Gbps or faster. A C-band FWA product delivering a few hundred megabits serves the value segment well, but it was never going to compete for those gigabit households. mmWave gives fixed wireless a credible route into the premium tier, and it reframes the metric that matters. Raw FWA net additions become less important than the total number of premises an operator can serve at gigabit speed, regardless of the access technology behind it.
It also explains why Verizon now expects to go well beyond its earlier ambition of 8 to 9 million FWA customers by 2028. With a high-speed tier in the portfolio, the addressable market for fixed wireless is no longer capped by what mid-band spectrum can spare.
How mmWave FWA reshapes spectrum economics
The second effect is less visible but arguably more valuable. Every fixed wireless household served on mmWave is a household no longer drawing on C-band capacity. That capacity flows back to mobile, at the same moment Verizon is reporting its strongest postpaid phone growth in five years, with 406,000 net additions in the quarter. A spectrum asset that was carried on the balance sheet with limited return becomes revenue-generating, and in doing so protects the performance of the mid-band layer that underpins the mobile business.
Seen as a system, the model looks like this:
| Access layer | Role in a layered model | Key strength | Key constraint |
| Fibre (FTTP) | Gigabit and multi-gig homes, enterprise, AI backbone | Highest capacity and longest asset life | Civil works cost and build time |
| mmWave FWA | Gigabit service in dense metro premises and MDUs | Very wide channels without last-mile trenching | Line of sight, range and installation planning |
| C-band FWA | Broad-coverage home broadband at mid-tier speeds | Wide footprint and simple self-install | Capacity shared with mobile users |
| Low-band | Mobile coverage and resilience | Range and in-building penetration | Limited capacity for fixed services |
For the wider market, the implication is that high-band licences deserve a second look. Operators in the US and elsewhere hold mmWave spectrum that has often been treated as a sunk cost. A proven fixed gigabit use case at metro scale would change how those holdings are valued, deployed and, in some markets, how future high-band assignments are designed.
MDUs and fibre density: where mmWave FWA fits best
The metro focus is no accident. Multi-dwelling units are among the most expensive and slowest premises to connect with fibre. Landlord agreements, riser access and the condition of older buildings can delay in-building wiring for months or years. A rooftop or façade-mounted mmWave link feeding in-building distribution sidesteps much of that friction. This is the model Starry built its business around, and Verizon’s acquisition of Starry earlier this year, alongside the expansion of its MDU programme, signals how central that segment is to the plan.
There is a useful paradox here. mmWave FWA does not compete with fibre so much as depend on it. High-band nodes need dense, fibre-fed backhaul, which means mmWave naturally rides the fibre footprint and extends its reach into premises where the final connection is costly. Verizon’s multi-year agreement with Corning for more than 80 million miles of fibre through 2032 underlines that fibre remains the foundation. The 10 to 15 million mmWave premises are best understood as fibre-adjacent gigabit capacity rather than an alternative to it.
Gigabit without trenching: a pattern beyond mmWave FWA
The same week brought a parallel move in Europe. Virgin Media O2 began offering 2 Gbps services over its existing DOCSIS hybrid fibre-coaxial network to an additional 3 million homes across England, with no new digging required. The technologies differ, but the logic is the same: operators are extracting the next performance tier from assets already in the ground or already under licence, before committing to new civil works.
That reflects a broader capital discipline across the sector. Incremental upgrades to existing assets reach the market faster and cost less per premises than greenfield builds, and they free capital for opportunities with stronger returns. Verizon’s fibre is a case in point: a $2 billion dark fibre agreement with AWS, following a $1 billion deal with Google, takes its signed AI infrastructure and edge contracts to roughly $4 billion. The same fibre asset is being monetised at the backbone layer for hyperscalers and at the access layer for homes, with mmWave extending its reach in between.
What to watch as mmWave FWA scales through 2027
Verizon plans to begin scaling the service this quarter and continue through 2027 and beyond. Several indicators will shape how the model develops, for Verizon and for any operator considering a similar path:
- Installation model. Whether installations lean towards window-mounted self-install or professional outdoor fitting will largely determine cost per connection and speed of rollout.
- Performance at scale. Sustaining gigabit speeds through busy hours and varied weather conditions across large customer bases is the benchmark that will define the tier.
- Node density and backhaul. The pace of high-band node deployment in each metro will track closely with local fibre backhaul availability.
- Pricing and positioning. How mmWave gigabit plans are priced relative to fibre and cable gigabit tiers will show whether the service is positioned as a substitute or a complement.
- Ecosystem momentum. Radio and CPE suppliers scaling production for fixed high-band links, and other high-band licence holders evaluating similar services, would indicate the model is spreading.
- Reporting metrics. Operators may begin reporting gigabit-capable premises across all technologies as a headline figure, which would make technology-agnostic comparison far easier.
The TeckNexus view on mmWave FWA
The second act of mmWave is neither a vindication of the original 2018 thesis nor a retreat from fibre. It is a sign of maturity: spectrum being assigned to the job it is physically best suited for, inside a portfolio designed around customer segments rather than network availability. Broadband strategy is becoming an engineering portfolio rather than a single technology bet, and operators that can orchestrate fibre, mid-band and high-band as one system will be best placed to grow gigabit coverage without growing capital intensity at the same rate.
For more analysis on digital infrastructure, 5G and advanced connectivity, subscribe to TeckNexus Monthly Insights. If you would like to share your perspective with our audience and generate qualified leads, partner with TeckNexus through our Intelligence Programs.