Private Network
Intelligence
Intelligence Journeys
Utilities Private Broadband Planning
AI Use Case Planning for Utilities

Fiber

Verizon posted 55,000 postpaid phone net additions, a modest beat that underscores stabilizing consumer trends and stronger execution in premium plans and broadband cross-sell. The net add beat is small in absolute terms, but strategically important: it points to improving churn and a healthier mix of high-value subscribers after several quarters of intense promotional pressure. Management coupled the result with a constructive outlook characterized by service revenue resilience and disciplined capital intensity, hinting at a tighter or modestly raised full‑year guide. For a market still digesting 5G investment cycles, this steady footing matters more than splashy net‑add gains.
T-Mobile has inked two 50/50 fiber joint ventures to accelerate FTTP reach, add multi-gig capacity, and broaden its multi-access broadband portfolio. T-Mobile will partner with Oak Hill Capital to combine GoNetspeed and Greenlight Networks into a single platform and, in a separate JV, team with infrastructure investor Wren House to acquire i3 Broadband. Collectively, the platforms target about 1.8 million passings by the end of 2026—roughly 1.3 million from GoNetspeed/Greenlight and 500,000 from i3 Broadband—expanding T-Mobile’s ability to sell T-Fiber by T-Mobile alongside its leading 5G fixed wireless access (FWA) offering.
Deutsche Telekom is weighing a structural overhaul that would collapse its 53% ownership of T-Mobile US into a single, unified company spanning both sides of the Atlantic. Reports indicate Deutsche Telekom is exploring an all-stock transaction in which a new holding company would acquire both Deutsche Telekom and T-Mobile US, with current shareholders of each ending up as owners of the combined entity. The new group could pursue dual listings in the U.S. and Europe, eliminating today’s parent–subsidiary setup and aligning governance, strategy, and capital allocation under one roof.
Verizon’s role as Official Telecommunication Services Sponsor for FIFA World Cup 2026 and Official Tournament Supporter for FIFA Women’s World Cup 2027 elevates mega-event connectivity into a proving ground for 5G, fiber, FWA and broadcast at unprecedented scale. The World Cup concentrates extreme traffic densities, with each match expected to generate more than 50 terabytes of in-stadium data—an order of magnitude that forces operators to optimize spectrum, radio density and backhaul in tandem. Verizon’s capacity uplift—adding 5G spectrum to deliver an estimated 3x to 5x boost across all host stadiums—will benchmark real-world 5G ROI where venue, fan, and operational requirements converge.
The European Commission has approved Orange’s plan to acquire the remaining stake in MasOrange, signaling limited competitive impact and clearing the path for full control in Spain. Orange will purchase the roughly 50% it does not already own in MasOrange from the Lorca consortium for about €4.3 billion. MasOrange was created in 2024 by combining Orange Spain and MásMóvil, and the new deal converts the joint venture into a wholly owned Orange subsidiary. The Commission used its simplified merger review, indicating no structural change in market concentration. Closing is expected before July 2026, after which MasOrange will be integrated into Orange’s operations and financial reporting.
European regulators have cleared the path for Telecom Italia (TIM) to offload its global wholesale arm, Sparkle, advancing a restructuring with implications for sovereignty, subsea capacity, and wholesale competition. The European Commission has approved the acquisition of Sparkle by Italy’s Ministry of Economy and Finance (MEF) and infrastructure provider Retelit, valuing the asset at €700 million and granting joint control to the two buyers. TIM had initially targeted closing in late 2025, but now guides to completion in the first half of 2026. Brussels found the deal would not materially distort competition in the relevant wholesale markets.
US Mobile and Starlink have launched limited-time bundles that combine Starlink residential service with US Mobile’s unlimited mobile plans under a single account and bill. Entry pricing starts at $47 per month, which effectively blends a $30 Starlink residential tier (targeted around 100 Mbps) with a $17 US Mobile base unlimited plan. Higher Starlink speed tiers are available at $77 per month for a 200 Mbps option and $117 per month for a “Max” service that targets 400 Mbps or more. Compared with Starlink’s typical standalone rates of $50, $80, and $120 for the same speed tiers, the bundles represent meaningful savings for households that want both mobile and home internet.
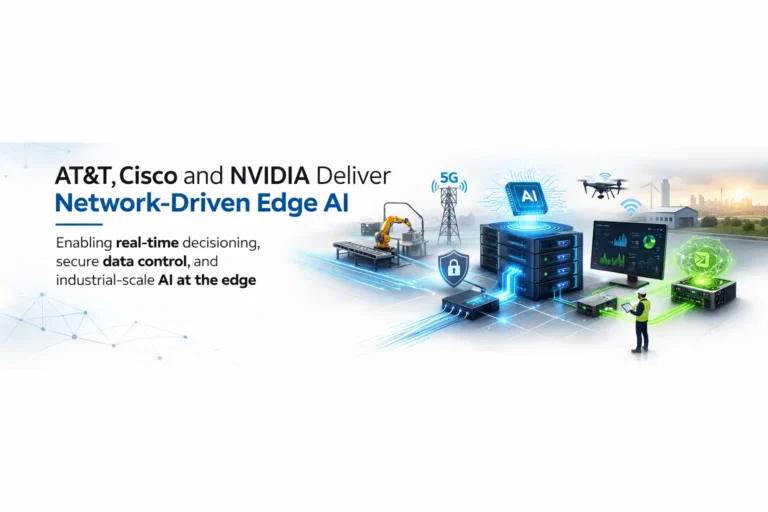
AT&T’s new collaboration with Cisco and NVIDIA signals a decisive shift from cloud-centric AI to network-driven edge intelligence for enterprise operations. Enterprises want real-time decisioning without shipping sensitive data to distant clouds, and operators need a scalable way to deliver it. By combining AT&T’s dedicated IoT core with Cisco’s mobility services platform and NVIDIA-powered AI infrastructure, the trio is packaging deterministic connectivity, near-device inference, and policy enforcement into a single, operator-grade platform. The promise: lower latency, tighter data control, and a path to production for AI at industrial scale.
AT&T’s five-year, $250 billion U.S. network commitment sets the tone for the next phase of fiber, 5G, and satellite convergence as traffic, AI workloads, and resilience requirements climb sharply. The 2026–2030 window aligns with the industry’s transition into 5G-Advanced (3GPP Release 18/19), the scaling of edge AI, and increased cloud traffic between homes, enterprises, and hyperscalers. Data growth is no longer linear, and the cost of downtime is rising. Large, front-loaded builds in fiber and 5G Radio Access Network (RAN), paired with new satellite overlays, are how national carriers will chase coverage, performance, and reliability targets simultaneously.


Partner Hubs

Telco AI Agent Leadership

Telco AI Agent Leadership Landscape - Network Equipment Vendors
Network Equipment Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
OSS/BSS Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
System Integrator Report
Scroll to Top