Private Network
Intelligence
Intelligence Journeys
Utilities Private Broadband Planning
AI Use Case Planning for Utilities

Microsoft

India is moving to anchor a larger slice of global AI compute by pairing policy incentives with large-scale private capital and renewable power. New Delhi has outlined plans to attract more than $200 billion for AI infrastructure over the next two years, positioning the country as a production base for compute, data, and advanced applications rather than a pure consumer market. The policy stack aims to reduce friction for export-oriented AI services while widening access to shared compute for startups and enterprises. Adani Group plans to invest $100 billion through 2035 to build renewable-powered, AI-optimized data centers across India.
Cognizant is expanding its partnership with Google Cloud around Gemini Enterprise and Google Workspace, and it is putting real skin in the game by rolling out this stack internally to boost productivity and delivery velocity. The company is forming a dedicated Gemini Enterprise Center of Excellence and codifying repeatable delivery with an Agent Development Lifecycle that embeds AI across design, build, validation, and production. It is also packaging accelerators—Cognizant Ignition for discovery and data readiness and Cognizant Agent Foundry for no-code, pre-configured agents targeting use cases like AI-powered contact centers and intelligent order management.
A new cross-industry consortium is forming to codify how trusted technology should be built, operated, and governed across borders. On February 13, 2026, fifteen companies spanning cloud, networks, semiconductors, software, and AI launched the Trusted Tech Alliance during the Munich Security Conference. The goal: define verifiable, provider-agnostic practices for a trustworthy technology stack—from connectivity and cloud infrastructure to chips, software, and AI—so customers and governments can rely on secure, resilient services regardless of where solutions are developed or deployed. Trust, sovereignty, and resilience are now gating factors for growth as AI scales and geopolitical risk reshapes supply chains.
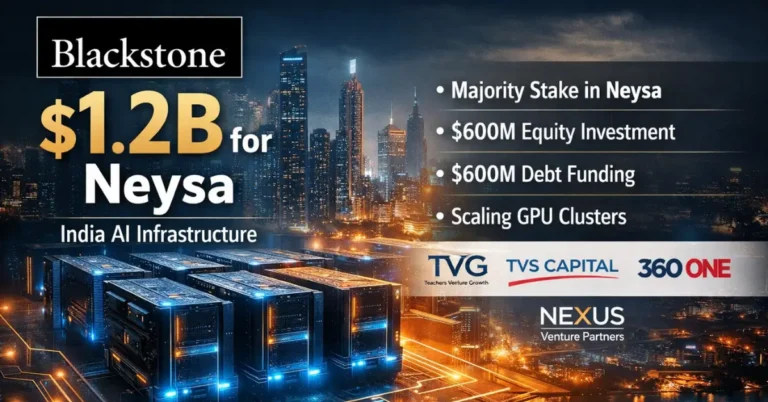
Blackstone will take a majority stake in Neysa through up to $600 million in primary equity, alongside Teachers’ Venture Growth, TVS Capital, 360 ONE Asset, and Nexus Venture Partners; the company also plans up to $600 million in debt to accelerate buildout. The raise is a step change from Neysa’s earlier $50 million and positions the Mumbai-headquartered startup to scale domestic GPU clusters for enterprises, public sector agencies, and AI developers.
The plan centers on Visakhapatnam, a port city on India’s east coast, as a tightly coupled zone for data centers, subsea cable landings, power, water, and the digital supply chain. State leadership wants the cluster to be more than rack space. It aims to bring in server assemblers, power and cooling vendors, and specialized logistics to create end-to-end capability. The city is also being pitched as a landing point for new subsea systems toward Singapore, which would diversify India’s international connectivity beyond Chennai and Mumbai and lower latency into Southeast Asia.
Anthropic’s latest financing round resets the competitive map for enterprise AI and raises the stakes for telecom, cloud, and large-scale IT buyers planning agentic automation. Anthropic closed a $30 billion Series G at a $380 billion post-money valuation, led by GIC and Coatue with participation from D. E. Shaw Ventures, Dragoneer, Founders Fund, ICONIQ, and MGX, alongside a broad cohort that includes Accel, General Catalyst, Jane Street, and the Qatar Investment Authority. The raise follows sustained commercial momentum and arrives as competitive intensity with OpenAI deepens, signaling that AI platform consolidation and scale economics will define the next phase of the market.
Microsoft’s AI QuickStart, backed by IMDA and UOB, aims to turn generative AI intent into production outcomes in weeks, not years. AI QuickStart targets “Digital Leaders” in Singapore—SMEs and larger non-ICT enterprises that have already built basic digital capabilities and can fund transformation—by offering a fast, structured path to deploy enterprise AI. Each engagement is designed to finish within three months with a cost cap of up to S$20,000 per project, covering cloud, compute, and professional services, which directly addresses executive concerns over unpredictable pilot spend and elongated proofs-of-concept.
An AI‑fueled land grab for advanced memory is squeezing supply for handsets, undercutting Qualcomm’s near‑term outlook even as end‑demand for premium Android devices improves. Memory suppliers are prioritizing high‑bandwidth memory (HBM) and DDR5 for AI accelerators and data center servers, diverting wafer capacity and capex away from mobile‑grade LPDDR5/5X and UFS storage. The result is a classic allocation cycle: supply chases the highest‑margin demand (HBM and enterprise SSDs), while downstream categories like smartphones and some edge devices face tighter availability and rising component costs. For Qualcomm, whose Snapdragon platforms anchor premium Android devices, the constraint limits upside volume and mix in the near term.
Amazon and Google currently lead the AI capex race, with Microsoft and Meta not far behind, and the prize is control over scarce compute, power, and network resources that define the next decade of cloud and AI services. For telecom and infrastructure players, the opportunity is immediate: deliver power-adjacent, fiber-rich, AI-ready capacity with speed and predictable SLAs. For enterprises, the mandate is pragmatic: secure capacity, design for portability across heterogeneous silicon, and enforce cost governance as inference scales. The winners will be those who pair aggressive buildouts with disciplined execution—turning record capex into durable platforms and customer outcomes.
Amdocs is launching aOS, an agentic operating system for telecom, to move CSPs from AI pilots to production-scale, cross-domain automation. Amdocs’ aOS targets that gap with a multi-agent architecture that automates complex workflows while keeping humans in the loop for policy and final decisions. At the foundation is a “Cognitive Core” that manages telco-specific knowledge, agent libraries, and guardrails. aOS pricing will lean on outcome-based SLAs, tying spend to measurable business impact such as resolution rates, handle-time reductions, activation velocity, or assurance KPIs. aOS is Amdocs’ bid to make agentic AI the connective tissue of telco operations.
AT&T is deepening ties with Amazon by pairing its national fiber assets with AWS cloud and AI tooling while adding low Earth orbit connectivity from Amazon’s satellite network to fill coverage gaps for business customers. The collaboration has two pillars: cloud modernization on AWS and satellite-enabled reach via Amazon’s LEO network, with AT&T also supplying fiber capacity into AWS data centers to bolster high-performance infrastructure. Amazon’s LEO constellation will deliver fixed broadband connectivity for AT&T Business customers in areas where terrestrial options are limited, enabling primary service in hard-to-reach sites and resilient backup for SD‑WAN architectures.
The merger creates a $1.25 trillion private giant that fuses launch, satellites, and AI, but the strategic logic goes beyond orbiting data centers. SpaceX brings rockets, Starship scale, and the world’s largest NGSO broadband network via Starlink. xAI brings models, AI R&D, and a brand in the hottest capital market category. Together, they present a single story to investors: own the stack from compute to constellation to connectivity, on and off Earth. Consolidation gives Musk freedom to reallocate cash flows and simplifies the roadshow pitch.

Partner Hubs

Telco AI Agent Leadership

Telco AI Agent Leadership Landscape - Network Equipment Vendors
Network Equipment Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
OSS/BSS Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
System Integrator Report
Scroll to Top