Partner Hubs

The next evolution of Ciena’s DCOM: OOB management for diverse data center needs
2027 Intelligence Programs

Ericsson

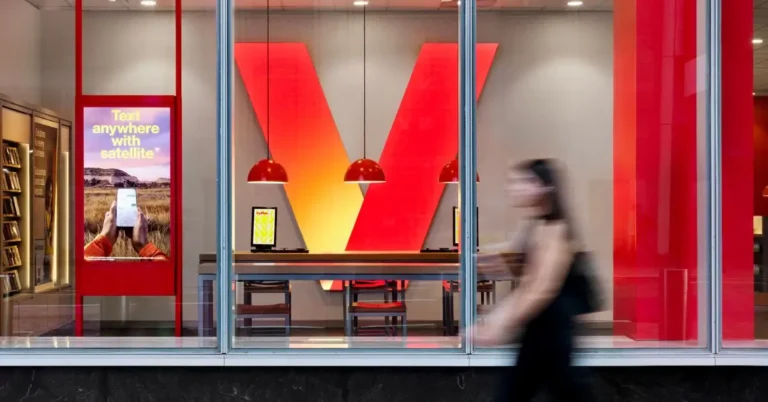
Verizon exits 2025 with standout subscriber growth and a leaner 2026 investment plan that shifts dollars from network build to integration, efficiency and customer retention. Verizon posted more than 1 million net additions in the fourth quarter, including 616,000 postpaid phone net adds—the best showing since 2019—and 372,000 broadband net adds driven by 319,000 fixed wireless access (FWA) additions and the strongest Fios Internet quarter since 2020. After years of 5G coverage build, Verizon is pivoting to densification, fiber integration and operating efficiency, allowing capex to step down without undermining network competitiveness. Capital will concentrate on fiber-led convergence, FWA capacity, and experience-centric technologies that reduce churn and support revenue quality.
France’s three other mobile network operators—Bouygues Telecom, Free-iliad and Orange—have reopened negotiations with Altice to carve up most of SFR, reviving a complex deal that could reshape competition, capex and customer experience across the market. The operators confirmed they are conducting due diligence with Altice after re-engaging in early January 2026, stressing that legal and financial terms remain undecided and that there is no assurance of a transaction. A successful transaction would compress the French market from four to three MNOs, with material consequences for pricing power, 5G/fiber investment, vendor ecosystems and enterprise buyers. Consolidation momentum is building across Europe, evidenced by recent approvals of large transactions with stringent remedies. Altice has been under sustained pressure to reduce debt following restructurings and asset sales.
CEO Börje Ekholm indicated the company will keep trimming headcount after cutting roughly 5,000 positions over the last year. In Sweden, Ericsson has notified authorities and begun union talks that could affect about 1,600 roles, part of a multi‑year restructuring program. The move follows a 2023 plan to remove around 8,500 jobs worldwide—about 8% of its workforce—with further reductions last year in markets such as Spain and Canada. The rationale remains consistent: reset the cost base, protect profitability, and keep investment firepower for strategic bets amid a slower operator capex cycle.
Ericsson is signaling a strategic shift toward defence, mission-critical, and AI-era network architectures as traditional RAN spending stays flat. Management expects the global RAN market to remain flat in 2026, sustaining a multi-year trend that now pegs annual spend at roughly the low-$30 billions. Ericsson is building for a traffic mix shift where AI applications push uplink throughput and latency to the forefront. Defence, utilities, transport, and public safety are moving from proprietary systems to standards-based 3GPP networks.
Enterprises are moving fast to private 5G to digitize operations, but the payoff only materializes if security scales with the new connectivity footprint. Private 5G brings deterministic wireless to factories, hospitals, ports, and energy sites, connecting robots, AGVs, cameras, and critical control systems. Security must follow identities and workloads, not subnets. Adopt a Zero‑Trust approach aligned to NIST SP 800‑207 with a single source of truth for identity and policy. Shift from perimeter controls to context-driven segmentation. Build on open standards and APIs to avoid lock‑in and simplify operations. Security must be foundational, measurable, and auditable from day one.
AI-driven experiences are flipping the traffic mix, pulling more capacity demand toward the uplink than U.S. mobile networks have historically planned for. Generative and vision-based AI are shifting usage from predominantly downloads to more continuous and bandwidth-heavy uploads. Recent benchmarking shows U.S. 5G networks prioritize downlink KPIs more than peers in Asia, even as uplink usage climbs. RootMetrics’ drive testing in late 2025 found all three U.S. carriers set roughly one-fifth of their midband Time Division Duplex (TDD) frame resources for uplink. That gap becomes material as AI, livestreaming, and enterprise camera workloads expand. U.S. carriers continued to win experience awards in early 2026, even as their uplink allocations trailed global leaders.
2027 Intelligence Programs
Scroll to Top
TECKNEXUS MWC BARCELONA 2027
MWC27 EXECUTIVE INSIGHTS PROGRAM

Industry voices. Ideas that move.

SIX MAGAZINES. SIX BIG CONVERSATIONS.
EDITION 01 Networks as Platforms
EDITION 02 AI in the Real World
EDITION 03 The Intelligent Enterprise
EDITION 04 The Future of AI
EDITION 05 Securing the Digital Future
EDITION 06 The Next Frontier

Ways to Participate

Contributed Article Complimentary for eligible MWC sponsors
Sponsored Article & Executive Q&A
Executive Video Interview