Private Network
Intelligence
Intelligence Journeys
Utilities Private Broadband Planning
AI Use Case Planning for Utilities

Fiber

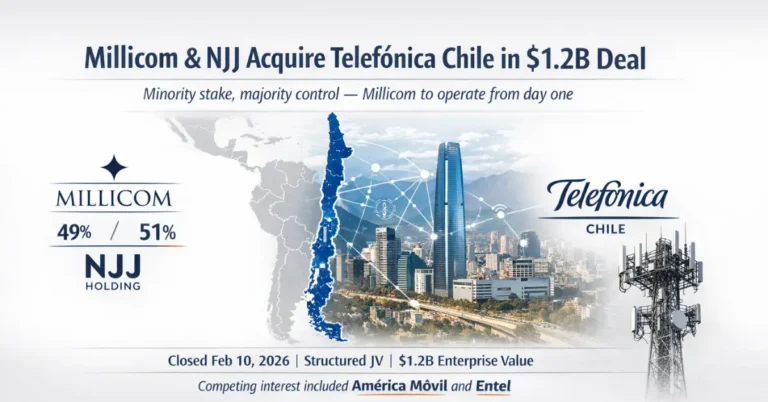
Millicom and NJJ have jointly acquired Telefónica’s Chilean operations in a structure designed to capture upside while insulating Millicom’s balance sheet. Through a jointly controlled vehicle, NJJ holds 51% and Millicom 49% of nearly all of Telefónica’s interest in Chile, with Millicom operating the asset from day one despite its minority stake. The headline value is about $1.2 billion, reflecting a challenged but strategically important footprint in one of Latin America’s most advanced telecom markets. The transaction closed on February 10, 2026, and follows months of speculation that drew interest from other regional heavyweights, including América Móvil and Entel.
LG Uplus is moving from rule-based automation to closed-loop autonomy, using AI agents and digital twins to accelerate toward a fully autonomous network by 2028. Its core platform, the AI Orchestration Nexus (AION), is already automating repetitive operations and has contributed to a reported 70% reduction in customer complaints about network quality—an early signal that the approach is translating into measurable outcomes. The company plans to showcase these capabilities at MWC Barcelona 2026, underscoring growing operator interest in operational AI as 5G matures and traffic patterns become more volatile.
Deutsche Telekom and T-Systems have switched on a sovereign, NVIDIA-powered AI factory in Munich’s Tucherpark, positioning Germany as a serious contender in industrial AI infrastructure. The new facility brings nearly 10,000 NVIDIA Blackwell GPUs online, including DGX B200 systems and NVIDIA RTX Pro Server GPUs, delivering up to 0.5 exaFLOPS of AI compute for training, fine-tuning, and large-scale inference. Operated by T-Systems on German soil, the platform targets industry, research, startups, and the public sector with strict controls for data protection, security, and availability. Early customers include Agile Robots, which is combining vision, robotics, and foundation models, and PhysicsX, which applies AI to technical simulation.
New guidance from the NTIA signals that BEAD-funded satellite providers, including SpaceX’s Starlink, must abide by standard program terms rather than negotiate bespoke carve-outs. An updated NTIA FAQ on subgranting makes clear that states cannot waive or dilute the statutory and programmatic requirements set out in the BEAD NOFO and subsequent guidance. Payments should be tied to objective milestones and verifiable outcomes, not front-loaded without proportional performance. Performance testing, reporting, and documentation must meet program and FCC-aligned standards; subgrantees cannot unilaterally narrow test samples or exclude locations to their advantage. The FAQ effectively answers whether BEAD can be implemented on a “vendor’s terms”: it cannot.
Colombia has cleared a milestone consolidation: Tigo has taken operational control of Movistar, creating a second national-scale incumbent to challenge Claro. The Superintendence of Industry and Commerce (SIC) approved the integration through Resolution 94169 of 2025, capping months of scrutiny and pushback from rivals and ISPs. The merger compresses Colombia’s competitive field at a time when 5G rollouts, fiber densification, and cloud-native cores demand scale. It creates a stronger counterweight to Claro, but also raises real concerns about a two-horse race and the downstream effects on MVNOs, ISPs, and enterprise buyers.
Amazon and Google currently lead the AI capex race, with Microsoft and Meta not far behind, and the prize is control over scarce compute, power, and network resources that define the next decade of cloud and AI services. For telecom and infrastructure players, the opportunity is immediate: deliver power-adjacent, fiber-rich, AI-ready capacity with speed and predictable SLAs. For enterprises, the mandate is pragmatic: secure capacity, design for portability across heterogeneous silicon, and enforce cost governance as inference scales. The winners will be those who pair aggressive buildouts with disciplined execution—turning record capex into durable platforms and customer outcomes.
NGMN’s latest operator-led guidance frames simplification as a precondition for 5G efficiency, sustainability and service agility—not an optional clean-up exercise. NGMN’s new Framework for Network Simplification – An Operator View argues for targeted simplification across radio, core and transport to contain this sprawl while preserving the ability to launch differentiated services. The alliance places cloud‑native design, federated service exposure and AI‑driven operations at the center of that shift, supported by agile ways of working. Simplification is how operators square the circle—cut carbon and cost, while accelerating innovation. The publication offers a practical, non-prescriptive method to decide where simplification delivers the most benefit, and when complexity risk outweighs near-term gains.
Liberty Global and Google Cloud have signed a five-year agreement to deploy AI at scale across Liberty Global’s European footprint and to advance hybrid cloud, autonomous networks, and new go-to-market plays. The partnership spans roughly 80 million fixed and mobile connections across Liberty Global’s operating companies, including Virgin Media O2 in the UK, Telenet in Belgium, VodafoneZiggo in the Netherlands, Virgin Media in Ireland, and Sunrise in Switzerland. On the network side, the companies will co-develop AI-first programs aimed at reliability, security, scalability, and cost efficiency. Commercially, the parties will target SMEs with a joint portfolio that combines connectivity with cloud, cybersecurity, and AI services.
AT&T is deepening ties with Amazon by pairing its national fiber assets with AWS cloud and AI tooling while adding low Earth orbit connectivity from Amazon’s satellite network to fill coverage gaps for business customers. The collaboration has two pillars: cloud modernization on AWS and satellite-enabled reach via Amazon’s LEO network, with AT&T also supplying fiber capacity into AWS data centers to bolster high-performance infrastructure. Amazon’s LEO constellation will deliver fixed broadband connectivity for AT&T Business customers in areas where terrestrial options are limited, enabling primary service in hard-to-reach sites and resilient backup for SD‑WAN architectures.
AT&T has closed its $5.75 billion cash deal to acquire Lumen’s consumer fiber business across 11 states, reshaping competitive dynamics in U.S. fiber-to-the-home and sharpening Lumen’s enterprise focus. The transaction moves more than 1 million fiber subscribers and over 4 million enabled fiber locations, including the Quantum Fiber brand and related consumer access networks, into AT&T’s portfolio. AT&T’s fiber home internet footprint now spans 32 states, adding major metros such as Denver, Seattle, and Salt Lake City where it can bring multi-gig services to market at scale.
Digipower X positions itself as a vertically integrated AI infrastructure operator combining Tier III-certified modular data centers with owned and controlled energy assets to compress deployment cycles. The company cites more than 200 MW currently online across a combined-cycle plant and three additional operational sites, development pathways for up to 1.5 GW over the next three years, and a letter of intent tied to a 1.3 GW power plant in West Virginia that is being evaluated as a long-term AI campus anchor, with additional scale targeted in North Carolina. Its AI-Ready Modular Solution (ARMS) aims to deliver Tier III modular capacity in roughly 180 days, emphasizing redundancy, energy optimization, and liquid-cooling readiness for high-density AI clusters.
The operators that control both dense fiber and performant 5G, and that package them coherently, will set the pace for the next telecom cycle. AT&T’s targets—more fiber passings, higher bundle attach, and measured wireless growth—put it squarely in the camp that sees integrated networks as the winning model. If the company executes on build cadence and cross-sell while keeping experience clean, expect continued share gains in fiber markets and a tougher environment for single-asset competitors. For buyers, the practical takeaway is to lean into converged sourcing now to lock in economics and resiliency as these footprints expand.

Partner Hubs

Telco AI Agent Leadership

Telco AI Agent Leadership Landscape - Network Equipment Vendors
Network Equipment Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
OSS/BSS Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
System Integrator Report
Scroll to Top