Private Network
Intelligence
Intelligence Journeys
AI Use Case Planning for Utilities
Utilities Private Broadband Planning
https://www.ciena.com/insights/blog/2026/rls-hyper-rail-solving-the-challenges-of-multi-rail-photonics?campaign=X1994626&channel=media-direct-buy&medium=display&source=tecknexus&ad-type=&campaign-type=&term=&region=&lid=D3JLmZ

America

ElevenLabs raised $500 million in Series D funding at an $11 billion valuation, led by Sequoia Capital with continued participation from Andreessen Horowitz and ICONIQ, and new backing from Lightspeed, Evantic Capital and BOND alongside existing investors. The company says it has surpassed key ARR milestones and reported strong enterprise adoption across sectors through 2025, with telecom emerging as a priority vertical as operators seek to modernize legacy IVR and contact center stacks. Conversational agents can replace keypad IVRs with natural dialogue that recognizes intent, confirms identity, retrieves context and executes actions across channels.
Rogers Communications has moved from beta to a commercial footprint for satellite-to-mobile in Canada, extending basic connectivity and select apps to consumer smartphones while adding an industrial IoT tier for remote operations. The new Rogers Satellite service enables a curated set of popular apps to work beyond terrestrial coverage, including WhatsApp calling, Google Maps, AccuWeather, X, and CalTopo on most modern smartphones. In parallel, Rogers introduced satellite-to-mobile for IoT businesses, targeting asset tracking along highways and rail, as well as sensor telemetry in forestry, mining, and other resource sectors where terrestrial cellular is sparse.
Paramount Skydance launched a hostile, board-bypassing tender offer to acquire all of Warner Bros. Discovery (WBD) at $30 per share, valuing the company at about $108 billion on an enterprise basis. The bid arrives days after WBD agreed to sell its studio and streaming assets—including Warner Bros. studios, HBO, and Max—to Netflix in a cash-and-stock deal valued at roughly $72 billion. Paramount’s pitch: more cash, full-company certainty, and a quicker path to close. The outcome will determine control of premium U.S. content, set the pace of streaming consolidation, and ripple into network traffic, advertising markets, and device and distribution partnerships.
Ericsson’s latest Mobility Report points to a clear shift: operators are turning 5G capabilities into differentiated, SLA-backed services rather than just selling more data at higher speeds. After years of building coverage and capacity, 5G networks are mature enough to commercialize features like guaranteed latency, uplink boosts, and application-aware prioritization. The catalysts are in place: more 5G Standalone (SA) cores, rising traffic from video creation and immersive apps, and enterprise demand for predictable performance across sites and clouds. The net result is momentum behind premium, differentiated connectivity that can be priced, assured, and exposed to partners.
New performance data shows U.S. WISPs are getting faster, but low‑Earth orbit players like Starlink are advancing just as quickly—and the competitive gap in rural markets is narrowing. Based on Speedtest Intelligence data from Q1 2021 to Q2 2025, eight of the larger WISPs—Starry, Resound Networks, Nextlink, Wisper Internet, Unwired Broadband, GeoLinks, Etheric Networks, and Rise Broadband—improved speeds, with download gains outpacing uploads. Starry led by a wide margin with a 202 Mbps median download in Q2 2025, followed by Resound at 99 Mbps and Nextlink at 68 Mbps; GeoLinks trailed at 23 Mbps. Crucially, only a minority of WISP users consistently achieve the FCC’s 100/20 Mbps fixed broadband benchmark.
Amazon has moved its low Earth orbit broadband effort out of code-name mode and into a market-facing brand with strategic implications for telecom and enterprise buyers. Project Kuiper is now Amazon Leo, a direct reference to the low Earth orbit constellation underpinning the service. The rebrand signals a transition from R&D to commercial execution. Amazon reports more than 150 satellites in orbit today—roughly 153 by recent counts—following a string of successful launches and a completed prototype mission. The company says it will light up service as it adds coverage and capacity.
NEC is moving to scale its cloud and SaaS business support capabilities with a $2.9 billion acquisition of CSG Systems International, positioning Netcracker at the center of the combined telecom monetization play. CSG brings a sizable recurring-revenue portfolio in digital BSS, billing, charging, and customer engagement used by communications, cable, media, and digital service providers, complementing Netcracker’s OSS/BSS, orchestration, and service automation strengths. The all-cash deal values CSG at approximately $2.9 billion on an enterprise value basis and has unanimous board approval, with closing targeted for 2026 pending CSG shareholder approval and customary antitrust and other regulatory reviews.
According to the latest Speedtest Intelligence findings from Ookla, the share of states where at least 60% of tested fixed-broadband users achieve the FCC’s 100 Mbps down/20 Mbps up benchmark rose sharply between late 2024 and the first half of 2025. That count climbed from 22 states (plus Washington, D.C.) to 38 states (plus D.C.), signaling faster last‑mile networks and better in-home performance for a sizable portion of U.S. households. Progress on equity also accelerated. In the first half of 2025, 33 states reduced the performance gap between urban and rural users—while 17 saw the gap widen versus the second half of 2024.
Nokia delivered a stronger-than-expected third quarter, with comparable operating profit reaching €435 million against consensus of about €342 million. Group net sales rose 12% to €4.83 billion, above forecasts, driven by Optical Networks and cloud-related demand tied to AI data centers. The stock jumped double digits intraday and added billions in market value, reflecting newfound confidence after a challenging first half. The recovery now is concentrated in network infrastructure rather than mobile RAN, underscoring where customers are actually spending to handle AI-era traffic patterns. Nokia nudged its full-year operating profit outlook to €1.7–2.2 billion, with a reporting change related to scaling down passive venture investments partly in play.
Germany’s largest operator is turning e-waste into engagement currency with a take-back drive that mixes material recovery with headline incentives. Deutsche Telekom estimates 195 million unused phones are sitting idle in Germany, locking up valuable materials and ESG progress. The company is reframing those devices as an urban mine—rich in gold, copper, and critical minerals—and as a lever to scale circularity ahead of its 2030 ambition to make all IT and network technology, and most end-user devices, recyclable or reusable. By the end of 2024, the operator had already taken back more than 11 million phones across the group.
Amazon is piloting AI-enabled smart glasses for delivery associates to streamline last‑mile workflows, adding a hands‑free heads‑up display that blends navigation, scanning, and proof‑of‑delivery into the driver’s field of view. The company is testing delivery‑specific smart glasses that use on‑device computer vision and AI to identify packages, surface hazards, and guide walking routes from the vehicle to the doorstep without requiring a phone in hand. When a van is parked, the device activates and shows the next task: find the right parcel in the vehicle, traverse complex environments like multi‑unit buildings, and confirm delivery with visual capture.
A planned merger between Lynk Global and Omnispace aims to fuse spectrum assets, satellite technology, and SES’s multi-orbit infrastructure to scale 3GPP-compliant direct-to-device services worldwide. The combined company will pair Omnispace’s globally coordinated S-band holdings, about 60 MHz anchored by ITU filings and aligned to non-terrestrial network standards—with Lynk’s patented multi-spectrum D2D platform. SES, already an investor in both firms, will become a major strategic shareholder and provide access to its GEO and MEO assets and ground network to improve coverage, resiliency, and time-to-market. Lynk has already launched commercial messaging and alerting in small markets with a handful of LEO spacecraft.
https://www.ciena.com/insights/blog/2026/rls-hyper-rail-solving-the-challenges-of-multi-rail-photonics?campaign=X1994626&channel=media-direct-buy&medium=display&source=tecknexus&ad-type=&campaign-type=&term=&region=&lid=D3JLmZ

Partner Hubs

Telco AI Agent Leadership

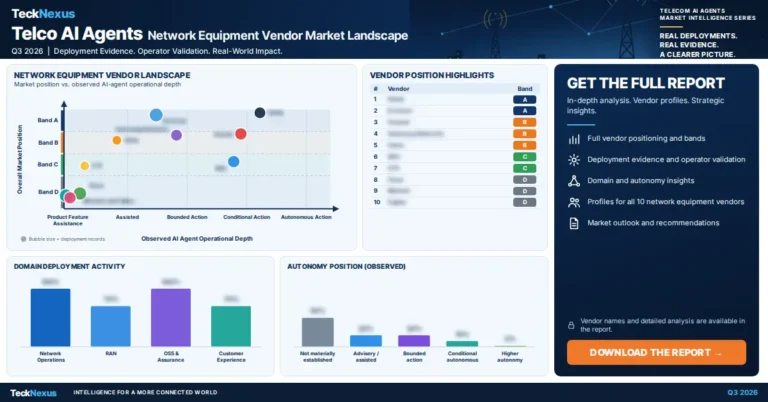
Telco AI Agent Leadership Landscape - Network Equipment Vendors
Network Equipment Vendor Report
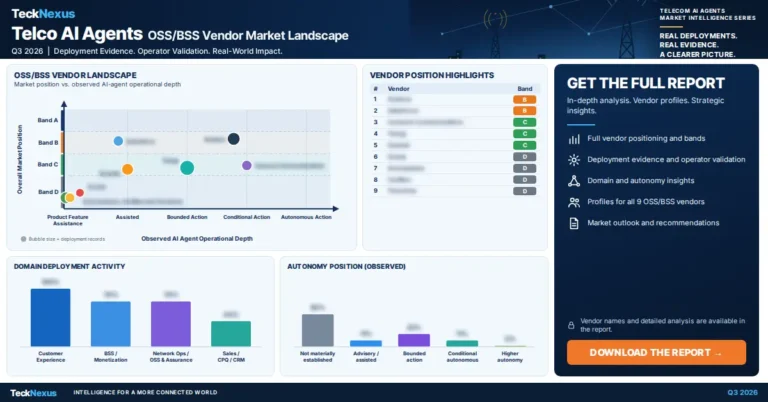
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
OSS/BSS Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
System Integrator Report
Scroll to Top