Private Network
Intelligence
Intelligence Journeys
AI Use Case Planning for Utilities
Utilities Private Broadband Planning
https://www.ciena.com/insights/blog/2026/rls-hyper-rail-solving-the-challenges-of-multi-rail-photonics?campaign=X1994626&channel=media-direct-buy&medium=display&source=tecknexus&ad-type=&campaign-type=&term=&region=&lid=D3JLmZ

America

Enterprise demand is shifting from project-based consulting to managed, outcome-driven operations infused with AI and data. By combining WNS's scaled operations with Capgemini's consulting, engineering, and cloud capabilities, the company aims to capture this demand with end-to-end, AI-enabled "run and transform" offerings. The deal expands Capgemini's delivery footprint in India, strengthens its business services unit, and adds vertical platforms and playbooks that can be cross-sold to Capgemini's installed base in North America and Europe. For WNS clients, it opens access to broader transformation capabilities—cloud, data, and engineering—while preserving managed services continuity.
Ericsson’s Microwave Outlook 2025 points to a backhaul market that will be almost evenly split between microwave and fiber by 2030, reshaping transport decisions for dense 5G and future 6G builds. Microwave already carries traffic for most live 5G networks worldwide, and a rising mix of E-band and emerging higher bands is closing the capacity gap with fiber for short- to medium-range links. For operators facing site densification, fiber lead times, and rising build costs, microwave provides a fast, resilient, and cost-optimized path to scale. E-band deployments are accelerating and overtaking legacy 38 GHz usage in several markets.
AI is everywhere in telecom, yet most pilots never make it into production because the industry’s data, tooling, and operating models are not ready for scaled automation. Recent industry research suggests that about 95% of AI pilots in telecom fail to scale beyond proofs of concept. Leaders are moving from pilots to platforms by embedding AI in the systems that run the business and anchoring every initiative to measurable outcomes. Telecom AI will not scale through pilots alone; it scales when embedded in the systems that run revenue, experience, and networks.
In 2024, the U.S. cable sector generated $568.7 billion in total economic output and supported 1.3 million jobs across the country. This footprint spans broadband networks, video programming, construction, manufacturing, and a broad vendor ecosystem. It underscores why cable remains a central pillar of America’s connectivity and media economy even as consumption shifts to IP and streaming. Cable broadband providers—led by Comcast, Charter Communications (Spectrum), Cox, Altice USA (Optimum), Mediacom, Cable One (Sparklight), and WOW!—accounted for $366 billion in total economic impact and nearly 888,000 jobs.
Telefónica reports €77 billion invested over ten years to expand sustainable, resilient connectivity, with SDG 9 (industry, innovation and infrastructure) as the strategic anchor. The operator now serves nearly 350 million accesses, has passed 81.4 million premises with FTTH, and runs one of the largest ultra-broadband footprints globally, second in scale only to China. Spain is Telefónica’s showcase for fiber-led modernization. Dense FTTH has enabled a managed copper switch-off, which simplifies operations, cuts energy use, and improves service quality. The operator targets net zero by 2040 - ten years ahead of many international timelines—and reports a 52% reduction in CO2 emissions across the value chain from 2015 to 2024.
Lumen is accelerating a multi-year, multi-billion-dollar expansion of its U.S. backbone to match the explosive rise of AI-driven traffic. The company plans to add 34 million new intercity fiber miles by the end of 2028, targeting a total of 47 million intercity fiber miles. In 2025, Lumen has already added more than 2.2 million intercity fiber miles across 2,500+ route miles, with a year-end target of 16.6 million intercity fiber miles. Network capacity grew by 5.9+ Pbps year-to-date, and Lumen earmarked more than $100 million to push 400Gbps connectivity across clouds, data centers, and metros—now covering over 100,000 route miles with 400G-enabled transport.
Manufacturers and wireless providers are shifting 5G from promising pilots to scaled, revenue‑relevant deployments across American factories. A joint report from the National Association of Manufacturers (NAM) and CTIA underscores a clear inflection point: commercial 5G, industrial AI and edge computing are maturing together. With 3GPP Release 16/17 capabilities such as URLLC, time‑sensitive networking integration, network slicing and non‑public networks, 5G is increasingly able to support time‑critical control, quality inspection and safety systems at scale. Production use cases are expanding and delivering measurable benefits. The message is consistent: companies that operationalize 5G alongside AI and automation will capture disproportionate productivity and resiliency advantages.
With the FCC under pressure to deliver 300 MHz of auctionable spectrum, a group of Senate Republicans is urging the agency to preserve the shared 3.5 GHz CBRS band and the unlicensed 6 GHz band that underpin private 5G and next‑gen Wi‑Fi. Ten Senate Republicans, including five members of the Senate Commerce Committee, sent a letter urging the FCC to ensure existing operations in the 6 GHz and Citizens Broadband Radio Service (CBRS) bands continue “without disruption.” NTIA Administrator Arielle Roth called for preserving 6 GHz for Wi‑Fi, a stance applauded by NCTA as a recognition that unlicensed spectrum is an economic engine.
The quarter’s growth underscores a resilient access capex cycle despite macro uncertainty, with fiber and fixed wireless access (FWA) deployments offsetting sluggish cable spend. Fiber PON platforms and 5G FWA customer premises equipment (CPE) drove the uptick, while DOCSIS infrastructure outlays fell 13% year over year on weaker Remote PHY Device (RPD) purchases and a slowdown in new virtual CMTS (vCMTS) licenses. The competitive center of gravity in broadband is shifting. Operators prioritizing XGS-PON rollouts and 5G FWA are growing faster and spending more, while cable operators are pacing upgrades and deferring some distributed access architecture (DAA) investments.
SpaceX wants the FCC to count Starlink as “advanced” broadband in its annual Section 706 report, a move that could reshape funding, benchmarks, and competition in rural internet buildouts. In 2024, the agency set a 100/20 Mbps benchmark, added affordability and adoption metrics, and floated a long-term goal of 1 Gbps/500 Mbps. SpaceX argues that excluding LEO distorts the national picture. The company says Starlink serves more than 2 million U.S. subscribers and posts median peak-hour speeds near 200 Mbps today. Rural electric co-ops and community telcos counter that LEO networks remain capacity constrained and variable.
Verizon Value is rolling out enhanced prepaid international services across its Simple Mobile and Total Wireless brands, sharpening its competitive edge in global roaming and cross-border communications starting August 28, 2025. The offers blend unlimited international calling to large country sets, global texting, and expanded roaming with 5G access on Verizon's network, including 5G Ultra Wideband on select tiers. Simple Mobile adds unlimited global texting across all plans and scales international calling and data inclusions from entry to premium tiers. Total Wireless retools its unlimited structure with a five-year price guarantee (taxes and fees included), adds 95 more calling destinations (up to 180 countries on higher tiers), and doubles roaming coverage to 30+ countries.
More than $14 billion has been invested across the CBRS stacklicenses, RAN, devices, infrastructure, sensors, and software. Over 420,000 CBRS radio nodes (CBSDs) are in service. The device ecosystem is broad: Apple and Samsung ship n48-capable handsets; industrial and FWA suppliers support n48 CPEs and routers; Ericsson, Nokia, Samsung, JMA Wireless and others provide radio and DAS. This is not a pilot; it is production infrastructure. Refarming would force replacement or retuning of hundreds of thousands of base stations and millions of end devices, plus upgrades to SAS integrations and enterprise control planes.
https://www.ciena.com/insights/blog/2026/rls-hyper-rail-solving-the-challenges-of-multi-rail-photonics?campaign=X1994626&channel=media-direct-buy&medium=display&source=tecknexus&ad-type=&campaign-type=&term=&region=&lid=D3JLmZ

Partner Hubs

Telco AI Agent Leadership

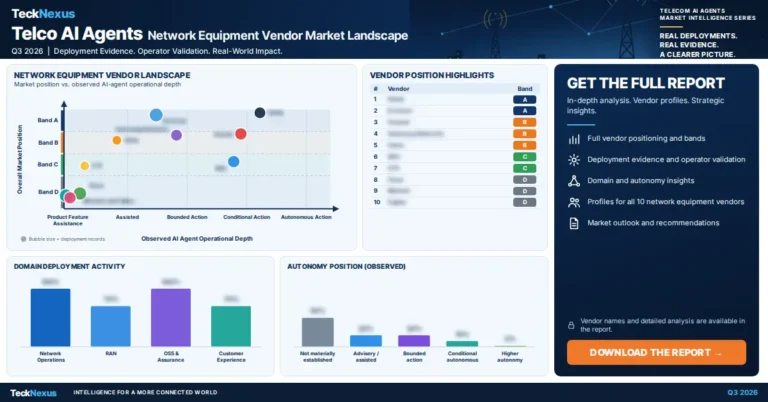
Telco AI Agent Leadership Landscape - Network Equipment Vendors
Network Equipment Vendor Report
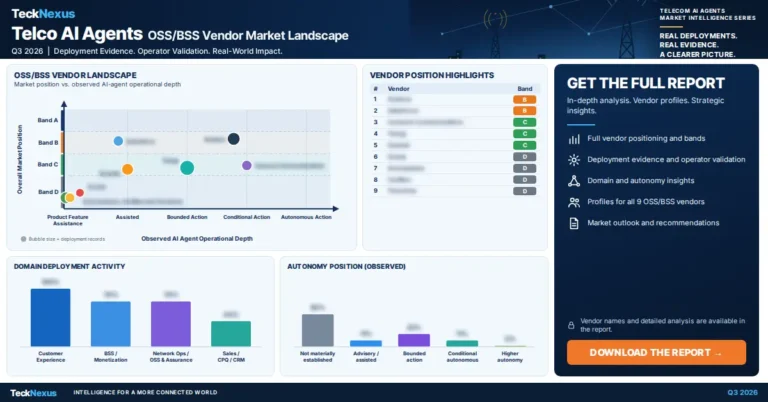
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
OSS/BSS Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
System Integrator Report
Scroll to Top