Private Network
Intelligence
Intelligence Journeys
Utilities Private Broadband Planning
AI Use Case Planning for Utilities
https://www.ciena.com/insights/blog/2026/rls-hyper-rail-solving-the-challenges-of-multi-rail-photonics?campaign=X1994626&channel=media-direct-buy&medium=display&source=tecknexus&ad-type=&campaign-type=&term=&region=&lid=D3JLmZ

Network Slicing

Network slicing partitions a single physical network into multiple virtual networks, each tuned for specific performance, latency, or reliability requirements, all running on shared infrastructure. It depends on 5G standalone’s flexible, software-defined core, and is a key enabler of differentiated services — dedicated slices for enterprises, critical communications, or specific applications — and therefore a route to new operator revenue. In practice, slicing has advanced more slowly than early expectations, constrained by standalone deployment pace, operational complexity, and unproven demand. For operators, the question is which customers will pay for guaranteed, differentiated connectivity; for enterprises, whether a slice beats a private network. This channel tracks network slicing standards, deployments, and commercial models, with analysis of where slicing is delivering real services and where it remains a capability waiting for a market.

Mobile Private Networks (MPNs) have reached a critical juncture, evolving from niche deployments to scalable, production-ready solutions. Enterprises are now embracing MPN-as-a-Service, combining edge computing, AI-driven operations, and hybrid spectrum strategies to deliver low-latency, secure, and flexible connectivity. Discover how Wi-Fi integration, automation, and vendor-agnostic deployment models are accelerating MPN adoption across industries.
Orange has signed a binding agreement to buy Lorca’s remaining 50% stake in MasOrange for 4.25 billion euros in cash, targeting completion in the first half of 2026 subject to customary approvals. The agreement transitions MasOrange from a 50:50 joint venture to a wholly owned subsidiary of Orange, consolidating governance and simplifying decision-making across mobile, fixed, and converged operations in Spain. At closing, MasOrange is expected to be fully consolidated into Orange’s accounts, including MasOrange debt that Orange plans to refinance at or after completion, providing flexibility to optimize the capital structure and cost of capital.
IBM has agreed to acquire Confluent for $31 per share in cash, signaling a decisive move to make real-time, governed data the backbone of generative and agentic AI across hybrid cloud environments. The transaction values Confluent at an enterprise value of roughly $11 billion, with closing targeted by mid-2026 pending shareholder and regulatory approvals. Together they aim to unify application, data, and AI pipelines across public clouds, private data centers, and edge locations—reducing integration friction and accelerating time to value for enterprise AI.
Reliance Jio’s path to a mid-2026 IPO is increasingly intertwined with the timing and magnitude of India’s next mobile tariff hike. Domestic brokers argue Jio has a tactical reason to push back on near-term tariff increases: hikes tend to accelerate Bharti Airtel’s revenue market share (RMS) gains more than Jio’s, narrowing the lead at the worst possible time for an IPO. Airtel has been the key beneficiary of previous price actions, chipping away at Jio’s RMS advantage by almost two percentage points since mid-2024. On current assumptions, Jio is informally pegged around $153 billion, implying an EV/EBITDA multiple near the low teens.
Switzerland’s SBB has deployed an Ericsson IMS/VoLTE platform that interworks with legacy GSM-R, delivering Europe’s first live bridge between public 4G voice and mission-critical railway communications. Ericsson and SBB completed a nationwide IMS/VoLTE integration that extends reliable voice communications across Switzerland’s 3,100 km rail network and removes dependency on public 3G roaming for coverage gaps outside GSM-R footprints. The IMS core integrates multi-supplier elements and preserves EIRENE features such as functional numbering, group calls, emergency stop calls, and onboard announcements, ensuring safety-critical behavior is maintained. It also demonstrates that mission-critical requirements can be met over modern IP telephony when engineered with the right interworking, governance, and testing.
Nvidia used NeurIPS to expand an open toolkit for digital and physical AI, with a flagship reasoning model for autonomous driving and a broader stack that targets speech, safety, and reinforcement learning. Nvidia introduced DRIVE Alpamayo-R1 (AR1), an open vision-language-action model that fuses multimodal perception with chain-of-thought reasoning and path planning, aiming to push toward Level 4 autonomy in constrained domains. To lower adoption friction, Nvidia published the Cosmos Cookbook with step-by-step recipes for data curation, synthetic data generation, inference, and post-training workflows, enabling customization for diverse physical AI use cases.
Ericsson’s latest Mobility Report points to a clear shift: operators are turning 5G capabilities into differentiated, SLA-backed services rather than just selling more data at higher speeds. After years of building coverage and capacity, 5G networks are mature enough to commercialize features like guaranteed latency, uplink boosts, and application-aware prioritization. The catalysts are in place: more 5G Standalone (SA) cores, rising traffic from video creation and immersive apps, and enterprise demand for predictable performance across sites and clouds. The net result is momentum behind premium, differentiated connectivity that can be priced, assured, and exposed to partners.
India’s 5G market has entered a scale phase, with momentum pointing to more than a billion subscribers and deeper network modernization over the next six years. Ericsson’s latest Mobility Report projects over 1 billion 5G subscriptions in India by end-2031, representing about 79% of the country’s mobile base. Average mobile data usage per active smartphone in India stands near 36 GB per month and is forecast to approach 65 GB per month by 2031. Two demand-side levers stand out: affordable 5G devices and expanding Fixed Wireless Access (FWA), accelerating mainstream adoption and opening a credible substitute to wired broadband in underserved areas.
Verizon will cut more than 13,000 roles as part of a broader restructuring aimed at simplifying operations and resetting its cost base for the next phase of growth. The reduction represents roughly 13% of Verizon’s reported ~100,000 full-time workforce and about one-fifth of its non-union management ranks, according to figures shared alongside the announcement. In parallel, Verizon plans to curb outsourcing and other external labor spending, convert 179 company-owned retail stores to franchise operations, and shutter one store. The restructuring reflects subscriber headwinds and a need to rebalance costs as 5G investment priorities shift from buildout to monetization and automation.
Jeff Bezos is stepping back into day-to-day operations as co-CEO of Project Prometheus, a new AI company reportedly funded with $6.2 billion to build “AI for the physical economy.” Project Prometheus will be co-led by Bezos and Vik Bajaj, an operator-scientist with leadership experience at Google X, Verily, and Foresite Labs. Early reports indicate the company is targeting engineering and manufacturing tasks across sectors such as aerospace, automotive, and computing hardware. Headcount is already near 100, drawing researchers from OpenAI, Google DeepMind, and Meta, signaling an aggressive push for top-tier AI talent.
S&P Global Ratings has upgraded Bharti Airtel on the back of stronger earnings quality, healthier free cash flow, and a clearer deleveraging path, signaling a maturing Indian mobile market. The action reflects rising confidence that India’s tariff repair is sticking after mid-2024 hikes, with average revenue per user moving up and a larger share of premium 4G/5G subscribers. Airtel’s fiscal Q2 (India) showed operating momentum and cash discipline—key ingredients behind the rating move. Tariff increases and a richer subscriber mix pushed ARPU above the psychologically important INR 200 threshold, aided by postpaid gains, 4G/5G migration, and bundled content.
The Las Vegas Grand Prix is more than a spectacle this year—it’s a real-world benchmark for what 5G Standalone can deliver under extreme density, with T-Mobile integrating slicing, private 5G and edge video into broadcast, venue ops and public safety workflows. Broadcast teams are ingesting 360-degree and drone feeds over 5G with edge processing, venue commerce runs on a dedicated slice, and police leverage a 5G-connected drone for situational awareness. These deployments illustrate a practical blueprint for monetizing 5G SA and edge in venues, media, public safety and large events.

Frequently Asked Questions

What is network slicing in simple terms?
It’s the ability to carve a single physical 5G network into multiple virtual, independently configured slices, each with its own guaranteed performance characteristics for speed, latency, and reliability, so an operator can sell different service tiers off the same infrastructure rather than building separate networks for each use case. Each slice behaves, from the customer’s perspective, like a dedicated network tailored to their specific needs, even though it’s actually running on shared physical infrastructure alongside other slices serving completely different customers simultaneously. This is conceptually similar to how a single physical server can run multiple virtual machines that each behave like an independent computer, applied instead to network connectivity.
Is network slicing actually commercially available, or still experimental?
It has moved from pilot to early commercial deployment. Major carriers including T-Mobile, Verizon, Reliance Jio, and Singtel have launched commercial slicing-based offers for specific use cases, and telecom operators are described as the primary enablers of slicing technology, expected to hold roughly 62 percent of the market in 2026. That said, the industry consistently describes network slicing as being in the early stages of commercialization, meaning successful pilots are still being converted into broader, more scalable commercial offerings rather than slicing having become a fully mature, universally available product.
What’s a real-world example of network slicing in use?
Singtel partnered with Tencent Games to launch a dedicated low-latency network slice for cloud gaming in Singapore, described as the first nationwide gaming-specific network slice in the world, letting users play without downloading games or needing high-end hardware. Verizon Business launched a dedicated fixed wireless access slice for enterprise customers with guaranteed performance, extending slicing beyond mobile use cases into business broadband. Nokia and the UAE operator du were reportedly first in the industry to deploy autonomous network slicing, which automates the creation and management of slices rather than requiring extensive manual configuration.
Why does network slicing require 5G Standalone (SA)?
True dynamic, end-to-end network slicing depends on a 5G core built independently of 4G, known as 5G Standalone or SA architecture, since SA provides the flexibility and granular control needed to create, manage, and guarantee performance across multiple isolated virtual networks simultaneously. Non-standalone 5G, which still relies on a 4G core for certain control functions, can support some slicing-like capabilities but generally not with the same flexibility, automation, or end-to-end performance guarantees that SA enables. This is one of the main reasons operators have prioritized SA core upgrades specifically as a foundation for unlocking more advanced monetization opportunities like network slicing.
How big is the network slicing market expected to get?
Forecasts vary considerably depending on the specific market research firm, but most analyses put network slicing’s growth rate above 40 percent annually through the late 2020s, driven primarily by telecom operators monetizing differentiated connectivity for industries like healthcare, automotive, gaming, and manufacturing. Asia Pacific is generally described as leading global adoption given its large population base and diverse industrial use cases, while North America is often projected as the fastest-growing region given strong infrastructure investment. These projections should be treated with appropriate caution though, since the underlying market remains in an early commercialization phase.
Who actually manages and creates network slices in practice?
In practice, network slices are created and managed through orchestration software that translates a specific business requirement, such as guaranteed low latency for a particular customer’s application, into the actual technical configuration needed to deliver it across the relevant network infrastructure. This orchestration layer handles tasks like allocating the right combination of radio, transport, and core network resources to a given slice, monitoring whether it’s actually delivering its promised performance, and adjusting resource allocation dynamically as conditions change. More advanced, automated approaches, sometimes called autonomous network slicing, aim to handle much of this process automatically rather than requiring extensive manual configuration by network engineers each time.
What technical challenges have slowed broader network slicing adoption?
Several technical challenges have slowed broader adoption beyond the foundational requirement of upgrading to 5G Standalone infrastructure. Ensuring consistent performance guarantees across a slice that may span multiple different network domains, from radio access through transport and core, requires sophisticated end-to-end orchestration and assurance capabilities that have taken time to mature. Interoperability across different vendors’ equipment adds further complexity for operators running multi-vendor networks. There’s also a more fundamental business challenge: defining a manageable, scalable set of standard slice types that cover most customer needs, rather than requiring a fully custom-built slice for every individual customer, which would be operationally impractical at scale.
How is network slicing different from older approaches like VPNs or dedicated lines?
Older approaches like traditional VPNs or dedicated leased lines could provide a degree of network differentiation and security for specific customers, but they generally required separate, often physically distinct infrastructure or fixed, manually provisioned configurations that were slow and expensive to set up and change. Network slicing achieves a broadly similar goal, providing differentiated, somewhat isolated connectivity for a specific customer, but does so dynamically and through software, on top of shared underlying 5G infrastructure, without requiring separate physical infrastructure for each customer. This makes slicing considerably faster and cheaper to provision than traditional dedicated infrastructure approaches, while still providing meaningful performance guarantees and isolation.

Partner Hubs

Telco AI Agent Leadership

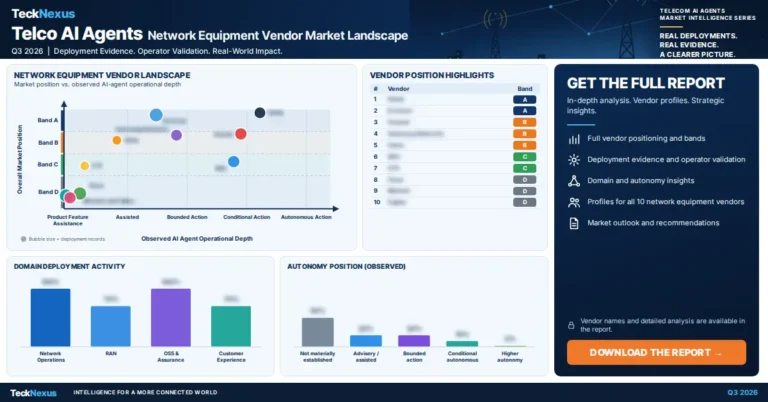
Telco AI Agent Leadership Landscape - Network Equipment Vendors
Network Equipment Vendor Report
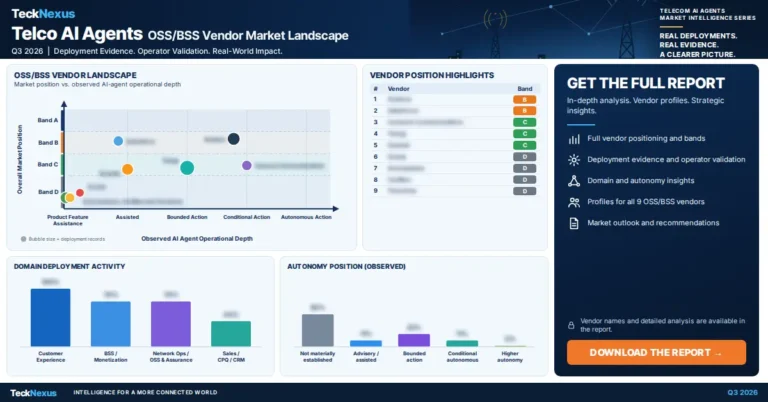
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
OSS/BSS Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
System Integrator Report
Scroll to Top