Private Network
Intelligence
Intelligence Journeys
Utilities Private Broadband Planning
AI Use Case Planning for Utilities
https://www.ciena.com/insights/blog/2026/rls-hyper-rail-solving-the-challenges-of-multi-rail-photonics?campaign=X1994626&channel=media-direct-buy&medium=display&source=tecknexus&ad-type=&campaign-type=&term=&region=&lid=D3JLmZ

Network Slicing

Network slicing partitions a single physical network into multiple virtual networks, each tuned for specific performance, latency, or reliability requirements, all running on shared infrastructure. It depends on 5G standalone’s flexible, software-defined core, and is a key enabler of differentiated services — dedicated slices for enterprises, critical communications, or specific applications — and therefore a route to new operator revenue. In practice, slicing has advanced more slowly than early expectations, constrained by standalone deployment pace, operational complexity, and unproven demand. For operators, the question is which customers will pay for guaranteed, differentiated connectivity; for enterprises, whether a slice beats a private network. This channel tracks network slicing standards, deployments, and commercial models, with analysis of where slicing is delivering real services and where it remains a capability waiting for a market.

5G standalone networks change the service model. Operators can carve the network into slices with distinct latency, reliability, and throughput characteristics validated by 3GPP standards. That enables ultra-reliable low-latency communications for factory automation, connected vehicles, remote operations, and mission-critical services. It also enables differentiated quality for cloud gaming, broadcast-like video, and IoT control loops when combined with edge computing and time-sensitive networking. Jio’s position is that treating all traffic identically under a single “internet access” umbrella can inhibit these new uses. A ruleset that preserves open internet principles for consumers yet explicitly allows specialized services with assured QoS for enterprises is what the company seeks.
CAF’s signalling division and Cellnex demonstrated that OPTIO, a modular and multi-bearer CBTC platform, operates reliably on a private 5G network in both lab and field conditions, including challenging scenarios such as tunnels. The system already supports Wi‑Fi and LTE; adding 5G confirms a multi-access design that lets operators choose the right bearer per line, phase, or location. Private 5G brings ultra-low latency, higher capacity, stronger QoS control, and end-to-end security under the operator’s domain. The project received European co-financing via the Recovery and Resilience Facility under Spain’s UNICO Sectorial 2023 program, underscoring public support for digital rail modernization.
A new neutral host 5G deployment at 10 World Trade in Boston’s Seaport sets a practical blueprint for scalable, multi-operator indoor connectivity in Class A commercial real estate. Most mobile traffic is generated indoors, yet macro networks struggle to penetrate dense, energy-efficient buildings. The 10 World Trade deployment—delivered by Boston Global Investors (BGI) with Aspen Venue Partners and Ericsson - addresses all three pressures with a small-cell-based, neutral host design that multiple operators can share while also supporting private 5G and future network slicing. The model aligns with broader industry trends: 3GPP-based indoor systems, shared infrastructure economics, and spectrum agility that includes CBRS in the U.S.
Nokia’s tie-up with OneLayer brings carrier-grade security and OT-aware visibility into one stack, addressing the core adoption barrier for private 5G/LTE in utilities: protecting highly distributed, mission-critical operations at scale. Together, the companies deliver a zero-trust model that spans radio to application: authenticated device identity, continuous posture assessment, role-based segmentation at the cellular (DNN/QoS flow) and IP layers, and orchestrated mitigation. Bottom line: With utilities accelerating private LTE/5G rollouts, Nokia and OneLayer are packaging the controls that regulators, insurers, and boards now expect—bringing OT-aware zero trust into the cellular domain without adding operational complexity.
LG Uplus is working with AWS on agentic AI that automates installation of cloud‑native network software, with early claims of up to 80% faster turn‑ups versus manual methods. LG Uplus and AWS partnered to develop an AI-driven approach that installs complex network software stacks without human intervention. The system uses Amazon Bedrock alongside AWS’s Strands-Agents SDK to orchestrate multiple cooperating AI agents. These agents are pre-trained on network design and implementation documents so they can execute the full workflow - provisioning cloud infrastructure, collecting device and network parameters, generating configurations, performing installation, and troubleshooting.
Vodafone named Dell Technologies a strategic infrastructure provider for a five-year Open RAN buildout across Europe, signaling a move from trials to scaled, automated 5G networks. Vodafone will expand one of Europe’s largest Open RAN footprints using Dell infrastructure as part of a multi-year radio access modernization program. Dell will supply its PowerEdge XR8000 series servers, including the XR8620t and the latest XR8720t with Intel Xeon 6 SoC. Vodafone also plans to adopt the Dell Telecom Infrastructure Automation Suite (DTIAS) to provide the Infrastructure Management Service within its Open RAN architecture, designed to automate Day 0/1/2 lifecycle operations for O-Cloud infrastructure.
NEC is moving to scale its cloud and SaaS business support capabilities with a $2.9 billion acquisition of CSG Systems International, positioning Netcracker at the center of the combined telecom monetization play. CSG brings a sizable recurring-revenue portfolio in digital BSS, billing, charging, and customer engagement used by communications, cable, media, and digital service providers, complementing Netcracker’s OSS/BSS, orchestration, and service automation strengths. The all-cash deal values CSG at approximately $2.9 billion on an enterprise value basis and has unanimous board approval, with closing targeted for 2026 pending CSG shareholder approval and customary antitrust and other regulatory reviews.
India has ceded the lowest-tariff crown to Bangladesh and Egypt, yet it still leads on value through generous allowances and low data unit costs. Indian base plans commonly include unlimited voice, whereas Bangladesh and Egypt restrict voice to roughly 100 and 70 minutes respectively at entry level. On data, incremental purchase economics are unusually attractive: an extra Rs 100 typically buys around 26 GB, or about Rs 4 per GB, keeping India among the most affordable data markets globally. Even after adjusting for purchasing power parity, India remains at the affordable end of global tariff rankings.
The partnership targets two fronts: mission-critical rail communications for operations and high-speed broadband for passengers. The scope includes deploying advanced 5G infrastructure, testing FRMCS-based use cases, and running a real-world trial on an existing SAR line to validate performance, integration, and safety requirements. An innovation and test lab will be established to accelerate solution validation, and SAR teams will be trained on FRMCS/5G rail technologies to build in-house capability. The partners will explore 5G Standalone capabilities for operational communications, including quality-of-service guarantees, redundancy, and resilience needed for rail. FRMCS-aligned services such as mission-critical push-to-talk/data/video (MCX), Railway Emergency Call, and secure staff communications will be validated for integration with signaling and control systems.
Vodafone is partnering with Irish firm Zinkworks on Rapid RIC, a central platform that blends secure data analytics, a visual low-code interface, and code-generating AI to create and operate RAN applications, or rApps. The goal is ambitious but specific: cut time-to-market from months to weeks, scale deployments across markets, and improve service quality, capacity, and energy use. The platform is slated for early 2026 availability and will run primarily on Vodafone’s private Google Cloud Platform environment. Rapid RIC uses GenAI to generate production-grade code from visual designs, enabling radio engineers to turn domain knowledge directly into software without deep AI or ML skills.
Industry capex remained exceptionally strong in 2024, underscoring broadband’s status as critical infrastructure for the digital and AI economy. Broadband providers invested an estimated $89.6 billion in U.S. communications infrastructure last year, pushing cumulative investment since 1996 to more than $2.2 trillion and keeping the 2020–2024 average above $90 billion annually. Spend concentrated on fiber deepening, rural reach, wireless capacity, and overall network scale for AI, cloud, and streaming workloads. While 2024 trailed 2023’s higher tally, it still signals a sustained, competitive race to modernize fixed and mobile networks.
General Motors will begin rolling out a Google Gemini–powered conversational assistant across Buick, Chevrolet, Cadillac, and GMC in 2026, advancing the automaker’s in-cabin AI strategy and resetting expectations for voice-driven services in connected vehicles. GM plans to deliver a new assistant, built on Google’s Gemini family, as an over-the-air update via the Play Store to eligible OnStar-equipped vehicles from model year 2015 and newer. At launch, drivers should see more natural interactions: the assistant will understand free-form requests, maintain context across turns, and cope better with accents and phrasing. GM says the assistant will tap vehicle data to push maintenance alerts and route suggestions as well.

Frequently Asked Questions

What is network slicing in simple terms?
It’s the ability to carve a single physical 5G network into multiple virtual, independently configured slices, each with its own guaranteed performance characteristics for speed, latency, and reliability, so an operator can sell different service tiers off the same infrastructure rather than building separate networks for each use case. Each slice behaves, from the customer’s perspective, like a dedicated network tailored to their specific needs, even though it’s actually running on shared physical infrastructure alongside other slices serving completely different customers simultaneously. This is conceptually similar to how a single physical server can run multiple virtual machines that each behave like an independent computer, applied instead to network connectivity.
Is network slicing actually commercially available, or still experimental?
It has moved from pilot to early commercial deployment. Major carriers including T-Mobile, Verizon, Reliance Jio, and Singtel have launched commercial slicing-based offers for specific use cases, and telecom operators are described as the primary enablers of slicing technology, expected to hold roughly 62 percent of the market in 2026. That said, the industry consistently describes network slicing as being in the early stages of commercialization, meaning successful pilots are still being converted into broader, more scalable commercial offerings rather than slicing having become a fully mature, universally available product.
What’s a real-world example of network slicing in use?
Singtel partnered with Tencent Games to launch a dedicated low-latency network slice for cloud gaming in Singapore, described as the first nationwide gaming-specific network slice in the world, letting users play without downloading games or needing high-end hardware. Verizon Business launched a dedicated fixed wireless access slice for enterprise customers with guaranteed performance, extending slicing beyond mobile use cases into business broadband. Nokia and the UAE operator du were reportedly first in the industry to deploy autonomous network slicing, which automates the creation and management of slices rather than requiring extensive manual configuration.
Why does network slicing require 5G Standalone (SA)?
True dynamic, end-to-end network slicing depends on a 5G core built independently of 4G, known as 5G Standalone or SA architecture, since SA provides the flexibility and granular control needed to create, manage, and guarantee performance across multiple isolated virtual networks simultaneously. Non-standalone 5G, which still relies on a 4G core for certain control functions, can support some slicing-like capabilities but generally not with the same flexibility, automation, or end-to-end performance guarantees that SA enables. This is one of the main reasons operators have prioritized SA core upgrades specifically as a foundation for unlocking more advanced monetization opportunities like network slicing.
How big is the network slicing market expected to get?
Forecasts vary considerably depending on the specific market research firm, but most analyses put network slicing’s growth rate above 40 percent annually through the late 2020s, driven primarily by telecom operators monetizing differentiated connectivity for industries like healthcare, automotive, gaming, and manufacturing. Asia Pacific is generally described as leading global adoption given its large population base and diverse industrial use cases, while North America is often projected as the fastest-growing region given strong infrastructure investment. These projections should be treated with appropriate caution though, since the underlying market remains in an early commercialization phase.
Who actually manages and creates network slices in practice?
In practice, network slices are created and managed through orchestration software that translates a specific business requirement, such as guaranteed low latency for a particular customer’s application, into the actual technical configuration needed to deliver it across the relevant network infrastructure. This orchestration layer handles tasks like allocating the right combination of radio, transport, and core network resources to a given slice, monitoring whether it’s actually delivering its promised performance, and adjusting resource allocation dynamically as conditions change. More advanced, automated approaches, sometimes called autonomous network slicing, aim to handle much of this process automatically rather than requiring extensive manual configuration by network engineers each time.
What technical challenges have slowed broader network slicing adoption?
Several technical challenges have slowed broader adoption beyond the foundational requirement of upgrading to 5G Standalone infrastructure. Ensuring consistent performance guarantees across a slice that may span multiple different network domains, from radio access through transport and core, requires sophisticated end-to-end orchestration and assurance capabilities that have taken time to mature. Interoperability across different vendors’ equipment adds further complexity for operators running multi-vendor networks. There’s also a more fundamental business challenge: defining a manageable, scalable set of standard slice types that cover most customer needs, rather than requiring a fully custom-built slice for every individual customer, which would be operationally impractical at scale.
How is network slicing different from older approaches like VPNs or dedicated lines?
Older approaches like traditional VPNs or dedicated leased lines could provide a degree of network differentiation and security for specific customers, but they generally required separate, often physically distinct infrastructure or fixed, manually provisioned configurations that were slow and expensive to set up and change. Network slicing achieves a broadly similar goal, providing differentiated, somewhat isolated connectivity for a specific customer, but does so dynamically and through software, on top of shared underlying 5G infrastructure, without requiring separate physical infrastructure for each customer. This makes slicing considerably faster and cheaper to provision than traditional dedicated infrastructure approaches, while still providing meaningful performance guarantees and isolation.
TECKNEXUS PRIVATE NETWORKS
Congratulations to the 2026 Award Winners
Explore the Winners →

Partner Hubs

Telco AI Agent Leadership

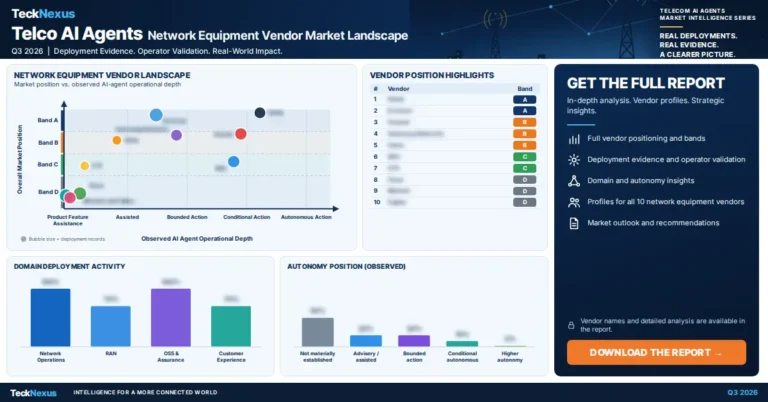
Telco AI Agent Leadership Landscape - Network Equipment Vendors
Network Equipment Vendor Report
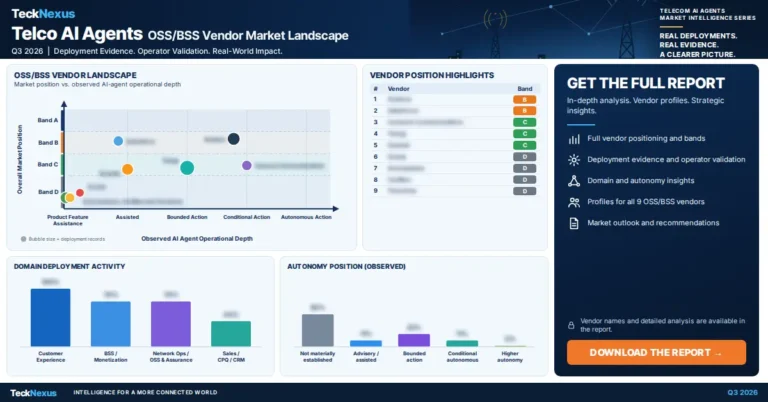
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
OSS/BSS Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
System Integrator Report
Scroll to Top