Private Network
Intelligence
Intelligence Journeys
Utilities Private Broadband Planning
AI Use Case Planning for Utilities

Spectrum

Defense, public safety, transport, and critical infrastructure need deterministic connectivity that moves with the mission. Traditional rollouts struggle with time-to-service, power, and backhaul constraints. Portable, “all-in-one” 5G modules help bridge that gap by putting the radio, core, and management closer to the edge, enabling local breakout, resilience, and consistent QoS. With 3GPP Release 16/17 features maturing and SA-first private networks becoming standard, demand is shifting from pilots to field-ready systems that can be mounted in vehicles, worn as backpacks, or staged in temporary zones.
Ericsson’s Microwave Outlook 2025 points to a backhaul market that will be almost evenly split between microwave and fiber by 2030, reshaping transport decisions for dense 5G and future 6G builds. Microwave already carries traffic for most live 5G networks worldwide, and a rising mix of E-band and emerging higher bands is closing the capacity gap with fiber for short- to medium-range links. For operators facing site densification, fiber lead times, and rising build costs, microwave provides a fast, resilient, and cost-optimized path to scale. E-band deployments are accelerating and overtaking legacy 38 GHz usage in several markets.
India’s mobile industry lobby is pushing for tariff corrections as network spending rises faster than service revenues. The Cellular Operators Association of India (COAI) says operators face a growing mismatch between capital outlays and tariff-led returns. By its estimate, the cumulative gap up to 2024 was already around Rs 10,000 crore and is widening in 2025 as data consumption accelerates. COAI argues that a handful of large traffic generators (LTGs) are responsible for most network load without directly contributing to network build costs. Expect a mix of tariff rationalization, plan redesign, and targeted capex as operators chase sustainable returns.
Verizon and AST SpaceMobile have advanced their partnership into a definitive commercial agreement to deliver space-based cellular coverage in the United States starting in 2026. The agreement enables Verizon subscribers to connect “when needed” to AST SpaceMobile’s low Earth orbit (LEO) satellites using standard, unmodified phones. AST says service will focus on coverage gaps across the continental U.S., and will extend Verizon’s premium 850 MHz low-band spectrum into remote areas. AST highlights successful space tests as proof points and positions the network for both commercial and government use.
India and the United Kingdom have launched the India–UK Connectivity and Innovation Centre to accelerate secure, AI-driven, and resilient telecom technologies over the next four years. The two governments committed an initial £24 million—roughly ₹250–₹282 crore depending on exchange rates—to fund applied research, joint testbeds, field trials, and standards contributions in emerging telecom domains. The investment concentrates on three pillars: AI in telecommunications, non-terrestrial networks (NTNs) for satellite and airborne connectivity, and telecoms cybersecurity with open, interoperable systems. The multi-year window aligns to the critical runway for 5G‑Advanced and early 6G experimentation.
After two years of decline, telecom equipment spending is edging back into positive territory with early signs of a broad-based rebound. Dell’Oro Group’s preliminary data indicates worldwide telecom equipment revenues across six tracked sectors rose 4% year over year in the first half of 2025, with markets outside China up a stronger 8%. The rebound was not limited to a single pocket of spend, but three areas led the gains: mobile core networks, optical transport, and service provider routers and switches. By contrast, RAN remains comparatively muted in many markets as 5G macro buildouts mature.
Verizon has entered a definitive agreement to acquire Starry, a fixed wireless broadband specialist focused on MDUs across Boston, New York, Los Angeles, Denver, and Washington, D.C. Starry brings nearly 100,000 broadband customers and an MDU-centric network architecture built around wideband millimeter-wave and hybrid fiber. Verizon said the move will support its ambition to double fixed wireless subscribers to roughly 8–9 million by 2028 and extend availability to about 90 million households. Starry’s in-market MDU know-how and neutral-host friendly building relationships give Verizon a fast path to scale in cities where it already owns substantial fiber backhaul and large 28/39 GHz mmWave holdings.
India Mobile Congress 2025 in New Delhi framed a clear ambition: scale domestic innovation, shape 6G, and turn telecom into a larger engine of GDP growth. Leaders underscored a whole-of-government approach, with multiple ministries backing IMC and the Department of Telecommunications and the Cellular Operators Association of India co-hosting. India’s telecom and digital sector is estimated to contribute roughly 12–14% to GDP today. Leaders at IMC projected this could reach about 20% by the mid-2030s if India scales advanced connectivity, software-led services, and domestic manufacturing. India’s 6G push was tied to a potential GDP uplift exceeding a trillion dollars by 2035.
India is poised to greenlight commercial satellite communication services once TRAI issues final pricing for satellite spectrum use and associated charges. The communications minister indicated the policy and licensing groundwork for satellite broadband is largely complete, with two GMPCS licenses issued and one additional letter of intent granted. The final trigger is the Telecom Regulatory Authority of India’s decision on spectrum pricing and usage fees for satcom bands. After that, operators can commence rollouts—initially for enterprise and backhaul, then for consumer broadband in selected markets. Bharti-backed Eutelsat OneWeb and Reliance Jio’s satellite unit are positioned to move early, with constellation capacity and gateways progressing.
At India Mobile Congress 2025, Jio framed a broad agenda that ties devices, networks, AI skills, and safety into a national-scale digital strategy. The message from Jio’s chairman was clear: India’s telecom flywheel now spans the full value chain, from semiconductors and device platforms to fraud management and the next wave of 6G research. Telcos are shifting from pure connectivity to platform businesses that bundle devices, cloud access, security, and AI services. JioPC is positioned as an “AI-ready” computer that turns any screen into a managed endpoint, delivered through a subscription model.
Sweden’s largest passenger rail operator SJ is consolidating its communications estate with Telia to accelerate 5G, IoT, and crisis-readiness across trains, stations, depots, and corporate operations. The partnership positions Telia as SJ’s primary provider for nationwide mobile and fixed communications, combining public 5G/LTE coverage with managed services that support day‑to‑day rail operations and passenger experience. For passengers, more consistent Wi‑Fi backhaul and seamless digital services are the immediate wins; for operations, the prize is reliability and faster recovery when incidents occur. European operators are scaling beyond discrete connectivity pilots toward platforms that unify onboard systems, station sensors, and back‑office analytics.
AT&T has gone live on Boldyn Networks’ neutral-host infrastructure in New York’s Joralemon Street tunnel, with G line tunnel segments next in the rollout. AT&T customers can now access 5G mobile service through the 1.1-mile (1.8 km) Joralemon Street tunnel, the oldest underwater subway tunnel in New York City, which links the 4/5 lines between Borough Hall in Brooklyn and Bowling Green in Manhattan. Subway connectivity has shifted from convenience to critical infrastructure for safety, accessibility, and productivity. AT&T’s first-mover status sets a competitive benchmark; other national carriers (Verizon and T‑Mobile) are expected to follow as on-boarding progresses across the system.

Partner Hubs

Telco AI Agent Leadership

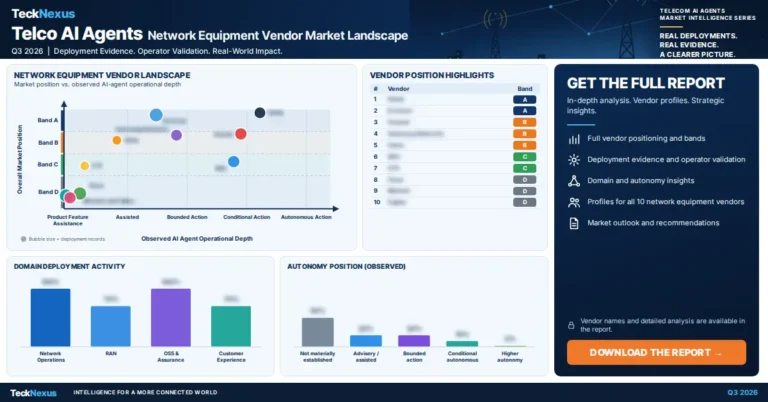
Telco AI Agent Leadership Landscape - Network Equipment Vendors
Network Equipment Vendor Report
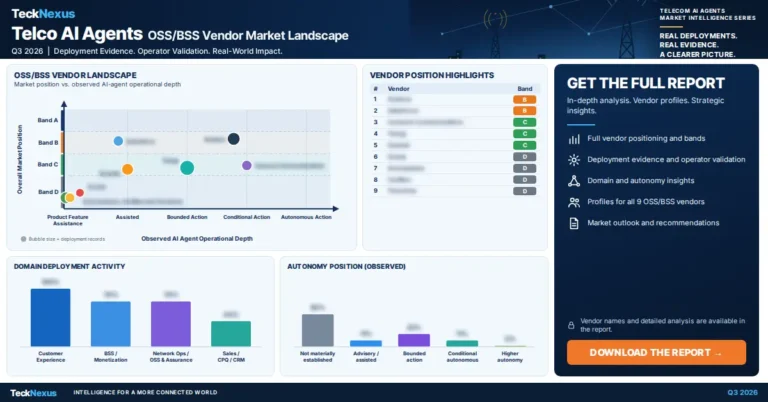
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
OSS/BSS Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
System Integrator Report
Scroll to Top