Private Network
Intelligence
Intelligence Journeys
Utilities Private Broadband Planning
AI Use Case Planning for Utilities

Spectrum

A fresh technical report from Broadband Forum details how a single outdoor 5G Fixed Wireless Access connection can deliver gigabit broadband to multiple apartments by reusing a building’s existing wiring. The document defines an architecture where one high-capacity 5G FWA modem—preferably operating on mmWave (3GPP FR2, roughly 24–40 GHz)—is installed on the roof or exterior of a multi‑dwelling unit (MDU) and then shared across many tenants. Instead of running new fiber to every unit, the approach leverages in‑place infrastructure such as coaxial cabling, twisted pair, or legacy telephone wiring to distribute service from a centralized point (attic, basement, or telecom closet) to apartments.
OECD data shows fixed and mobile broadband have shifted from build-out to scale-up, with fibre and 5G underpinning a new phase of digital infrastructure. Fixed broadband penetration across the OECD rose to 36.5 subscriptions per 100 inhabitants by end-2024, up from 32 in 2019, while the fibre share of fixed lines jumped from 28 percent to 47 percent over the same period. Gigabit-tier offers (≥1 Gbps) moved from 4 percent of subscriptions in 2019 to 19 percent in 2024, signaling both wider availability and growing appetite for very high throughput. On mobile, average monthly data consumption per subscription increased 2.5x—from 6 GB at end-2019 to 15 GB in 2024, aligned with more video, cloud, and AI-assisted applications shifting to handhelds and connected devices.
Orange has reached a non-binding agreement to acquire Lorca’s 50% stake in MasOrange for €4.25 billion in cash, aiming for sole control of Spain’s leading operator by customer base. The transaction would shift MasOrange from joint control (Orange and Lorca JVCO, owner of MásMóvil) to full ownership by Orange. Full control simplifies governance, accelerates synergy capture, and gives Orange greater flexibility in network investment, pricing, and product roadmap execution in Spain. Orange expects to sign a binding agreement before end-2025, subject to agreement on final terms. Completion is targeted for the first half of 2026, assuming standard merger-control review.
At SK AI Summit 2025, CEO Jung Jaihun outlined plans to expand the Ulsan artificial intelligence data center (AIDC) to 1GW-class capacity, stand up a nationwide trio of hubs (Gasan in the Seoul metro, Ulsan in the south, and a new southwest site), and take the model into Southeast Asia starting with Vietnam. The operator is also deepening technology collaborations with Amazon Web Services (AWS) on Edge AI and with NVIDIA on AI-RAN and a Manufacturing AI Cloud; it intends to buy more than 2,000 NVIDIA RTX PRO 6000 Blackwell GPUs and scale Korea’s largest GPU cluster, Haein, as core compute for industrial AI workloads.
TELUS has taken full ownership of TELUS Digital, a move designed to consolidate AI-powered customer experience, SaaS, and automation capabilities across its telecom, health, and agriculture businesses while unlocking material cost efficiencies. TELUS acquired all remaining TELUS Digital shares for US$4.50 per share, valuing the transaction at approximately US$539 million and issuing a small portion of TELUS common shares alongside cash to complete the deal; the entity will be delisted from the TSX and NYSE and cease public reporting. Management targets roughly US$150 million in annual efficiencies from automation, business simplification, and tighter cross-selling.
Vodafone named Dell Technologies a strategic infrastructure provider for a five-year Open RAN buildout across Europe, signaling a move from trials to scaled, automated 5G networks. Vodafone will expand one of Europe’s largest Open RAN footprints using Dell infrastructure as part of a multi-year radio access modernization program. Dell will supply its PowerEdge XR8000 series servers, including the XR8620t and the latest XR8720t with Intel Xeon 6 SoC. Vodafone also plans to adopt the Dell Telecom Infrastructure Automation Suite (DTIAS) to provide the Infrastructure Management Service within its Open RAN architecture, designed to automate Day 0/1/2 lifecycle operations for O-Cloud infrastructure.
Virgin Media O2 has struck a multi‑year agreement with Starlink Direct to Cell to deliver satellite‑to‑mobile service across rural UK not‑spots, positioning O2 as the first British operator to integrate Starlink’s constellation with licensed mobile spectrum. Branded as O2 Satellite, the service will initially support messaging and basic data on existing smartphones when users move beyond terrestrial signal. O2 is targeting landmass coverage beyond 95% within a year of launch, using Starlink’s 650+ low‑Earth orbit satellites to act as “cell sites in space.” Customer rollout is planned for early 2026, with pricing to follow and an extra monthly fee anticipated.
The FCC is circulating a proposal to reconfigure and auction a significant slice of upper C-Band spectrum, with a vote slated for November and a public comment period to shape the details. The draft notice of proposed rulemaking (NPRM) seeks input on auctioning up to 180 MHz of upper C-Band in the contiguous United States for licensed mobile broadband, with a floor of at least 100 MHz mandated by Congress for auction by July 2027. Commissioner Brendan Carr frames the objective as maximizing mid-band capacity for 5G and setting the stage for 6G, while maintaining aviation safety.
NVIDIA and Nokia unveiled a strategic partnership to deliver commercial AI-RAN products built on NVIDIA’s Aerial RAN Computer Pro (ARC-Pro) platform and Nokia’s RAN software portfolio, with NVIDIA committing a $1 billion equity investment in Nokia at approximately $6.01 per share, subject to customary closing conditions. The companies are targeting an AI-native RAN that runs both radio workloads and AI inference on a software-defined, accelerated platform, with a cumulative AI-RAN market opportunity that Omdia estimates will exceed $200 billion by 2030. ARC-Pro is positioned as a 6G-ready accelerated computing platform that couples connectivity, compute, and sensing, enabling upgrades from 5G-Advanced to 6G largely via software.
According to the latest Speedtest Intelligence findings from Ookla, the share of states where at least 60% of tested fixed-broadband users achieve the FCC’s 100 Mbps down/20 Mbps up benchmark rose sharply between late 2024 and the first half of 2025. That count climbed from 22 states (plus Washington, D.C.) to 38 states (plus D.C.), signaling faster last‑mile networks and better in-home performance for a sizable portion of U.S. households. Progress on equity also accelerated. In the first half of 2025, 33 states reduced the performance gap between urban and rural users—while 17 saw the gap widen versus the second half of 2024.
India has ceded the lowest-tariff crown to Bangladesh and Egypt, yet it still leads on value through generous allowances and low data unit costs. Indian base plans commonly include unlimited voice, whereas Bangladesh and Egypt restrict voice to roughly 100 and 70 minutes respectively at entry level. On data, incremental purchase economics are unusually attractive: an extra Rs 100 typically buys around 26 GB, or about Rs 4 per GB, keeping India among the most affordable data markets globally. Even after adjusting for purchasing power parity, India remains at the affordable end of global tariff rankings.
The partnership targets two fronts: mission-critical rail communications for operations and high-speed broadband for passengers. The scope includes deploying advanced 5G infrastructure, testing FRMCS-based use cases, and running a real-world trial on an existing SAR line to validate performance, integration, and safety requirements. An innovation and test lab will be established to accelerate solution validation, and SAR teams will be trained on FRMCS/5G rail technologies to build in-house capability. The partners will explore 5G Standalone capabilities for operational communications, including quality-of-service guarantees, redundancy, and resilience needed for rail. FRMCS-aligned services such as mission-critical push-to-talk/data/video (MCX), Railway Emergency Call, and secure staff communications will be validated for integration with signaling and control systems.

Partner Hubs

Telco AI Agent Leadership

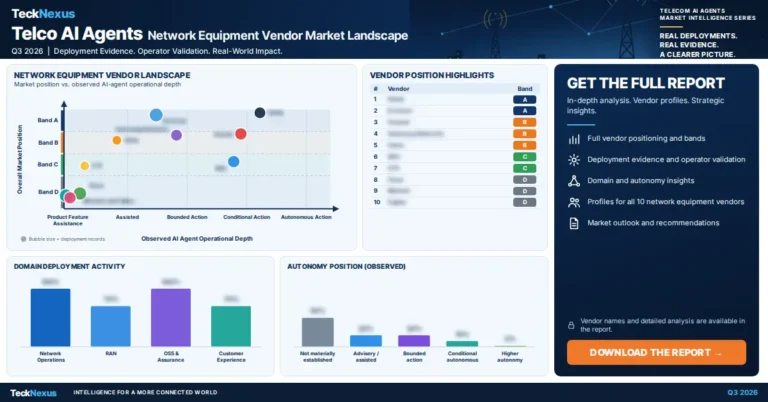
Telco AI Agent Leadership Landscape - Network Equipment Vendors
Network Equipment Vendor Report
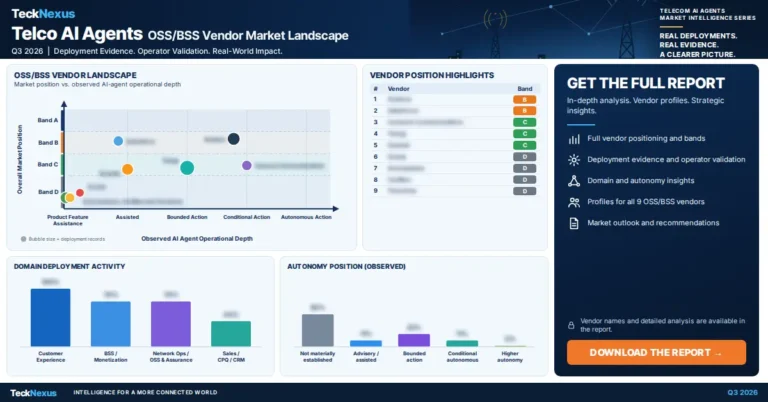
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
OSS/BSS Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
System Integrator Report
Scroll to Top