2027 Intelligence Programs

Broadband & FWA

Fixed wireless access (FWA) uses cellular networks — primarily 5G — to deliver home and business broadband as an alternative to cable and fiber. It has become one of 5G’s clearest commercial successes, letting operators monetize spectrum and capacity quickly, particularly where wired broadband is slow, costly, or unavailable. FWA’s economics depend on available mid-band capacity, device cost, and how aggressively operators price against fixed-line competitors. For operators, it offers fast revenue and subscriber growth; for enterprises and underserved regions, it offers viable connectivity without trenching fiber. This channel tracks FWA deployments, spectrum and capacity strategy, device developments, and the competitive dynamics between wireless and wired broadband, with analysis of where FWA delivers durable value and where capacity constraints limit its reach as adoption scales.

Verizon posted 55,000 postpaid phone net additions, a modest beat that underscores stabilizing consumer trends and stronger execution in premium plans and broadband cross-sell. The net add beat is small in absolute terms, but strategically important: it points to improving churn and a healthier mix of high-value subscribers after several quarters of intense promotional pressure. Management coupled the result with a constructive outlook characterized by service revenue resilience and disciplined capital intensity, hinting at a tighter or modestly raised full‑year guide. For a market still digesting 5G investment cycles, this steady footing matters more than splashy net‑add gains.
T-Mobile has inked two 50/50 fiber joint ventures to accelerate FTTP reach, add multi-gig capacity, and broaden its multi-access broadband portfolio. T-Mobile will partner with Oak Hill Capital to combine GoNetspeed and Greenlight Networks into a single platform and, in a separate JV, team with infrastructure investor Wren House to acquire i3 Broadband. Collectively, the platforms target about 1.8 million passings by the end of 2026—roughly 1.3 million from GoNetspeed/Greenlight and 500,000 from i3 Broadband—expanding T-Mobile’s ability to sell T-Fiber by T-Mobile alongside its leading 5G fixed wireless access (FWA) offering.
The broadband industry is intensifying its push to cut permitting delays on federal lands, with trade group USTelecom urging the Departments of Interior and Agriculture to adopt new White House guidance that would let agencies skip full environmental reviews for low-impact infrastructure projects. The guidance, issued by the Council on Environmental Quality in April, presses federal agencies to expand so-called categorical exclusions under NEPA — a shortcut the industry argues is essential to closing the digital divide in rural America.
Verizon’s role as Official Telecommunication Services Sponsor for FIFA World Cup 2026 and Official Tournament Supporter for FIFA Women’s World Cup 2027 elevates mega-event connectivity into a proving ground for 5G, fiber, FWA and broadcast at unprecedented scale. The World Cup concentrates extreme traffic densities, with each match expected to generate more than 50 terabytes of in-stadium data—an order of magnitude that forces operators to optimize spectrum, radio density and backhaul in tandem. Verizon’s capacity uplift—adding 5G spectrum to deliver an estimated 3x to 5x boost across all host stadiums—will benchmark real-world 5G ROI where venue, fan, and operational requirements converge.
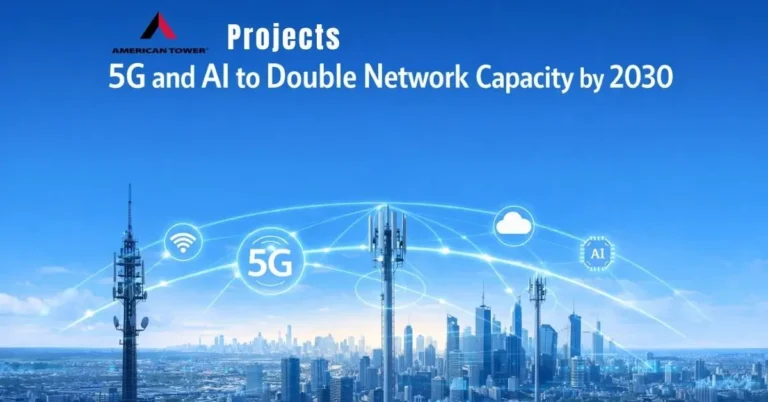
American Tower’s latest outlook puts a hard number on a trend most operators feel on the ground: the network needs to double by the end of the decade to absorb 5G, fixed wireless access, and AI-driven traffic. Mobile data growth remains the primary engine for new network investment. As 5G adoption scales and fixed wireless access expands, capacity pressure is shifting from coverage to throughput. The next leg comes from AI. New applications—from on-device inference to computer vision at the edge—demand more bandwidth, tighter latency, and stronger uplink. That profile is different from today’s downlink-heavy usage and will stress radios, backhaul, and site power.
Ericsson and Mistral AI are aligning telecom-grade engineering with customizable foundation models to push AI deeper into network operations and RAN automation. The pairing marries Mistral AI’s fast-evolving model stack with Ericsson’s domain expertise across radio, cloud-native networking, and service management. For European operators, it signals a path to AI capabilities that respect data residency, security, and compliance expectations under the EU AI Act without ceding control to generic, hyperscaler-led platforms. The outcome operators want is simple: measurable gains in performance, efficiency, and resiliency with governance baked in.
Ericsson has introduced an agentic rApp delivered as a cloud service on Amazon Web Services (AWS), aiming to speed operators’ shift from manual automation toward truly autonomous networks. By offering an “Agentic rApp as a Service” on AWS, Ericsson is packaging policy-driven and AI-assisted RAN optimization as a managed, cloud-delivered capability. Agentic capabilities bring reasoning, planning, and action-taking to operations. Running rApps on AWS offers elasticity, global reach, and faster release cadence. The goal: faster onboarding, lower integration friction, and a more repeatable path to closed-loop assurance across multi-vendor 4G/5G networks.
New guidance from the NTIA signals that BEAD-funded satellite providers, including SpaceX’s Starlink, must abide by standard program terms rather than negotiate bespoke carve-outs. An updated NTIA FAQ on subgranting makes clear that states cannot waive or dilute the statutory and programmatic requirements set out in the BEAD NOFO and subsequent guidance. Payments should be tied to objective milestones and verifiable outcomes, not front-loaded without proportional performance. Performance testing, reporting, and documentation must meet program and FCC-aligned standards; subgrantees cannot unilaterally narrow test samples or exclude locations to their advantage. The FAQ effectively answers whether BEAD can be implemented on a “vendor’s terms”: it cannot.
AT&T has closed its $5.75 billion cash deal to acquire Lumen’s consumer fiber business across 11 states, reshaping competitive dynamics in U.S. fiber-to-the-home and sharpening Lumen’s enterprise focus. The transaction moves more than 1 million fiber subscribers and over 4 million enabled fiber locations, including the Quantum Fiber brand and related consumer access networks, into AT&T’s portfolio. AT&T’s fiber home internet footprint now spans 32 states, adding major metros such as Denver, Seattle, and Salt Lake City where it can bring multi-gig services to market at scale.
The operators that control both dense fiber and performant 5G, and that package them coherently, will set the pace for the next telecom cycle. AT&T’s targets—more fiber passings, higher bundle attach, and measured wireless growth—put it squarely in the camp that sees integrated networks as the winning model. If the company executes on build cadence and cross-sell while keeping experience clean, expect continued share gains in fiber markets and a tougher environment for single-asset competitors. For buyers, the practical takeaway is to lean into converged sourcing now to lock in economics and resiliency as these footprints expand.
With the Union Budget around the corner, the Cellular Operators Association of India (COAI) is asking for a structural fix to spectrum pricing, statutory levies, and GST that is designed to restore sector health and accelerate digital infrastructure build-out. COAI’s agenda centers on spectrum affordability, regulatory levy rationalization, and GST reform to unlock liquidity frozen as input tax credit. COAI argues for spending the sizable unused corpus first, holding the DBN levy in abeyance, and trimming license fees to roughly 0.5–1% to cover administrative costs. Cutting GST on regulatory payments from 18% to 5% would reduce the pace of new ITC build-up and meaningfully ease liquidity pressure.

Frequently Asked Questions

What is FWA, and how is it different from home fiber or cable?
FWA delivers home or business internet over a cellular signal to a receiver and router installed at the property, rather than requiring a physical fiber-optic or coaxial cable line to be run from the provider’s network to that specific address. It essentially repurposes the same mobile network infrastructure carriers use for smartphones to also serve as last-mile home broadband. This is fundamentally different from fiber, which uses dedicated physical cabling carrying a guaranteed amount of bandwidth directly to one property, and from cable, which shares bandwidth across a neighborhood through coaxial lines. FWA’s performance is instead shared across everyone connected to the same nearby cell site, similar to how mobile phone performance can vary based on how many other devices are using that cell at once.
Is FWA actually replacing cable and fiber broadband?
In specific markets, FWA is genuinely displacing cable and fiber, particularly where running new physical cables is expensive or impractical. Fixed wireless connections grew by roughly 27 percent year over year as of late 2025, a notably fast growth rate for an established broadband category, and the share of FWA specifically offered over 5G, rather than older 4G infrastructure, jumped from 57 percent to 71 percent of providers in under a year, reflecting both rising consumer demand and improving network capability. That said, FWA growth has been strongest in markets where wired broadband options were previously limited or expensive, rather than uniformly displacing fiber in areas with well-established, competitively priced wired infrastructure.
Why do carriers like offering FWA?
FWA lets carriers monetize existing 5G spectrum and infrastructure investment for home broadband revenue without the substantial additional capital expense of physically trenching new fiber or cable lines to every home. Since the underlying radio network already exists to serve mobile phones, adding FWA customers represents largely incremental revenue on top of infrastructure the carrier has already built. Some carriers have begun offering FWA through dedicated network slices with guaranteed performance, allowing them to position FWA not just as a budget alternative to wired broadband but as a premium, business-grade connectivity tier with contractually guaranteed speed and reliability, opening additional revenue tiers beyond a single flat-rate consumer offering.
Is FWA fast enough to replace fiber for heavy users like gamers or remote workers?
Whether FWA is fast enough for heavy use depends heavily on local network conditions rather than being a fixed yes-or-no answer. On dense, well-provisioned mid-band 5G coverage, FWA performance can genuinely rival fiber for most household needs, including multiple simultaneous heavy users. However, because FWA performance is shared across everyone connected to the same nearby cell site, it tends to be more susceptible to congestion during peak hours, like early evening, than a dedicated fiber line. It’s also more sensitive to distance from the cell site, obstructions like trees or buildings, and weather, none of which meaningfully affect a buried fiber connection.
Where is FWA growing the fastest?
FWA growth has been fastest in markets with limited existing fixed broadband infrastructure, particularly rural and other underserved regions where extending fiber or cable to every home would require substantial new construction. In these areas, FWA offers a meaningfully faster and cheaper path to delivering broadband, leveraging cell towers that may already exist rather than trenching cable across long distances between sparsely located homes. Suburban areas with growing housing development but limited wired competition have also seen strong FWA adoption as a lower-priced alternative to existing cable monopolies. Dense urban areas have generally seen comparatively slower FWA growth, since wired competition tends to be stronger and cell capacity is shared among more customers.
How does FWA installation actually work for a new customer?
Installation for a typical residential FWA customer is generally simpler and faster than wired broadband installation, since it doesn’t require a technician to run new physical cabling. A customer usually receives a self-install kit containing a receiver and router, places it near a window or in a location with good signal reception based on a coverage-checking tool, and the device connects to the nearest compatible cell site automatically. Some providers offer optional professional installation, particularly for outdoor-mounted receivers intended to capture a stronger signal than an indoor unit could, which can meaningfully improve performance in marginal-coverage areas. Compared to a multi-week wait for a fiber technician to run new lines, FWA’s typically same-day or next-day self-install process is a practical advantage.
What are the main downsides of FWA compared to wired broadband?
FWA’s main limitations stem directly from its reliance on a shared, wireless signal rather than a dedicated physical line. Performance can fluctuate based on network congestion during peak hours, weather conditions, and physical obstructions between the receiver and the nearest cell site, none of which affect a buried fiber connection. Upload speeds are often noticeably lower than download speeds, which can matter for significant video conferencing or large file uploads. Data caps or deprioritization after a certain usage threshold are also more common on FWA plans than on many wired broadband plans, since FWA shares finite radio spectrum capacity across many customers in the same area, whereas a dedicated fiber line has no equivalent shared-capacity constraint.
How does network slicing change what FWA can offer business customers?
Network slicing allows carriers to offer FWA business customers a dedicated, performance-guaranteed connection rather than the standard, best-effort residential FWA experience, where performance can vary with overall network congestion. A business relying on FWA for critical operations, like point-of-sale systems or VoIP phone service, can be offered a network slice with contractually guaranteed minimum bandwidth and reliability, similar in concept to a dedicated business-grade wired connection, but delivered wirelessly. Verizon Business, for example, has launched a dedicated FWA network slice product specifically aimed at giving business customers more predictable, guaranteed performance. This lets carriers position FWA across a spectrum of tiers, from a budget consumer alternative up to a premium, guaranteed-performance business service.
Scroll to Top
TECKNEXUS MWC BARCELONA 2027
MWC27 EXECUTIVE INSIGHTS PROGRAM

Industry voices. Ideas that move.

SIX MAGAZINES. SIX BIG CONVERSATIONS.
EDITION 01 Networks as Platforms
EDITION 02 AI in the Real World
EDITION 03 The Intelligent Enterprise
EDITION 04 The Future of AI
EDITION 05 Securing the Digital Future
EDITION 06 The Next Frontier

Ways to Participate

Contributed Article Complimentary for eligible MWC sponsors
Sponsored Article & Executive Q&A
Executive Video Interview