Private Network
Intelligence
Intelligence Journeys
Utilities Private Broadband Planning
AI Use Case Planning for Utilities
https://www.ciena.com/insights/blog/2026/rls-hyper-rail-solving-the-challenges-of-multi-rail-photonics?campaign=X1994626&channel=media-direct-buy&medium=display&source=tecknexus&ad-type=&campaign-type=&term=&region=&lid=D3JLmZ

SpaceX

BlueBird 7 is slated to lift off in late February from Launch Complex 36 at Cape Canaveral Space Force Station on the New Glenn-3 mission. It is AST SpaceMobile’s first payload on New Glenn and the second satellite in its next-generation “Block 2” campaign, following BlueBird 6. BlueBird 7 mirrors BlueBird 6 and carries a deployable array of about 2,400 square feet—the company positions it as the largest commercial communications aperture in low Earth orbit. The design, backed by thousands of patent and patent-pending claims, is engineered to deliver peak downlink rates up to 120 Mbps directly to standard, unmodified devices for voice, data, and video.
New consumer research commissioned by Viasat and executed by GSMA Intelligence signals that non-terrestrial networks (NTN) are becoming a mainstream buying factor for mobile subscribers. The survey of more than 12,000 smartphone users across 12 countries finds persistent coverage gaps: over a third of respondents lose basic cellular service multiple times per month. That pain point is translating into intent. Roughly six in ten consumers say they would pay extra for satellite-enabled connectivity on their phones, and nearly half indicate they would switch operators if out‑of‑coverage service were included in their plan. On average, those willing to pay would accept a 5–7% uplift on their current monthly bill, with outliers such as India approaching a 9% premium.
New performance data shows U.S. WISPs are getting faster, but low‑Earth orbit players like Starlink are advancing just as quickly—and the competitive gap in rural markets is narrowing. Based on Speedtest Intelligence data from Q1 2021 to Q2 2025, eight of the larger WISPs—Starry, Resound Networks, Nextlink, Wisper Internet, Unwired Broadband, GeoLinks, Etheric Networks, and Rise Broadband—improved speeds, with download gains outpacing uploads. Starry led by a wide margin with a 202 Mbps median download in Q2 2025, followed by Resound at 99 Mbps and Nextlink at 68 Mbps; GeoLinks trailed at 23 Mbps. Crucially, only a minority of WISP users consistently achieve the FCC’s 100/20 Mbps fixed broadband benchmark.
Orange is moving to commercialize direct-to-device satellite connectivity in Europe with a carrier-branded SMS service that extends coverage beyond terrestrial reach. Orange will launch “Message Satellite,” an SMS and location-sharing service that lets smartphones connect directly to satellites when mobile or Wi‑Fi coverage is unavailable. The consumer launch in mainland France is slated for 11 December 2025, with professional and enterprise availability following in 2026. At launch, the service will be offered to Orange 5G and 5G+ customers using Google Pixel 9 or Pixel 10 devices, with additional handsets expected over time. Pricing is set at €5 per month after a six‑month free introductory period.
Amazon has moved its low Earth orbit broadband effort out of code-name mode and into a market-facing brand with strategic implications for telecom and enterprise buyers. Project Kuiper is now Amazon Leo, a direct reference to the low Earth orbit constellation underpinning the service. The rebrand signals a transition from R&D to commercial execution. Amazon reports more than 150 satellites in orbit today—roughly 153 by recent counts—following a string of successful launches and a completed prototype mission. The company says it will light up service as it adds coverage and capacity.
AST SpaceMobile is signaling a pivotal year ahead as it moves from demonstrations to commercial direct-to-device coverage with major operators and an aggressive launch schedule. The company’s plan to begin “intermittent nationwide” service in early 2026, followed by continuous coverage later in the year, is also a forcing function for device vendors, standards work, and MNO network integration. As AST scales to 45–60 BlueBird satellites by end-2026, pass frequency and overlap increase to support “continuous” service across the U.S., Europe, Japan, and other priority markets. AST reports over $3.2 billion in cash and liquidity.
A new joint plan from Vodafone and AST SpaceMobile aims to deliver satellite broadband directly to standard smartphones across Europe under a sovereign operational model. AST SpaceMobile has submitted plans through Germany for a space-based network designed to provide broadband directly to devices across Europe. Operations would run through SatCo, a Luxembourg-based joint venture with Vodafone announced earlier this year. The timing aligns with looming European spectrum decisions and intensifying competition in direct-to-device (D2D). S-band at 2 GHz is up for renewal across the region in 2027, and 700 MHz public protection and disaster relief (PPDR) frequencies are central to resilient communications strategy.
MTN has launched StarEdge Horizon, a Layer 2 service over SpaceX’s Starlink designed to move enterprise traffic on a private path to MTN points of presence (PoPs), bypassing the public internet and reducing latency, jitter, and operational complexity. The service extends a private Layer 2 domain from remote sites over Starlink into MTN regional PoPs, where enterprises can centralize internet egress, security, and policy. QoS and segmentation protect prioritized traffic, while multi-link redundancy reduces site-level downtime risks. By bringing a private Layer 2 architecture to Starlink, MTN’s StarEdge Horizon turns LEO from best-effort internet into a controllable enterprise transport.
A planned merger between Lynk Global and Omnispace aims to fuse spectrum assets, satellite technology, and SES’s multi-orbit infrastructure to scale 3GPP-compliant direct-to-device services worldwide. The combined company will pair Omnispace’s globally coordinated S-band holdings, about 60 MHz anchored by ITU filings and aligned to non-terrestrial network standards—with Lynk’s patented multi-spectrum D2D platform. SES, already an investor in both firms, will become a major strategic shareholder and provide access to its GEO and MEO assets and ground network to improve coverage, resiliency, and time-to-market. Lynk has already launched commercial messaging and alerting in small markets with a handful of LEO spacecraft.
New usage data shows AT&T subscribers are tapping into T-Mobile’s Starlink-powered T-Satellite more than expected, signaling a rapid shift in how carriers and customers think about direct-to-device connectivity. Speedtest intelligence indicates T-Mobile users account for the majority of direct-to-device (D2D) connections to Starlink, roughly six in ten overall and more than seven in ten among devices reporting active service at connection time. The surprise is AT&T’s footprint: about a third of observed connections come from AT&T subscribers, while Verizon’s share is minimal.
EchoStar has reset its strategy after regulator-driven spectrum sales, trading long-cycle infrastructure bets for an asset-light, capital-rich posture focused on satcom growth. Federal Communications Commission scrutiny over spectrum utilization forced EchoStar to accelerate decisions it had hoped to phase over time. Complaints from rivals spurred investigations into whether the company was meeting buildout and use obligations. Even if EchoStar prevailed in court, the process risked tying up key licenses and stalling its direct-to-device (D2D) ambitions. The company opted to monetize holdings and remove uncertainty rather than fight a prolonged, value-destructive battle.
SpaceX wants the FCC to count Starlink as “advanced” broadband in its annual Section 706 report, a move that could reshape funding, benchmarks, and competition in rural internet buildouts. In 2024, the agency set a 100/20 Mbps benchmark, added affordability and adoption metrics, and floated a long-term goal of 1 Gbps/500 Mbps. SpaceX argues that excluding LEO distorts the national picture. The company says Starlink serves more than 2 million U.S. subscribers and posts median peak-hour speeds near 200 Mbps today. Rural electric co-ops and community telcos counter that LEO networks remain capacity constrained and variable.
https://www.ciena.com/insights/blog/2026/rls-hyper-rail-solving-the-challenges-of-multi-rail-photonics?campaign=X1994626&channel=media-direct-buy&medium=display&source=tecknexus&ad-type=&campaign-type=&term=&region=&lid=D3JLmZ
TECKNEXUS PRIVATE NETWORKS
Congratulations to the 2026 Award Winners
Explore the Winners →

Partner Hubs

Telco AI Agent Leadership

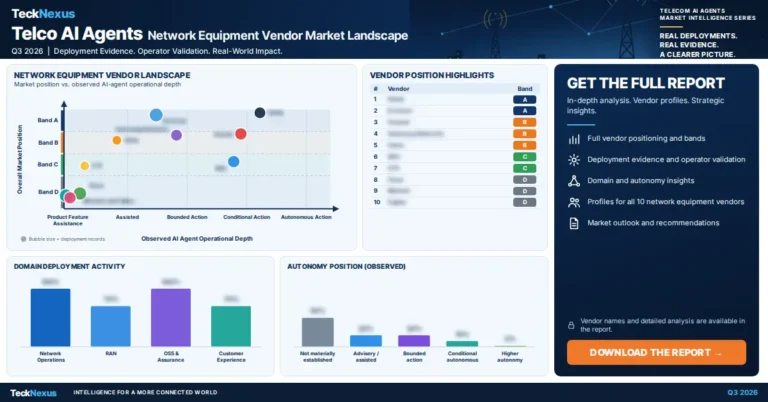
Telco AI Agent Leadership Landscape - Network Equipment Vendors
Network Equipment Vendor Report
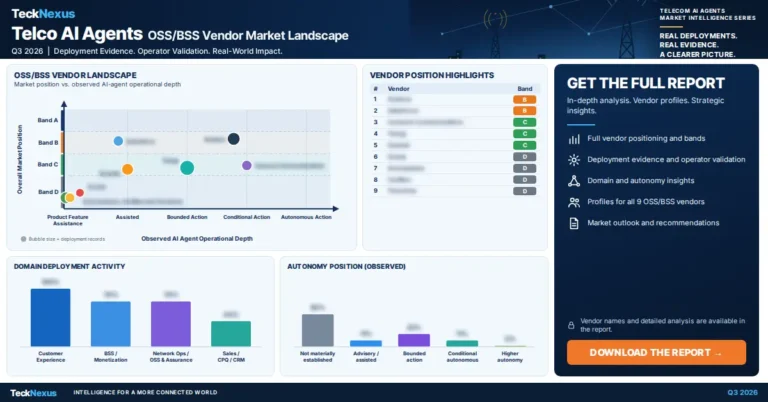
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
OSS/BSS Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
System Integrator Report
Scroll to Top