AI Agent Competitive
Intelligence
Intelligence Journeys
AI Use Cases for Utilities
Private Broadband for Utilities

Nvidia

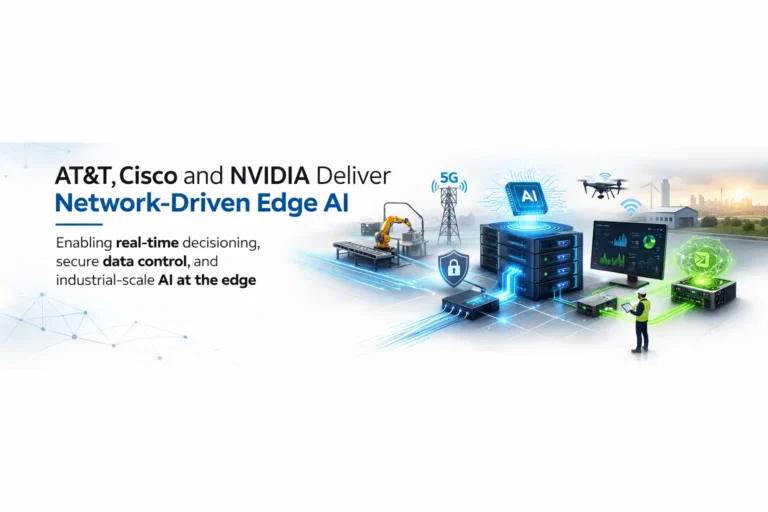
AT&T’s new collaboration with Cisco and NVIDIA signals a decisive shift from cloud-centric AI to network-driven edge intelligence for enterprise operations. Enterprises want real-time decisioning without shipping sensitive data to distant clouds, and operators need a scalable way to deliver it. By combining AT&T’s dedicated IoT core with Cisco’s mobility services platform and NVIDIA-powered AI infrastructure, the trio is packaging deterministic connectivity, near-device inference, and policy enforcement into a single, operator-grade platform. The promise: lower latency, tighter data control, and a path to production for AI at industrial scale.
Mobile World Congress 2026 showcased major developments across AI-native networks, enterprise private 5G, device innovation, and early 6G research. This recap highlights 50 key announcements and trends shaping the future of global connectivity.
TELUS Digital is using Mobile World Congress 2026 to move the AI-in-telecom conversation from pilots to proven production at scale. TELUS Digital reports processing more than two trillion tokens in 2025 through its Fuel iX generative AI platform for TELUS operations and customers. The portfolio spans AI for customer experience, application safety, and network modernization—built and battle-tested within TELUS before client rollout. The Network Design Services practice applies AI to planning and optimization while charting a path from legacy network stacks to cloud-native, automated environments.
India is moving to anchor a larger slice of global AI compute by pairing policy incentives with large-scale private capital and renewable power. New Delhi has outlined plans to attract more than $200 billion for AI infrastructure over the next two years, positioning the country as a production base for compute, data, and advanced applications rather than a pure consumer market. The policy stack aims to reduce friction for export-oriented AI services while widening access to shared compute for startups and enterprises. Adani Group plans to invest $100 billion through 2035 to build renewable-powered, AI-optimized data centers across India.
Anthropic’s latest financing round resets the competitive map for enterprise AI and raises the stakes for telecom, cloud, and large-scale IT buyers planning agentic automation. Anthropic closed a $30 billion Series G at a $380 billion post-money valuation, led by GIC and Coatue with participation from D. E. Shaw Ventures, Dragoneer, Founders Fund, ICONIQ, and MGX, alongside a broad cohort that includes Accel, General Catalyst, Jane Street, and the Qatar Investment Authority. The raise follows sustained commercial momentum and arrives as competitive intensity with OpenAI deepens, signaling that AI platform consolidation and scale economics will define the next phase of the market.
Deutsche Telekom and T-Systems have switched on a sovereign, NVIDIA-powered AI factory in Munich’s Tucherpark, positioning Germany as a serious contender in industrial AI infrastructure. The new facility brings nearly 10,000 NVIDIA Blackwell GPUs online, including DGX B200 systems and NVIDIA RTX Pro Server GPUs, delivering up to 0.5 exaFLOPS of AI compute for training, fine-tuning, and large-scale inference. Operated by T-Systems on German soil, the platform targets industry, research, startups, and the public sector with strict controls for data protection, security, and availability. Early customers include Agile Robots, which is combining vision, robotics, and foundation models, and PhysicsX, which applies AI to technical simulation.
An AI‑fueled land grab for advanced memory is squeezing supply for handsets, undercutting Qualcomm’s near‑term outlook even as end‑demand for premium Android devices improves. Memory suppliers are prioritizing high‑bandwidth memory (HBM) and DDR5 for AI accelerators and data center servers, diverting wafer capacity and capex away from mobile‑grade LPDDR5/5X and UFS storage. The result is a classic allocation cycle: supply chases the highest‑margin demand (HBM and enterprise SSDs), while downstream categories like smartphones and some edge devices face tighter availability and rising component costs. For Qualcomm, whose Snapdragon platforms anchor premium Android devices, the constraint limits upside volume and mix in the near term.
Amazon and Google currently lead the AI capex race, with Microsoft and Meta not far behind, and the prize is control over scarce compute, power, and network resources that define the next decade of cloud and AI services. For telecom and infrastructure players, the opportunity is immediate: deliver power-adjacent, fiber-rich, AI-ready capacity with speed and predictable SLAs. For enterprises, the mandate is pragmatic: secure capacity, design for portability across heterogeneous silicon, and enforce cost governance as inference scales. The winners will be those who pair aggressive buildouts with disciplined execution—turning record capex into durable platforms and customer outcomes.
Positron closed a $230 million Series B at a reported $1 billion valuation, co-led by Arena Private Wealth, Jump Trading, and Unless, with strategic capital from Qatar Investment Authority (QIA). Positron is focused on inference silicon rather than training, aligning with a market shift from building ever-larger foundation models to deploying them at scale. Its first-generation Atlas chip, manufactured in Arizona, is designed around high-speed memory throughput and is claimed to match Nvidia H100-class performance at under one-third the power for select inference workloads.
Amdocs is launching aOS, an agentic operating system for telecom, to move CSPs from AI pilots to production-scale, cross-domain automation. Amdocs’ aOS targets that gap with a multi-agent architecture that automates complex workflows while keeping humans in the loop for policy and final decisions. At the foundation is a “Cognitive Core” that manages telco-specific knowledge, agent libraries, and guardrails. aOS pricing will lean on outcome-based SLAs, tying spend to measurable business impact such as resolution rates, handle-time reductions, activation velocity, or assurance KPIs. aOS is Amdocs’ bid to make agentic AI the connective tissue of telco operations.
ElevenLabs raised $500 million in Series D funding at an $11 billion valuation, led by Sequoia Capital with continued participation from Andreessen Horowitz and ICONIQ, and new backing from Lightspeed, Evantic Capital and BOND alongside existing investors. The company says it has surpassed key ARR milestones and reported strong enterprise adoption across sectors through 2025, with telecom emerging as a priority vertical as operators seek to modernize legacy IVR and contact center stacks. Conversational agents can replace keypad IVRs with natural dialogue that recognizes intent, confirms identity, retrieves context and executes actions across channels.
The merger creates a $1.25 trillion private giant that fuses launch, satellites, and AI, but the strategic logic goes beyond orbiting data centers. SpaceX brings rockets, Starship scale, and the world’s largest NGSO broadband network via Starlink. xAI brings models, AI R&D, and a brand in the hottest capital market category. Together, they present a single story to investors: own the stack from compute to constellation to connectivity, on and off Earth. Consolidation gives Musk freedom to reallocate cash flows and simplifies the roadshow pitch.

Partner Hubs

Download content, access intelligence tools, and hear from executives.

Partner Events

  • FutureNet Asia 2026
  • Network X Vienna 2026
Scroll to Top