AI Agent Competitive
Intelligence
Intelligence Journeys
AI Use Cases for Utilities
Private Broadband for Utilities

Nvidia

July 2026's roundup: TSMC raises its Arizona commitment to $265 billion, Micron commits more than $250 billion to US DRAM manufacturing through 2035, SK hynix's $26.5 billion Nasdaq listing prices and begins trading, and hyperscaler data center and interconnect infrastructure keeps expanding from Alberta to Google's dark fiber network.
Apple's $30 billion Broadcom chip deal is the largest single commitment under its American Manufacturing Program to date - 15 billion+ US-made chips, a $1.5 billion Fort Collins expansion, and a supply agreement running through 2031. Here's what's actually in the deal and what it signals for wireless and telecom supply chains.
Telecom just crossed a line it spent years approaching carefully. AI agents are no longer confined to recommending fixes to network engineers — in a growing number of deployments, they're diagnosing faults and proposing remediations that a human simply signs off on, rather than performs. Nokia's work with Google Cloud is a clear marker of how far this has come: agents built on Gemini now sit inside Nokia's Assurance Center, and early results point to fault-resolution times cut by more than half, sometimes by as much as 80 percent. That's the part of the story getting the headlines. It's also, in a sense, the easy part... The harder question — the one the industry has mostly deferred — is what happens structurally once agents stop merely proposing and start acting, especially across more than one system at a time.
June 2026's roundup: agentic AI moves from pilot to operational core across telecom networks, satellite consolidates through Rocket Lab's $8B Iridium acquisition and SpaceX's $75B IPO, AI-RAN's GPU divide matures into shipping products, US spectrum auctions return after a four-year hiatus, and telecom M&A accelerates globally.
June 2026 showed agentic AI scaling from pilot to platform: industry-wide standards momentum, AI-RAN field trials from Nokia, Amdocs and KDDI, and fresh capital across data centers on three continents. This full roundup covers every deployment, partnership, funding round and governance move from the month, with tools to prioritise AI use cases and plan the network around them.
June 2026's roundup: SK Group, GS Group, and Naver unveil a $650 billion, 10-year AI infrastructure megaproject, Google shifts part of its TPU manufacturing from TSMC to Intel, Nvidia diversifies its HBM4 supply chain, and AI data center capacity keeps expanding into new global markets from Indonesia to Paraguay.
T-Mobile CTO John Saw's 'kinetic token' framework describes how Physical AI — robots, autonomous vehicles, industrial automation — changes what networks must do. The public telco debate that followed misses the most immediate implication: industrial private 5G networks are already, structurally, kinetic token infrastructure.
May 2026's roundup: AT&T, T-Mobile, and Verizon explore a joint satellite D2D venture, Ericsson tests GPU-free AI-RAN against Nvidia's GPU-embedded approach at the same two operators, 5G-Advanced sensing moves into live security deployments, and fiber capital both consolidates and expands.
May 2026's roundup: sovereign AI becomes a genuine global commercial category across nine countries, Anthropic's $65B raise reshapes enterprise AI partnerships, AI-RAN advances through Nvidia's direct investment in Nokia, and China's telecom giants launch a consumer AI token economy.
May 2026's roundup: the US government's 10% equity stake in Intel (now valued above $50B) underscores how strategic chip manufacturing has become, India and Vietnam both advance new chip fab and testing capacity, the AI chip supply chain keeps fragmenting beyond Nvidia, and Pixxel and Sarvam AI plan India's first orbital data center satellite.
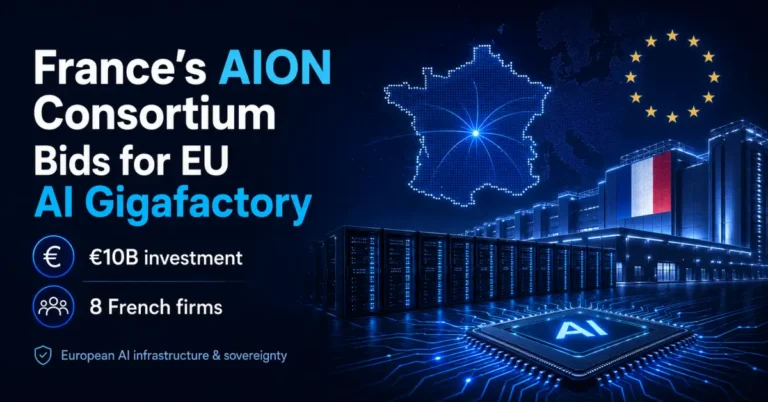
Eight French organisations — including Capgemini, Orange, EDF, Iliad and Scaleway — have formally united under the AION consortium to bid for an EU AI Gigafactory designation, backed by approximately €10 billion in committed investment. The bid targets EuroHPC's live call for proposals, closing June 23, 2026, and is designed to demonstrate France's ability to anchor the full AI value chain. For telecom and enterprise IT leaders, AION signals a structural repositioning of European operators as sovereign AI infrastructure enablers, not merely connectivity providers.
Runaway AI training demand is pushing data center fabrics past their limits, making optical networking the bottleneck to unlock GPU-scale performance and efficiency. Scale-up connects more GPUs within a box or across tightly coupled racks to form supernodes with ultra-low-latency fabrics. A new forecast from Goldman Sachs positions optical networking as the next mega-trend in AI infrastructure, with spend growing an order of magnitude as clusters densify. CPO—integrating optical engines with switch ASICs or accelerators—features prominently in the growth outlook. Expect a technology mix that also includes pluggable 800G/1.6T optics and emerging Linear Pluggable Optics (LPO) to reduce DSP power at short reaches.

Partner Hubs

Download content, access intelligence tools, and hear from executives.

Partner Events

  • FutureNet Asia 2026
  • Network X Vienna 2026
Scroll to Top