Private Network
Intelligence
Intelligence Journeys
Utilities Private Broadband Planning
AI Use Case Planning for Utilities

Mobility

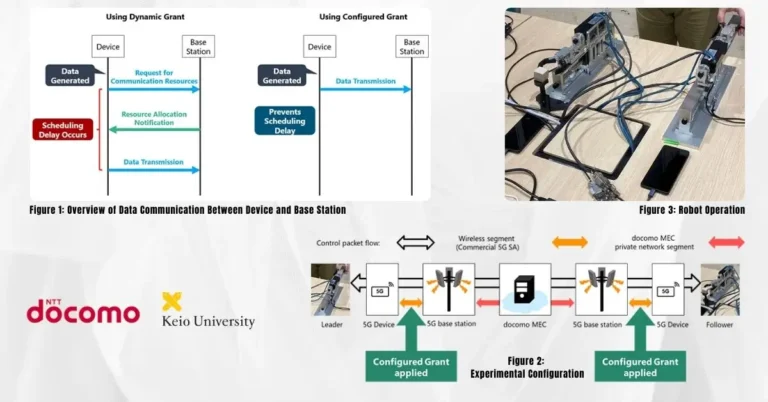
NTT DOCOMO and Keio University have validated that commercial 5G Standalone (SA) can stably support haptic-grade robot teleoperation using network slicing and configured grant—turning years of URLLC theory into practical results. By pairing 3GPP-configured grant scheduling with a low-latency slice and Keio’s Real Haptics technology, DOCOMO showed that public 5G SA can carry force and tactile feedback with the determinism required for safe, precise manipulation. The KPIs demonstrate material improvements in latency stability, force fidelity, and motion smoothness—indicators that the control loop is resilient enough for practical tasks.
NTT DATA’s private 5G rollout across 50 Cargill facilities signals that industrial connectivity is moving from pilot projects to standardized, multi-site execution. NTT DATA has deployed private 5G at Cargill manufacturing and processing locations worldwide—mostly in the United States with live sites in Europe—enabling a connected workforce, robotics, and edge AI across plants that are often too large and complex for conventional Wi‑Fi or wired networks to cover reliably. Manufacturers are consolidating on common digital platforms and need predictable, low-latency wireless for operational data, mobile human–machine interfaces, and autonomous systems; private 5G—built on 3GPP standards with SIM-based security and policy-based QoS—offers deterministic performance at scale where legacy networks struggle.
A new collaboration between GSMA Foundry and Singapore’s National University Health System (NUHS) aims to operationalize connected health at scale, with Ericsson and Singtel anchoring the 5G foundation. Healthcare digitization has moved from pilots to production, but most sites still struggle with deterministic connectivity, secure data exchange and workflow integration. The program combines private 5G with digital twin, XR, IoT and ambient AI to improve outcomes and operational resilience across care pathways. Early focus areas include 5G-enabled remote surgical assistance with ultra-reliable, low-latency links; immersive XR training and simulation that compress learning curves; autonomous and semi-autonomous robotics for logistics and point-of-care tasks; and AI-guided imaging such as vein visualization.
SK Telecom introduced ATHENA—an architecture grounded in AI-native operations, Zero Trust security, hyper-connectivity, openness, and cloud-native design—to guide mid- to long-term evolution across RAN, core, transport, and network data platforms. The operator positions “AI for network” and “network for AI” as dual tracks: the former embeds AI into decision loops for autonomous optimization, while the latter tunes the network fabric to serve AI workloads efficiently. SK Telecom will showcase related technologies at MWC Barcelona 2026, including AI agents for networks, AI-RAN for combined connectivity and compute, device-side AI for antenna tuning, and integrated sensing-and-communications.
Deutsche Telekom, Orange, Telefónica, TIM, and Vodafone unveiled a live, pan‑European edge federation at MWC 2026, marking a practical step toward an interoperable edge cloud that spans national borders. The five largest European operators demonstrated the European Edge Continuum, a federated edge capability now running in lab and pre‑production environments. The initiative provides a single entry point to deploy and manage applications across multiple operators’ edge nodes, with automated placement, security controls, and mobility‑aware continuity. The platform draws on components developed under the IPCEI‑CIS program backed by the EU’s NextGenerationEU funds, and is positioned for industrialization and commercial rollout next.
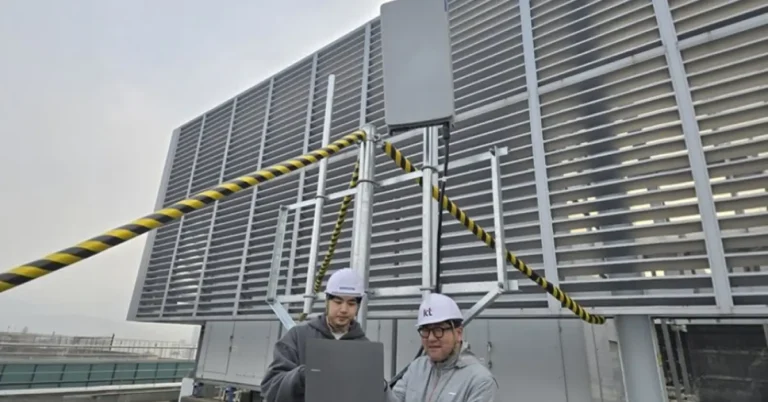
Samsung Electronics, working with KT Corporation and Keysight Technologies, has demonstrated 3 Gbps peak downlink in outdoor tests using an ultra‑dense antenna system and X‑MIMO in the 7 GHz band. The field trial took place at Samsung’s Seoul R&D Campus and pushed eight concurrent spatial streams from a base station to a single user device. The key enabler was a radio unit that packs roughly four times the antenna elements of today’s 5G massive MIMO gear into a similar physical footprint. Shorter wavelengths at 7 GHz make that density feasible without expanding the radio size.
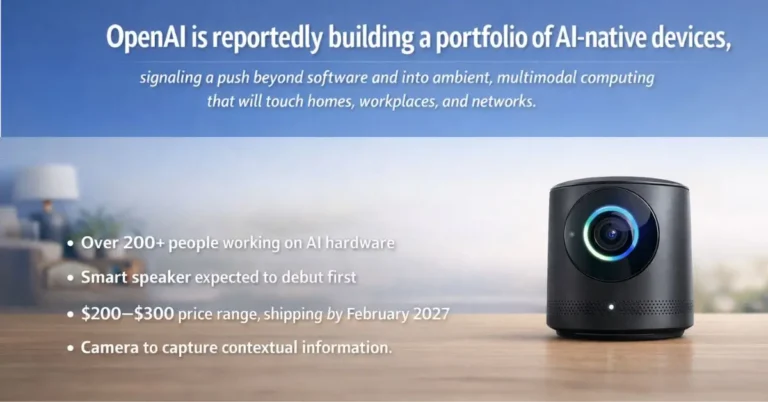
OpenAI is reportedly building a portfolio of AI-native devices, signaling a push beyond software and into ambient, multimodal computing that will touch homes, workplaces, and networks. Multiple reports indicate OpenAI has over 200 people developing a family of AI-enabled hardware, with a smart speaker expected to debut first. Early guidance points to a price in the $200–$300 range and a ship window no earlier than February 2027. The device is said to include a camera to capture contextual information about users and surroundings—an explicit bet on multimodal AI that fuses voice, vision, and environment for richer interactions.
Ericsson and Mistral AI are aligning telecom-grade engineering with customizable foundation models to push AI deeper into network operations and RAN automation. The pairing marries Mistral AI’s fast-evolving model stack with Ericsson’s domain expertise across radio, cloud-native networking, and service management. For European operators, it signals a path to AI capabilities that respect data residency, security, and compliance expectations under the EU AI Act without ceding control to generic, hyperscaler-led platforms. The outcome operators want is simple: measurable gains in performance, efficiency, and resiliency with governance baked in.
SpaceX’s anticipated 2026 IPO is not just a space-launch story; it is a capital and scale inflection that could reorder parts of the mobile and broadband value chain. Market chatter pegs SpaceX’s IPO valuation around the trillion-plus mark with a potential multibillion-dollar primary raise, a war chest that would dwarf most rivals’ balance sheets. For telecom, the same cash advantage accelerates Starlink’s network deployment, ground infrastructure, and device partnerships—compressing the window for incumbents to respond. Starlink reports more than 9,000 satellites in orbit, 9.2 million paying customers, and over $10 billion in annual revenue.
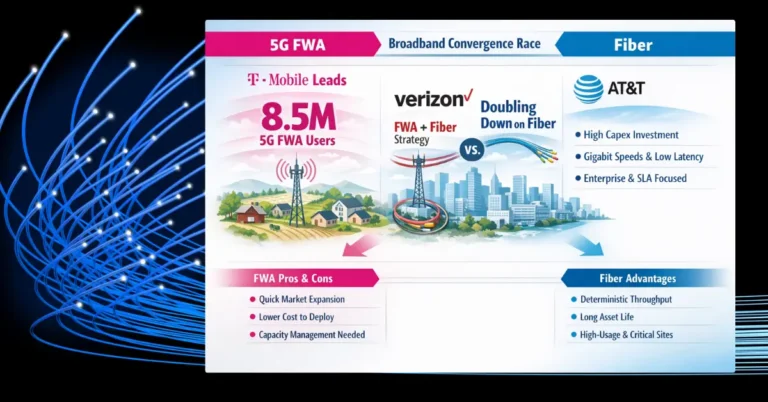
FWA is capex-light and fast to deploy, especially in mid-band-rich markets, which makes it ideal for quick share gains, addressable market expansion, and rural or underserved pockets. Its constraint is shared capacity: as mobile traffic grows, operators must manage prioritization, peak congestion, and plan mix to preserve experience. Fiber demands higher upfront capital but delivers deterministic throughput, low latency, and long asset life that underpins premium ARPU, enterprise SLAs, and wholesale opportunities. Expect operators to steer FWA toward segments with favorable traffic profiles and use fiber for high-usage clusters and enterprise-critical sites.
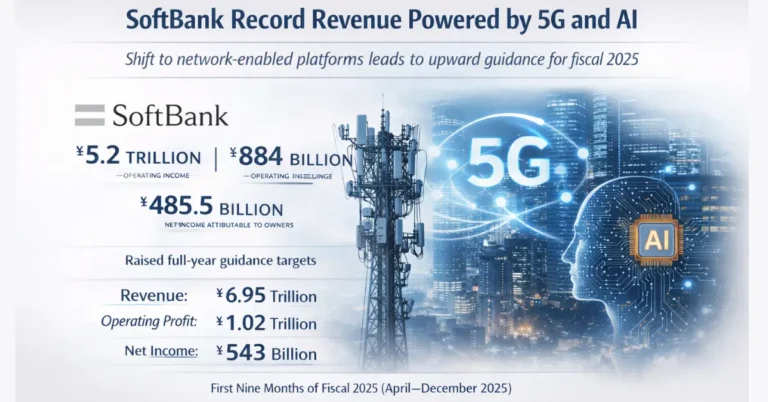
SoftBank Corp. delivered its strongest nine-month performance on record and lifted full-year guidance, underscoring a strategic shift from connectivity-only services to network-enabled platforms in AI, cloud, and edge. Through the first nine months of fiscal 2025 (April–December 2025), SoftBank reported revenue of ¥5.2 trillion, up 8% year over year, and operating income of ¥884 billion, also up 8%, with net income attributable to owners rising 11% to ¥485.5 billion. Management raised full-year targets to ¥6.95 trillion in revenue, ¥1.02 trillion in operating profit, and ¥543 billion in net income, signaling confidence heading into the March 31, 2026 year end.
Liberty Global and Google Cloud have signed a five-year agreement to deploy AI at scale across Liberty Global’s European footprint and to advance hybrid cloud, autonomous networks, and new go-to-market plays. The partnership spans roughly 80 million fixed and mobile connections across Liberty Global’s operating companies, including Virgin Media O2 in the UK, Telenet in Belgium, VodafoneZiggo in the Netherlands, Virgin Media in Ireland, and Sunrise in Switzerland. On the network side, the companies will co-develop AI-first programs aimed at reliability, security, scalability, and cost efficiency. Commercially, the parties will target SMEs with a joint portfolio that combines connectivity with cloud, cybersecurity, and AI services.
TECKNEXUS PRIVATE NETWORKS
Congratulations to the 2026 Award Winners
Explore the Winners →

Partner Hubs

Telco AI Agent Leadership

Telco AI Agent Leadership Landscape - Network Equipment Vendors
Network Equipment Vendor Report
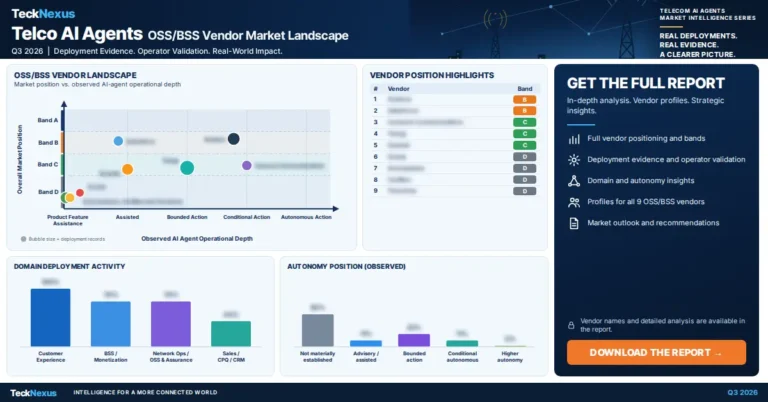
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
OSS/BSS Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
System Integrator Report
Scroll to Top