Private Network
Intelligence
Intelligence Journeys
Utilities Private Broadband Planning
AI Use Case Planning for Utilities

Investment

CEO Börje Ekholm indicated the company will keep trimming headcount after cutting roughly 5,000 positions over the last year. In Sweden, Ericsson has notified authorities and begun union talks that could affect about 1,600 roles, part of a multi‑year restructuring program. The move follows a 2023 plan to remove around 8,500 jobs worldwide—about 8% of its workforce—with further reductions last year in markets such as Spain and Canada. The rationale remains consistent: reset the cost base, protect profitability, and keep investment firepower for strategic bets amid a slower operator capex cycle.
Germany’s largest operator is pairing a go-to-market reset with a new in‑home sales model to lift fibre take-up, accelerate copper migration, and defend share in a tightening fixed broadband battle. Deutsche Telekom is moving beyond sidewalks and basements to deliver fibre all the way to the customer premise, including in-building cabling for multi-dwelling units on network level 4. After regional pilots in 2025, Deutsche Telekom is rolling out permanent local fibre consultancy teams to meet customers and property owners at the doorstep. Fibre is a considered purchase; informed on-site guidance shortens decision cycles and reduces fallout between order and activation.
The European Commission’s Digital Networks Act (DNA) is a sweeping proposal to harmonize telecom rules, catalyze next‑generation investment, and turn 27 national markets into a functional single market for connectivity. The DNA is timed to underpin an AI‑driven economy that depends on fiber, 5G/6G, and low‑latency cloud‑edge fabrics spanning borders. Longer licence durations and more flexible sharing are intended to reduce renewal risk and unlock investment in 5G densification and 6G prep. Mandatory national plans to phase out copper between 2030 and 2035 will free OPEX and energy, but require careful migration of regulated wholesale products, vulnerable users, and critical services.
More than 60% of U.S. households are now serviceable by fiber, with double‑digit millions of new homes added in 2025 as operators, co‑ops, and municipalities pushed into suburban and rural areas. Median build benchmarks show underground construction around $18 per foot and aerial around $8 per foot, based on a broad sample of operator and contractor data across dozens of states. Most builders expect costs to rise again in 2026, and many anticipate longer schedules. Labor and materials remain the top pressure points, while permitting and make‑ready feature more prominently as networks stretch into harder‑to‑build pockets.
Across roughly 2,000 decision-makers in telecom, data center, and large enterprises, a strong majority doubts that existing infrastructure will keep up with AI’s next wave. In the US, most respondents expect network buildouts to lag AI investment and call out near-term priorities such as optimizing bidirectional data flows, expanding fiber capacity, enabling real-time training feedback, and placing low-latency compute closer to users. In Europe, most enterprise leaders say current networks are not ready for broad AI adoption; many already report latency, throughput, and resiliency pain as data demands rise. The common thread is clear: without accelerated modernization, networks risk becoming the bottleneck that constrains AI outcomes.
Orange has signed a binding agreement to buy Lorca’s remaining 50% stake in MasOrange for 4.25 billion euros in cash, targeting completion in the first half of 2026 subject to customary approvals. The agreement transitions MasOrange from a 50:50 joint venture to a wholly owned subsidiary of Orange, consolidating governance and simplifying decision-making across mobile, fixed, and converged operations in Spain. At closing, MasOrange is expected to be fully consolidated into Orange’s accounts, including MasOrange debt that Orange plans to refinance at or after completion, providing flexibility to optimize the capital structure and cost of capital.
The latest 3GPP cycle consolidates 5G-Advanced (Release 18), sets the agenda for Release 19, and frames early 6G studies, with direct implications for operator investment, enterprise use cases, and vendor roadmaps. Release 18, the first phase of 5G-Advanced, is moving from standards completion into implementation, bringing carrier-grade enhancements in spectral efficiency, energy savings, and mobility performance. Release 19 now builds on these foundations, prioritizing further RAN efficiency, XR and video delivery at scale, richer analytics/exposure in the core (NWDAF, NEF/CAPIF), and enterprise-grade reliability across private and public networks.
Paramount Skydance launched a hostile, board-bypassing tender offer to acquire all of Warner Bros. Discovery (WBD) at $30 per share, valuing the company at about $108 billion on an enterprise basis. The bid arrives days after WBD agreed to sell its studio and streaming assets—including Warner Bros. studios, HBO, and Max—to Netflix in a cash-and-stock deal valued at roughly $72 billion. Paramount’s pitch: more cash, full-company certainty, and a quicker path to close. The outcome will determine control of premium U.S. content, set the pace of streaming consolidation, and ripple into network traffic, advertising markets, and device and distribution partnerships.
3GPP has become the organizing framework for how public safety, utilities, transportation and enterprise security adopt LTE/5G for mission-critical communications (MCX). For mission-critical users, 3GPP’s scope includes capabilities such as push-to-talk, data and video designed for high availability, priority, pre-emption and end-to-end security. For agencies and enterprises, the value of 3GPP is practical: it lowers integration risk, clarifies feature expectations and aligns multi-year investment roadmaps. Standards are the foundation; operational reliability is the measure of success. 3GPP is the baseline for resilient, interoperable operations.
Disney will invest $1 billion in OpenAI and become Sora’s first major content licensing partner, enabling fans to generate and share short videos that feature more than 200 characters and environments from Disney, Pixar, Marvel, and Star Wars. The agreement spans three years, excludes actor likenesses and voices, and extends to ChatGPT Images for IP‑compliant image generation. Disney will adopt OpenAI APIs across products and operations, including features for Disney+ and employee productivity, and may showcase select user creations on its streaming service. This agreement formalizes licensed synthetic media at scale and accelerates the convergence of UGC, premium IP, and AI tooling.
Reliance Jio’s path to a mid-2026 IPO is increasingly intertwined with the timing and magnitude of India’s next mobile tariff hike. Domestic brokers argue Jio has a tactical reason to push back on near-term tariff increases: hikes tend to accelerate Bharti Airtel’s revenue market share (RMS) gains more than Jio’s, narrowing the lead at the worst possible time for an IPO. Airtel has been the key beneficiary of previous price actions, chipping away at Jio’s RMS advantage by almost two percentage points since mid-2024. On current assumptions, Jio is informally pegged around $153 billion, implying an EV/EBITDA multiple near the low teens.
TECKNEXUS PRIVATE NETWORKS
Congratulations to the 2026 Award Winners
Explore the Winners →

Partner Hubs

Telco AI Agent Leadership

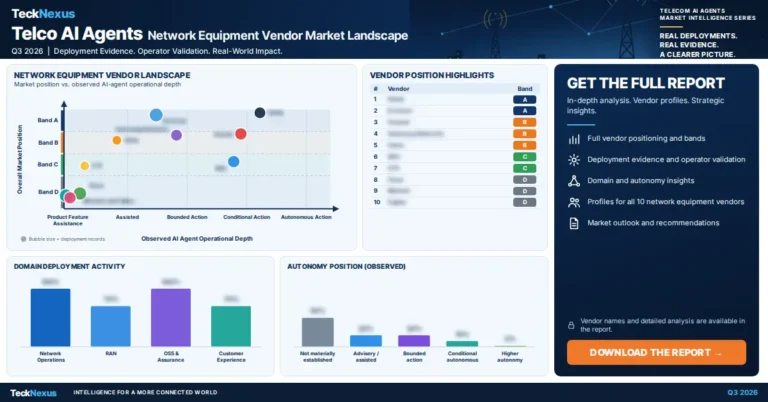
Telco AI Agent Leadership Landscape - Network Equipment Vendors
Network Equipment Vendor Report
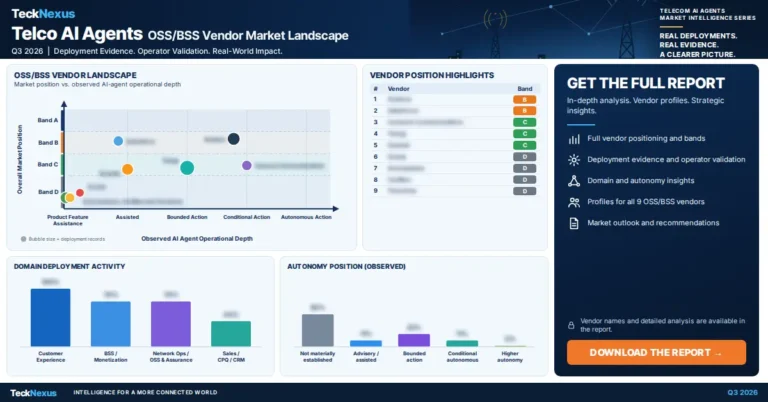
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
OSS/BSS Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
System Integrator Report
Scroll to Top