Private Network
Intelligence
Intelligence Journeys
Utilities Private Broadband Planning
AI Use Case Planning for Utilities

Eutelsat OneWeb

SpaceX is evolving from a rocket company into a vertically integrated infrastructure conglomerate with direct implications for satellite connectivity, defense communications, AI, and enterprise network strategy. With a planned $2 trillion Nasdaq IPO targeting $75 billion in capital, over $6 billion in cumulative U.S. government contracts, and Starlink expanding as a tier-one connectivity layer, SpaceX is positioning itself as a direct competitor in telecom markets. Telecom operators and enterprise IT leaders must stress-test their non-terrestrial network strategies now, before IPO capital accelerates SpaceX's competitive timelines across every market it touches.
Live Streamed on Mon, 2 Mar at 16:00 - 17:00 CET

As the foundations of global order shift, strategic sovereignty is emerging as a defining challenge for governments and industries. This session brings together leaders shaping Europe’s industrial and digital landscape to reflect on how the region can strengthen its autonomy while remaining open, innovative and globally engaged. With rising geopolitical risk and intensifying technological rivalry, the ability to control, govern and secure essential capabilities has never been more important. We examine how Europe can scale innovation, modernise essential infrastructure and reinforce critical industries. Strategic investment and firm political commitment will be crucial to shaping a more sovereign, competitive and resilient future.
SpaceX’s anticipated 2026 IPO is not just a space-launch story; it is a capital and scale inflection that could reorder parts of the mobile and broadband value chain. Market chatter pegs SpaceX’s IPO valuation around the trillion-plus mark with a potential multibillion-dollar primary raise, a war chest that would dwarf most rivals’ balance sheets. For telecom, the same cash advantage accelerates Starlink’s network deployment, ground infrastructure, and device partnerships—compressing the window for incumbents to respond. Starlink reports more than 9,000 satellites in orbit, 9.2 million paying customers, and over $10 billion in annual revenue.
TeraWave combines 5,280 low Earth orbit satellites with 128 medium Earth orbit satellites—5,408 spacecraft in total—tied together via optical inter-satellite links. The design targets global coverage with two distinct performance tiers: up to 144 Gbps symmetrical RF links per enterprise customer using Q/V-band in LEO, and optical links in MEO delivering up to 6 Tbps for high-throughput trunking between hubs. Blue Origin positions the service for point-to-point private links and enterprise-grade internet access, with an initial target of up to 100,000 customers. The company intends to launch on its own New Glenn vehicles and leverage reusable engines to scale deployment.
New consumer research commissioned by Viasat and executed by GSMA Intelligence signals that non-terrestrial networks (NTN) are becoming a mainstream buying factor for mobile subscribers. The survey of more than 12,000 smartphone users across 12 countries finds persistent coverage gaps: over a third of respondents lose basic cellular service multiple times per month. That pain point is translating into intent. Roughly six in ten consumers say they would pay extra for satellite-enabled connectivity on their phones, and nearly half indicate they would switch operators if out‑of‑coverage service were included in their plan. On average, those willing to pay would accept a 5–7% uplift on their current monthly bill, with outliers such as India approaching a 9% premium.
Scroll to Top
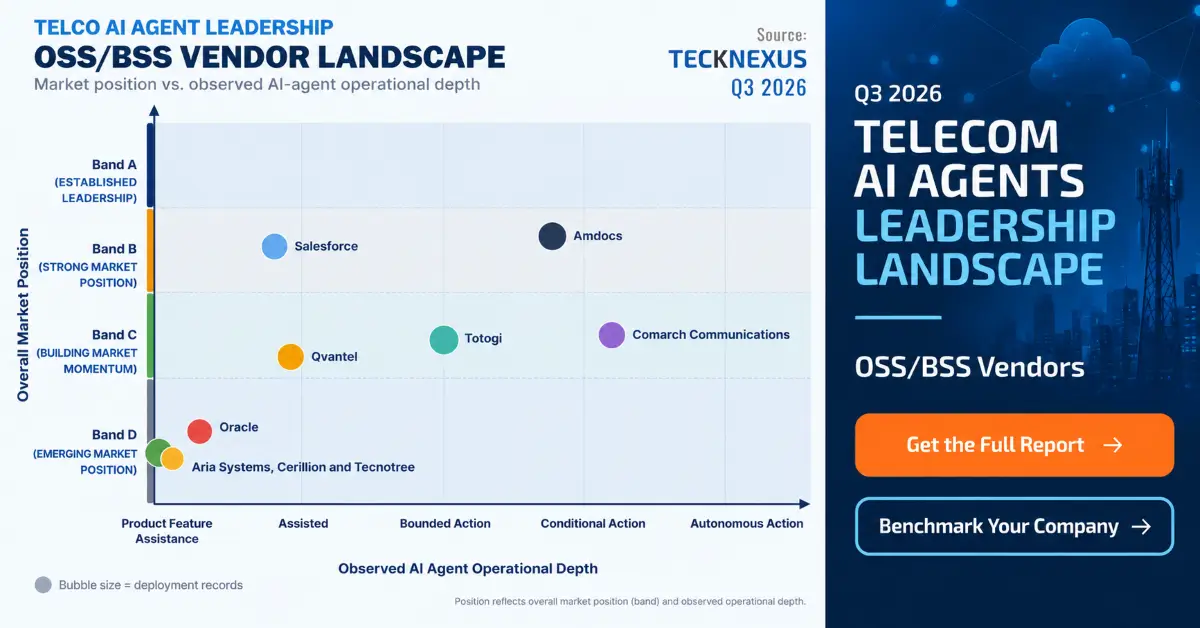
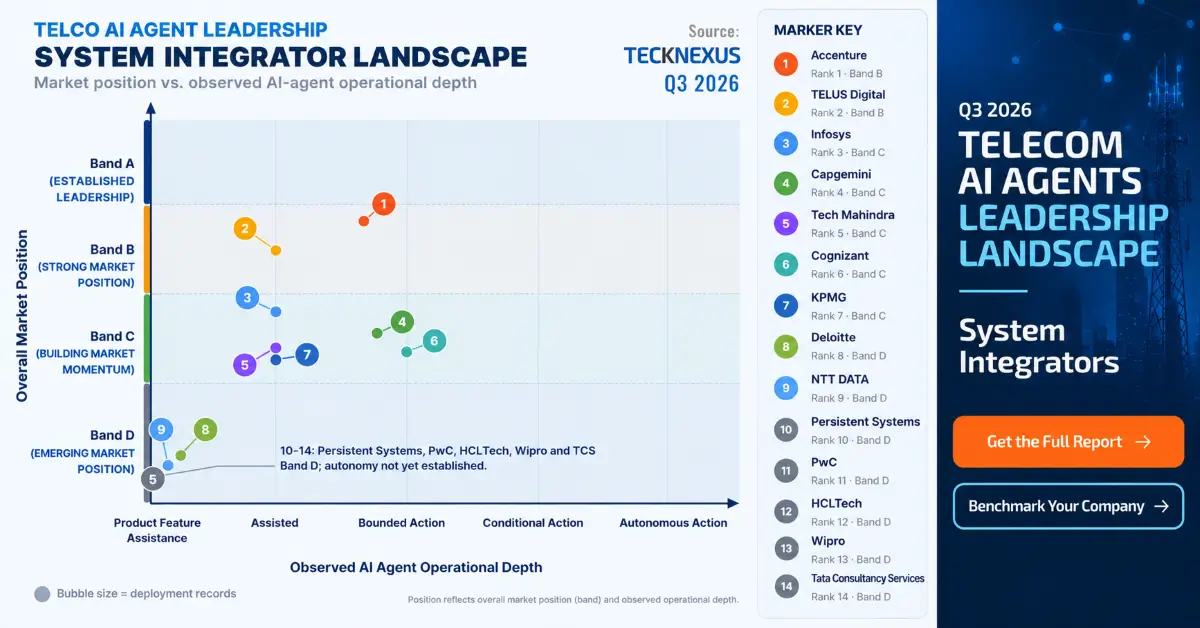
TELECOM AI AGENTS Q3 2026 · Available Now

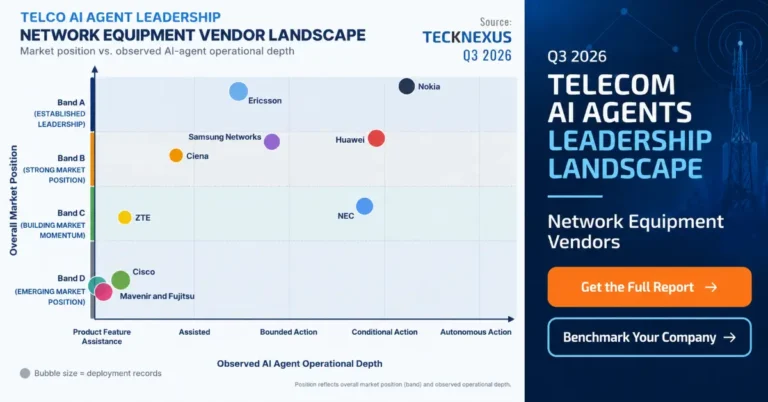
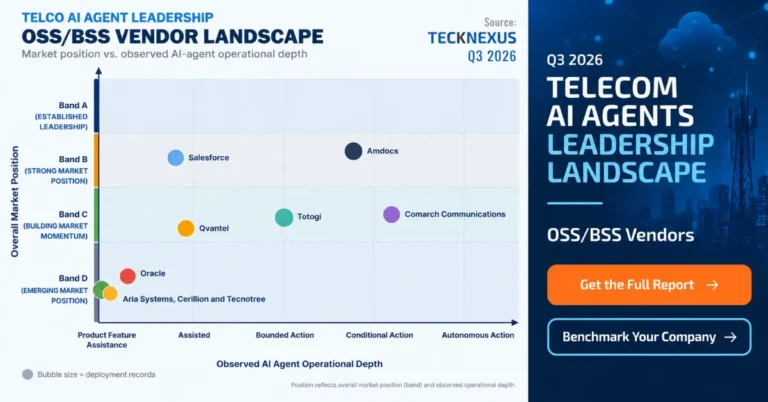
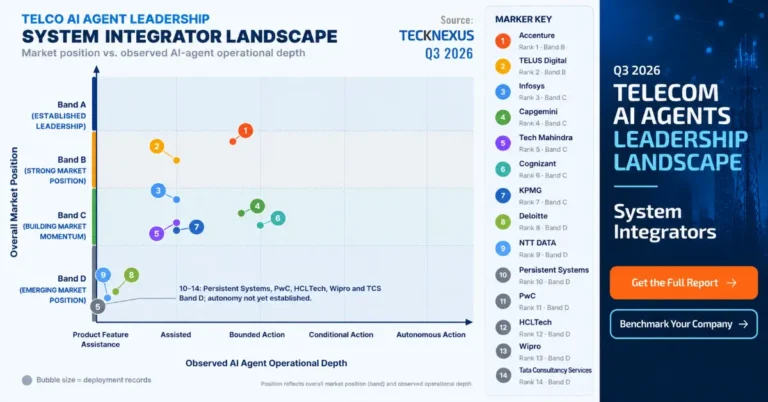
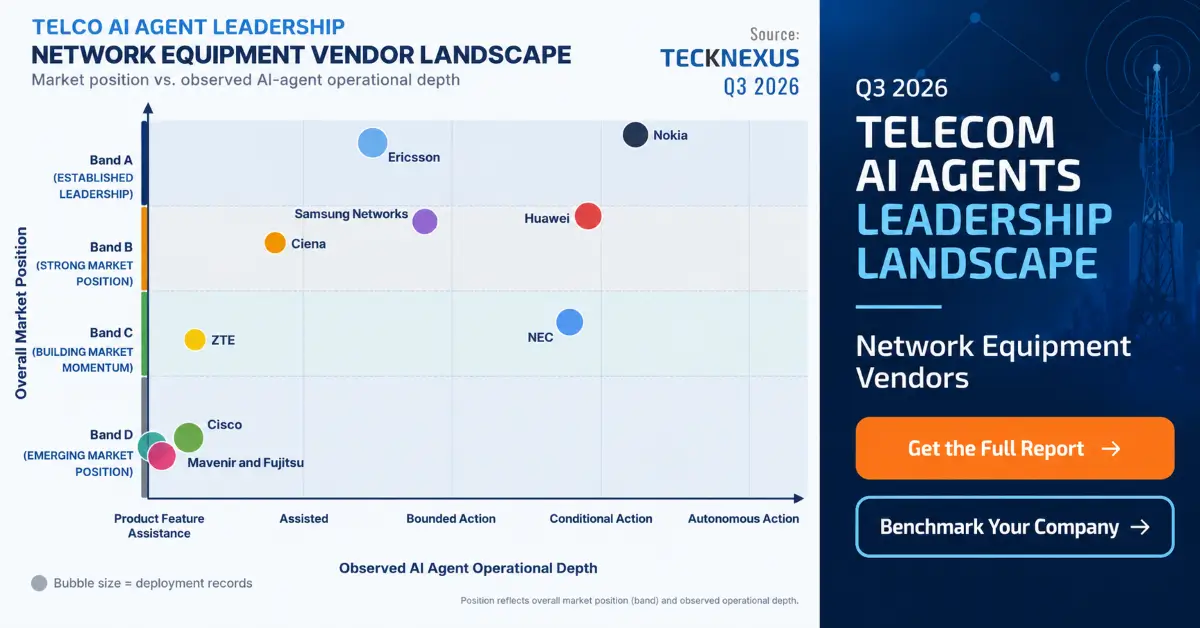
Explore the Telecom AI Agents Leadership Landscapes

Explore market positioning, deployment momentum and operator validation across the telecom AI agent ecosystem.
Explore Leadership Landscapes
Independent · Evidence-based · Telecom-focused