Private Network
Intelligence
Intelligence Journeys
Utilities Private Broadband Planning
AI Use Case Planning for Utilities

5G

5G is the fifth generation of cellular technology and the current global standard, succeeding 4G LTE with faster speeds, lower latency, and the capacity to connect far more devices per cell. Standardized by 3GPP from around 2017 and launched commercially in 2019, it has become the dominant connectivity technology across most major markets. 5G spans low-, mid-, and high-band (mmWave) spectrum and two architectures — non-standalone, which runs on a 4G core, and standalone, which unlocks network slicing and the lowest latency. The standard continues to evolve through 5G-Advanced, adding AI-native management and tighter satellite integration. For enterprises and operators, the questions have shifted from coverage to monetization, private deployments, and standalone migration. This channel tracks 5G developments across vendors, operators, and enterprise verticals, with analysis and decision tools for teams evaluating real deployments.

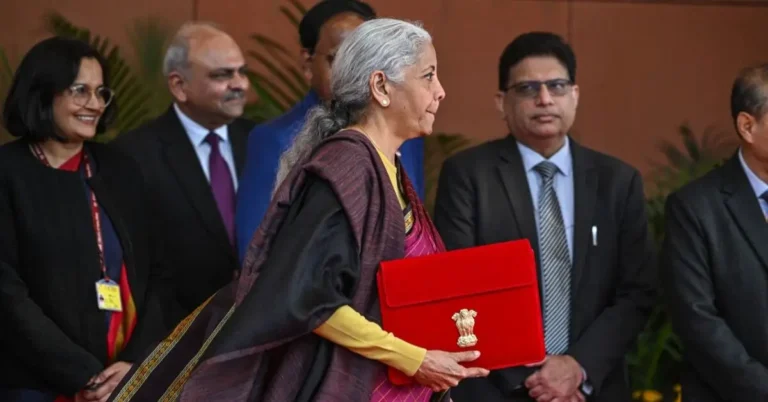
With the Union Budget around the corner, the Cellular Operators Association of India (COAI) is asking for a structural fix to spectrum pricing, statutory levies, and GST that is designed to restore sector health and accelerate digital infrastructure build-out. COAI’s agenda centers on spectrum affordability, regulatory levy rationalization, and GST reform to unlock liquidity frozen as input tax credit. COAI argues for spending the sizable unused corpus first, holding the DBN levy in abeyance, and trimming license fees to roughly 0.5–1% to cover administrative costs. Cutting GST on regulatory payments from 18% to 5% would reduce the pace of new ITC build-up and meaningfully ease liquidity pressure.
The next wave of digital transformation will be defined by AI workloads riding on cloud and edge infrastructure over 5G networks, and that shift will change how networks are built, monetized, and secured. Generative and agentic AI move more compute into the network, creating persistent, uplink-heavy, low-latency flows rather than the mostly downlink, best-effort traffic of the smartphone era. Video from cameras, glasses, and sensors feeds models at the edge and in the cloud; results return in milliseconds to people and machines. That means tighter latency budgets, deterministic jitter control, and stronger guarantees for both throughput and reliability.
New Delhi has unveiled a sweeping tax holiday to capture the next wave of AI and cloud build-outs, positioning India as a long-term base for exporting compute. Foreign providers that deliver cloud and data center services to customers outside India will pay zero corporate tax on those revenues through 2047, provided workloads run from facilities in India. The budget also introduces a 15% cost-plus safe harbor for Indian data center units serving related foreign parties, simplifying transfer pricing for global delivery hubs. For cloud providers, it strengthens the business case to place GPU clusters, storage, and interconnect in India to serve overseas demand, not just local workloads.
NTT DATA and AWS have signed a multi-year strategic collaboration aimed at accelerating cloud modernization and responsible agentic AI adoption, with clear implications for APAC enterprises and telecoms. The agreement expands joint go-to-market and delivery across four pillars: AI-driven cloud transformation, industry cloud solutions, AI-enabled managed services and customer experience, and sovereign cloud for regulated workloads. NTT DATA has created a dedicated AWS Business Group with close to 11,000 AWS-certified experts and plans to certify nearly 10,000 more in three years. APAC boards want measurable AI outcomes, but legacy estates, data fragmentation, and compliance obligations slow progress.
Apple’s purchase of Israeli start-up Q.ai accelerates its shift toward multimodal, audio-first wearables and tighter on-device AI. Apple acquired Q.ai, a Tel Aviv-based AI company operating in stealth since 2022, in a transaction reported around $2 billion, making it Apple’s second-largest acquisition after Beats. The move lands as Apple pushes a broader AI refresh across devices and services, including a reworked Siri due next month and a reported integration of Google’s Gemini into Apple Foundation Models. The core value is a human-computer interface designed to reduce friction between intent and AI execution. This enables “silent speech” and context awareness without overt voice commands or touch.
Verizon exits 2025 with standout subscriber growth and a leaner 2026 investment plan that shifts dollars from network build to integration, efficiency and customer retention. Verizon posted more than 1 million net additions in the fourth quarter, including 616,000 postpaid phone net adds—the best showing since 2019—and 372,000 broadband net adds driven by 319,000 fixed wireless access (FWA) additions and the strongest Fios Internet quarter since 2020. After years of 5G coverage build, Verizon is pivoting to densification, fiber integration and operating efficiency, allowing capex to step down without undermining network competitiveness. Capital will concentrate on fiber-led convergence, FWA capacity, and experience-centric technologies that reduce churn and support revenue quality.
Telenor is monetizing its 25-year run in Thailand by selling its entire stake in True Corporation, signaling a strategic refocus and a maturing Asian portfolio. Telenor agreed to sell 24.95% of True Corporation to Arise Digital Technology Company Limited at THB 11.70 per share, with a mutual put/call option to transfer the remaining 5.35% two years after closing. The agreed valuation implies proceeds of roughly NOK 39 billion (about US$3.9 billion) and represents a notable premium—around 36% over True’s first post-merger trading day close and about 4% over the recent three-month VWAP. The sale aligns with a broader pivot toward capital discipline, structural simplification, and a tighter Nordic focus.
France’s three other mobile network operators—Bouygues Telecom, Free-iliad and Orange—have reopened negotiations with Altice to carve up most of SFR, reviving a complex deal that could reshape competition, capex and customer experience across the market. The operators confirmed they are conducting due diligence with Altice after re-engaging in early January 2026, stressing that legal and financial terms remain undecided and that there is no assurance of a transaction. A successful transaction would compress the French market from four to three MNOs, with material consequences for pricing power, 5G/fiber investment, vendor ecosystems and enterprise buyers. Consolidation momentum is building across Europe, evidenced by recent approvals of large transactions with stringent remedies. Altice has been under sustained pressure to reduce debt following restructurings and asset sales.
CEO Börje Ekholm indicated the company will keep trimming headcount after cutting roughly 5,000 positions over the last year. In Sweden, Ericsson has notified authorities and begun union talks that could affect about 1,600 roles, part of a multi‑year restructuring program. The move follows a 2023 plan to remove around 8,500 jobs worldwide—about 8% of its workforce—with further reductions last year in markets such as Spain and Canada. The rationale remains consistent: reset the cost base, protect profitability, and keep investment firepower for strategic bets amid a slower operator capex cycle.
Ericsson is signaling a strategic shift toward defence, mission-critical, and AI-era network architectures as traditional RAN spending stays flat. Management expects the global RAN market to remain flat in 2026, sustaining a multi-year trend that now pegs annual spend at roughly the low-$30 billions. Ericsson is building for a traffic mix shift where AI applications push uplink throughput and latency to the forefront. Defence, utilities, transport, and public safety are moving from proprietary systems to standards-based 3GPP networks.
BlueBird 7 is slated to lift off in late February from Launch Complex 36 at Cape Canaveral Space Force Station on the New Glenn-3 mission. It is AST SpaceMobile’s first payload on New Glenn and the second satellite in its next-generation “Block 2” campaign, following BlueBird 6. BlueBird 7 mirrors BlueBird 6 and carries a deployable array of about 2,400 square feet—the company positions it as the largest commercial communications aperture in low Earth orbit. The design, backed by thousands of patent and patent-pending claims, is engineered to deliver peak downlink rates up to 120 Mbps directly to standard, unmodified devices for voice, data, and video.
GlobalGPT’s new mobile app signals a step change in how multimodal AI is consumed—shifting advanced reasoning, image and video generation, and research assistance into a pocketable, enterprise-ready workflow. With app availability on Google Play and support for both Android and iOS ecosystems, enterprises can plan for cross-device continuity, enabling employees to start a task on desktop and continue on mobile with minimal friction. GlobalGPT routes user prompts to advanced models such as GPT-5.2, Claude Opus 4.5, and Gemini 3 Pro to tackle analysis, explanations, and decision support beyond basic Q&A.

Frequently Asked Questions

What actually makes 5G different from 4G LTE?
5G introduces three core technical improvements over 4G LTE: significantly higher peak data speeds, in some cases multiple gigabits per second under ideal conditions compared to 4G’s typical tens to low hundreds of megabits per second; substantially lower latency, the delay between sending and receiving data, which matters for applications like gaming, video calls, and industrial automation where responsiveness is critical; and far greater device density support, allowing a single cell site to maintain reliable connections with a much larger number of simultaneous devices, which matters increasingly as IoT sensors and connected devices proliferate. These improvements come from a combination of new radio technology, additional spectrum bands made available for 5G use, and a redesigned network architecture that’s considerably more flexible and software-driven than 4G’s architecture was.
What’s the difference between low-band, mid-band, and high-band (mmWave) 5G?
Low-band 5G uses similar frequencies to 4G LTE, offering wide coverage area and good building penetration but speeds not dramatically faster than good 4G performance, making it most useful for extending broad geographic coverage rather than delivering 5G’s headline speed improvements. Mid-band 5G offers a more balanced tradeoff between coverage and speed, generally delivering meaningfully faster performance than 4G across a reasonably wide area, and has become the most common band used for mainstream 5G deployment in most markets globally. High-band 5G, often called mmWave, delivers by far the fastest possible speeds, but its very short range and poor ability to penetrate walls means it’s typically deployed only in dense, high-traffic urban areas like stadiums, rather than for broad area coverage.
What’s the difference between 5G NSA (non-standalone) and 5G SA (standalone)?
5G non-standalone, or NSA, runs 5G radio technology on top of an existing 4G core network, meaning certain control functions still rely on 4G infrastructure even though the actual data connection itself uses 5G radio technology; this was the faster, easier path many operators took for their initial 5G launches, since it could be deployed by upgrading existing 4G infrastructure rather than building an entirely new core network from scratch. 5G standalone, or SA, uses an entirely new, independently functioning 5G core network rather than relying on 4G at all, unlocking more of 5G’s distinctive advanced capabilities, including network slicing and the lowest possible latency, that NSA architecture generally can’t fully support. Many operators have been gradually transitioning from NSA to SA, though this migration has generally taken longer than initially anticipated.
How widespread is 5G coverage and adoption globally in 2026?
5G has become genuinely widespread rather than experimental. Global subscriptions surpassed 3.1 billion in early 2026, with another 162 million subscriptions added in just the first quarter of the year, reflecting continued strong growth even years after 5G’s initial 2019 commercial launch. Coverage varies considerably by region and band: low and mid-band 5G now reaches the substantial majority of the population in most major markets including the U.S., much of Europe, China, and South Korea, while high-band mmWave coverage remains considerably more limited and concentrated in dense urban areas given its short range. Adoption has progressed furthest in markets with aggressive early infrastructure investment, particularly China and South Korea, while other regions, especially parts of the developing world, continue working through earlier stages of 5G buildout.
What is ‘5G-Advanced,’ and how is it different from regular 5G?
5G-Advanced, sometimes marketed by certain vendors and operators, particularly in China, as 5.5G, refers to the next phase of 5G standards development beyond the original 2019 specification, formalized starting with 3GPP Release 18 and continuing through subsequent releases. It introduces capabilities including better support for reduced-capability IoT devices that don’t need full 5G performance, tighter integration with non-terrestrial satellite networks, more sophisticated AI-native network management built directly into the standard, and further uplink and capacity improvements beyond the original 5G specification. Rather than representing a completely new generation the way 5G itself was relative to 4G, 5G-Advanced is best understood as a substantial, ongoing evolution and refinement of the existing 5G standard, extending its useful commercial life well beyond what the original 2019 specification alone delivered.
Why do real-world 5G speeds vary so much between users and locations?
Real-world 5G speeds vary considerably because of the fundamental tradeoffs between different frequency bands: a user connected to low-band 5G in a rural area will experience meaningfully slower speeds than someone connected to mid-band 5G in a well-covered urban area, who in turn will experience slower speeds than someone briefly connected to high-band mmWave near a stadium or dense downtown location. Network congestion also plays a significant role, since a cell site serving many simultaneous users, particularly during peak usage periods, will generally deliver lower per-user speeds than the same site serving fewer users. Device capability matters too, since a phone’s specific modem chip determines which frequency bands and 5G features it can actually access, meaning even within the same coverage area, different devices can experience meaningfully different real-world performance.
Is 5G actually necessary, or is 4G still ‘good enough’ for most uses?
For many everyday tasks like browsing, messaging, and standard video streaming, 4G genuinely remains adequate, and many consumers report not noticing a dramatic difference in daily use compared to a well-performing 4G connection, which is part of why 5G monetization has proven harder than the industry initially expected. However, 5G’s advantages become considerably more apparent for specific use cases: dense urban areas with heavy simultaneous network usage benefit meaningfully from 5G’s greater capacity, fixed wireless access using 5G can deliver genuinely faster home broadband than many alternatives, and emerging applications like cloud gaming, AR and VR, and industrial automation benefit directly from 5G’s lower latency and higher reliability in ways 4G generally can’t match. Whether 5G feels necessary depends heavily on a specific user’s actual usage patterns and location rather than being a universal yes or no answer.
How does 5G relate to other technologies like network slicing, private networks, and FWA covered elsewhere in this reference?
5G is the foundational technology underlying many of the more specific capabilities covered elsewhere in this reference. Network slicing depends specifically on 5G standalone’s more flexible core network architecture to create multiple differentiated virtual networks on shared infrastructure. Private networks increasingly use 5G rather than 4G LTE as their core technology for new deployments, given 5G’s superior capacity and lower latency for industrial use cases. Fixed wireless access has become one of 5G’s clearest commercial monetization successes, using 5G’s speed and capacity to deliver home broadband as an alternative to cable or fiber. Open RAN’s disaggregated, multi-vendor approach to radio equipment is increasingly being applied specifically to 5G network deployments, making 5G the underlying connectivity layer most other categories in this reference build upon.


Partner Hubs

Telco AI Agent Leadership

Telco AI Agent Leadership Landscape - Network Equipment Vendors
Network Equipment Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
OSS/BSS Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
System Integrator Report
Scroll to Top