Private Network
Intelligence
Intelligence Journeys
Utilities Private Broadband Planning
AI Use Case Planning for Utilities

Investment

Telefónica has launched a 2026–2030 plan to accelerate growth, simplify operations, and unlock up to €3 billion in savings while doubling down on its core markets and technology investments. Revenue is guided to a 1.5%–2.5% CAGR from 2025–2028, accelerating to 2.5%–3.5% in 2028–2030; adjusted EBITDA is guided to the same ranges across the two periods. Telefónica targets a gross impact of up to €2.3 billion in 2028 and €3 billion by 2030, driven by technology and operational excellence, process simplification, digital transformation, and monetization of legacy network assets as shutdowns progress.
OECD data shows fixed and mobile broadband have shifted from build-out to scale-up, with fibre and 5G underpinning a new phase of digital infrastructure. Fixed broadband penetration across the OECD rose to 36.5 subscriptions per 100 inhabitants by end-2024, up from 32 in 2019, while the fibre share of fixed lines jumped from 28 percent to 47 percent over the same period. Gigabit-tier offers (≥1 Gbps) moved from 4 percent of subscriptions in 2019 to 19 percent in 2024, signaling both wider availability and growing appetite for very high throughput. On mobile, average monthly data consumption per subscription increased 2.5x—from 6 GB at end-2019 to 15 GB in 2024, aligned with more video, cloud, and AI-assisted applications shifting to handhelds and connected devices.
Orange has reached a non-binding agreement to acquire Lorca’s 50% stake in MasOrange for €4.25 billion in cash, aiming for sole control of Spain’s leading operator by customer base. The transaction would shift MasOrange from joint control (Orange and Lorca JVCO, owner of MásMóvil) to full ownership by Orange. Full control simplifies governance, accelerates synergy capture, and gives Orange greater flexibility in network investment, pricing, and product roadmap execution in Spain. Orange expects to sign a binding agreement before end-2025, subject to agreement on final terms. Completion is targeted for the first half of 2026, assuming standard merger-control review.
TELUS has taken full ownership of TELUS Digital, a move designed to consolidate AI-powered customer experience, SaaS, and automation capabilities across its telecom, health, and agriculture businesses while unlocking material cost efficiencies. TELUS acquired all remaining TELUS Digital shares for US$4.50 per share, valuing the transaction at approximately US$539 million and issuing a small portion of TELUS common shares alongside cash to complete the deal; the entity will be delisted from the TSX and NYSE and cease public reporting. Management targets roughly US$150 million in annual efficiencies from automation, business simplification, and tighter cross-selling.
Hyundai Motor Group and NVIDIA are expanding their partnership to build a large-scale “physical AI” stack that fuses autonomous driving, smart factories, and robotics with national-scale infrastructure in Korea. The companies plan to stand up an AI factory built on 50,000 NVIDIA Blackwell GPUs to unify model training, validation, and deployment across vehicles and plants. Backed by an approximately $3 billion public–private investment, the effort includes a Physical AI Application Center, an NVIDIA AI Technology Center, and regional data centers developed in concert with Korea’s Ministry of Science and ICT.
NVIDIA and Nokia unveiled a strategic partnership to deliver commercial AI-RAN products built on NVIDIA’s Aerial RAN Computer Pro (ARC-Pro) platform and Nokia’s RAN software portfolio, with NVIDIA committing a $1 billion equity investment in Nokia at approximately $6.01 per share, subject to customary closing conditions. The companies are targeting an AI-native RAN that runs both radio workloads and AI inference on a software-defined, accelerated platform, with a cumulative AI-RAN market opportunity that Omdia estimates will exceed $200 billion by 2030. ARC-Pro is positioned as a 6G-ready accelerated computing platform that couples connectivity, compute, and sensing, enabling upgrades from 5G-Advanced to 6G largely via software.
Meta, Alphabet, and Microsoft signaled that AI infrastructure is now a multi-year capital priority measured in tens of billions per year. In their latest results, Meta guided capital expenditures into the $70–72 billion range with an even larger step-up expected the following year. Alphabet raised its 2025 capex outlook to $91–93 billion, up sharply from prior estimates. Microsoft reported $34.9 billion of capex in the most recent quarter, materially above expectations and up strongly year over year. These figures point to the largest synchronized build-out of compute, storage, and networking capacity in the history of cloud.
A renewed, three-year collaboration between Magic Leap and Google signals a pragmatic path to AI-capable AR glasses that prioritize visual quality, comfort, and manufacturability. Magic Leap is pivoting from building end-user headsets to becoming an ecosystem partner, offering waveguides, optics, device services, and manufacturing know-how to companies pursuing glasses form factors. The companies are aligning around Android XR, positioning the prototype showcased on stage at the Future Investment Initiative in Riyadh as a reference for future designs. The prototype highlights advances in see-through clarity, low-power displays, and an industrial design that approximates everyday eyewear.
India has ceded the lowest-tariff crown to Bangladesh and Egypt, yet it still leads on value through generous allowances and low data unit costs. Indian base plans commonly include unlimited voice, whereas Bangladesh and Egypt restrict voice to roughly 100 and 70 minutes respectively at entry level. On data, incremental purchase economics are unusually attractive: an extra Rs 100 typically buys around 26 GB, or about Rs 4 per GB, keeping India among the most affordable data markets globally. Even after adjusting for purchasing power parity, India remains at the affordable end of global tariff rankings.
SoftBank has reportedly approved the final $22.5 billion tranche of a planned $30 billion commitment to OpenAI, tied to the AI firm’s shift to a conventional for‑profit structure and a path to IPO. The investment completes a massive $41 billion financing round for OpenAI that began in April, making it one of the largest private capital raises in tech history. This funding and restructuring signal faster enterprise AI adoption, heavier infrastructure demand, and new platform dynamics that will ripple across networks, cloud, and edge. OpenAI is pushing deeper into enterprise tools, security features, and domain‑specific assistants.
Verizon signed a commercial agreement with Eaton Fiber, an affiliate of Tillman Global Holdings, to extend fiber-to-the-premises service well beyond its current Fios footprint and the locations it expects to add through its planned Frontier deal. The structure is straightforward. Eaton Fiber will fund, build, and operate the local access network. Verizon will handle sales, marketing, and customer care and gain full residential retail exclusivity on the new builds during deployment and for a subsequent period. Fiber is the control point for converged services.
AT&T’s third quarter shows steady operational execution in wireless and fiber, supported by portfolio moves that aim to strengthen capacity, reach, and cash generation through 2027. AT&T reported Q3 2025 revenue of $30.7 billion, up 1.6% year over year, with diluted EPS of $1.29 boosted by a gain related to the sale of its DIRECTV investment; adjusted EPS was $0.54, roughly flat year over year. Free cash flow improved to $4.9 billion from $4.6 billion a year ago, a key metric for debt reduction and capital returns. AT&T’s cross-sell between fiber and mobility is showing tangible traction in both net additions and churn control.
TECKNEXUS PRIVATE NETWORKS
Congratulations to the 2026 Award Winners
Explore the Winners →

Partner Hubs

Telco AI Agent Leadership

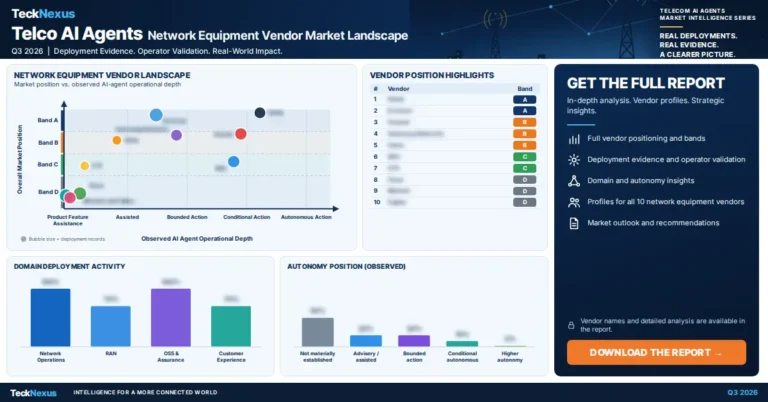
Telco AI Agent Leadership Landscape - Network Equipment Vendors
Network Equipment Vendor Report
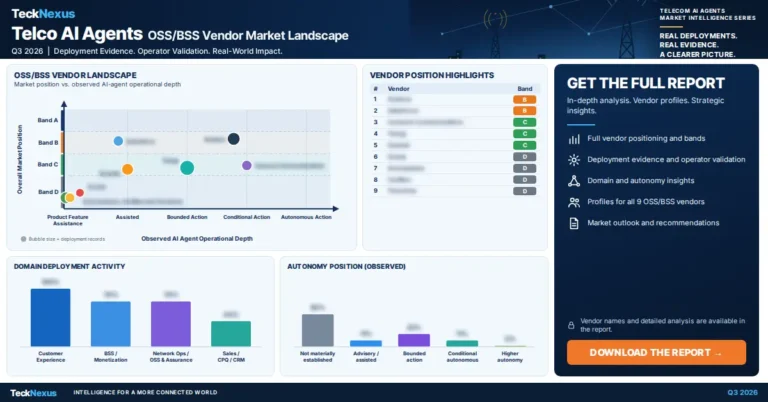
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
OSS/BSS Vendor Report
How are Amdocs, Salesforce, Comarch, Totogi, Qvantel, Oracle and other OSS/BSS vendors deploying telecom AI agents?
System Integrator Report
Scroll to Top